The Short Answers
- The average Filipino net worth is estimated at around $12,000–$15,000 per adult, though this masks extreme disparities between urban and rural populations.
- Overseas remittances account for roughly 10% of GDP, making them the single largest driver of household wealth for millions of families.
- Top earners—often business elites or overseas professionals—can see net worth figures in the multi-million range, but wealth concentration remains high.
- Cultural norms, such as utang na loob (debt of gratitude), often delay individual wealth accumulation in favor of familial or community obligations.

Deep Dive: The Full Picture
The Filipino net worth story is fundamentally shaped by migration. Since the 1970s, the Philippines has become the world’s largest exporter of nurses, caregivers, and skilled labor, with over 10 million Filipinos living abroad. These workers don’t just contribute to GDP—they redefine what wealth means for their families. A single OFW’s savings can fund a sibling’s education, a parent’s retirement, or even a small business back home. This intergenerational wealth transfer is less about personal balance sheets and more about social capital. Domestically, wealth accumulation faces structural hurdles. The Philippines has one of the lowest savings rates in Asia, partly due to high inflation and limited access to formal banking for informal-sector workers. Meanwhile, the real estate market—often a wealth-building tool elsewhere—is dominated by a small elite, pushing prices beyond reach for the average Filipino. The result? A bifurcated wealth ecosystem: those who can leverage overseas income or inherit land see their net worth grow, while others remain trapped in a cycle of consumption-driven living.The Context You Need
Historically, the Philippines’ economy has been remittance-dependent long before it became a global trend. Under Marcos, labor export policies were framed as a solution to unemployment, not a long-term economic strategy. Decades later, the system persists, with 80% of remittances going to families in the bottom 60% of the income distribution. This creates a paradox: while remittances boost GDP, they also reinforce inequality by making wealth accumulation dependent on individual migration rather than systemic economic growth. Cultural attitudes toward money further complicate the picture. The concept of pakikisama (harmony) often translates to reluctance in aggressive wealth-building, while bahala na (leave it to fate) can delay financial planning. Even among the affluent, Filipino net worth is frequently measured in relationships as much as assets—land inherited from grandparents, businesses passed down, or connections that open doors. This contrasts sharply with Western models where wealth is often tied to liquid assets or stock portfolios.The Mechanics
For the average Filipino, net worth growth hinges on three pillars: remittances, real estate, and informal savings. OFWs prioritize sending money home through cash-to-cash transfers, often via remittance hubs like Palawan or Cebu, where exchange rates are favorable. These funds rarely sit in bank accounts; instead, they’re used to pay off debts, build homes, or fund education—tangible assets that appreciate slowly if at all. The wealthy operate differently. High-net-worth individuals (HNWIs) in the Philippines—those with $1 million+ in assets—tend to be business owners, corporate executives, or overseas professionals who’ve repatriated capital. Their strategies involve diversifying into foreign currencies, luxury real estate, or blue-chip stocks, often through offshore accounts. The Bangko Sentral ng Pilipinas estimates that Filipino net worth held abroad exceeds $100 billion, though much of it remains untaxed due to complex legal structures.Details That Change the Picture
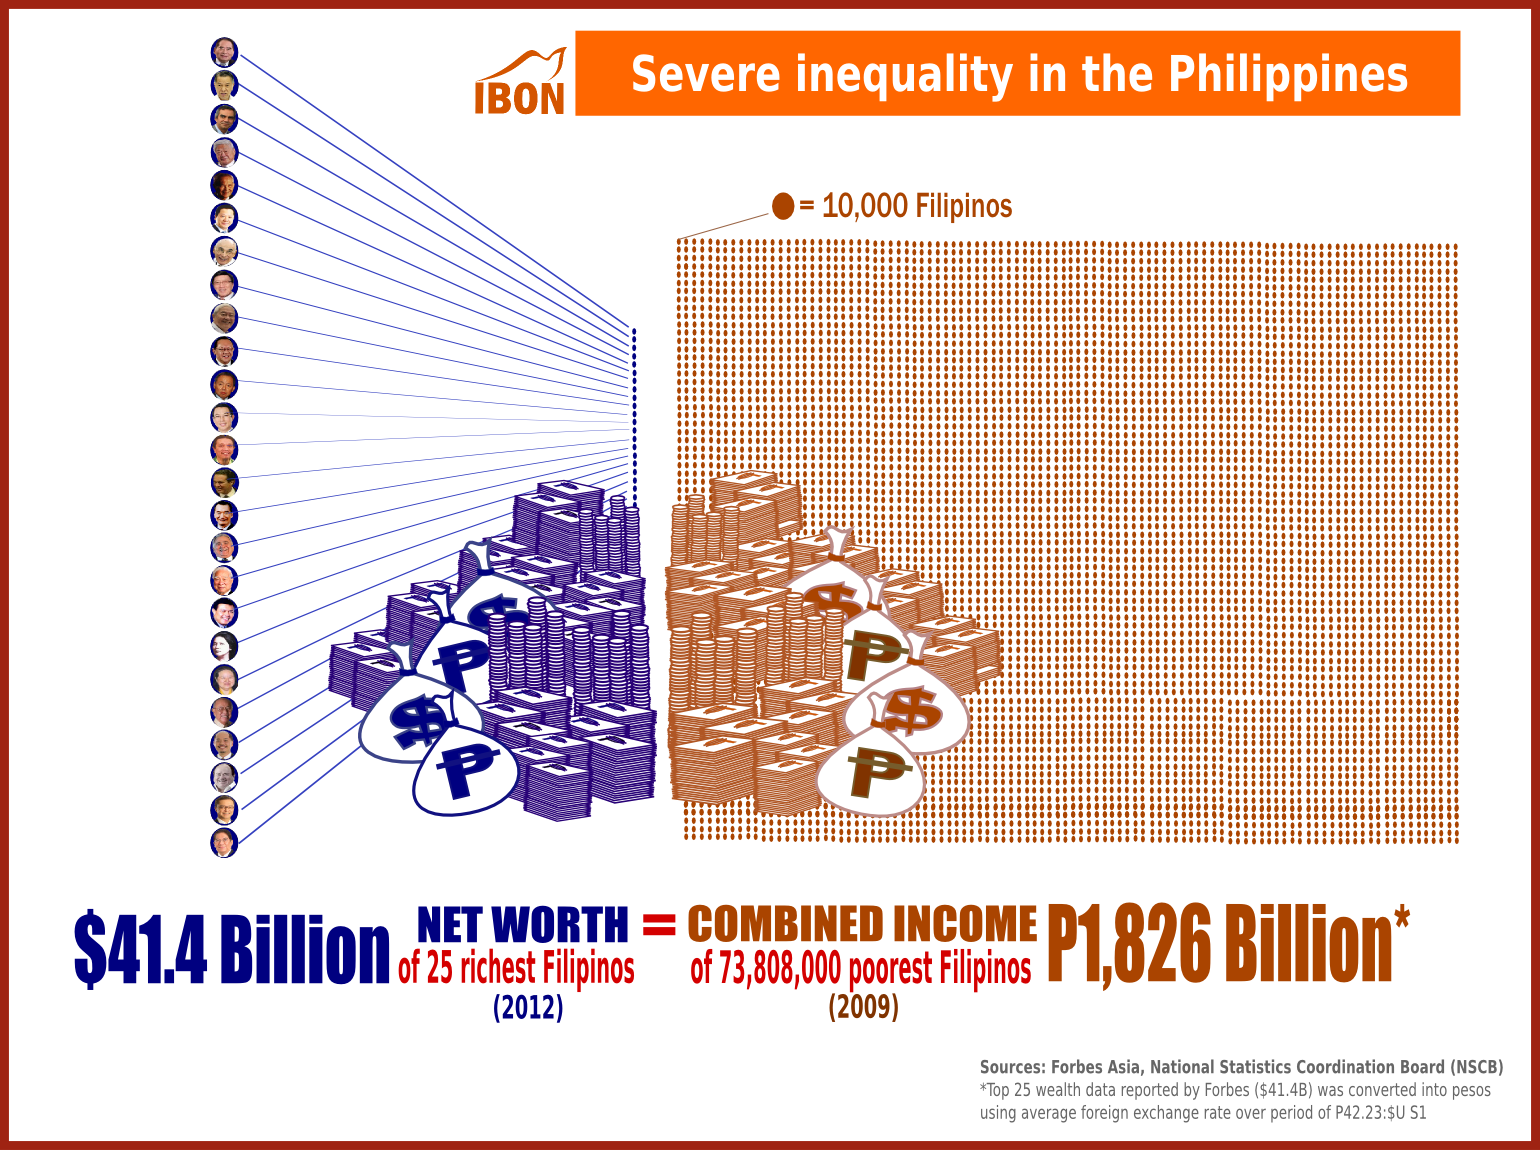
The Philippines’ wealth distribution is one of the most skewed in Southeast Asia. According to the World Inequality Database, the top 10% hold 50% of national wealth, while the bottom 50% control just 3%. This isn’t just about income—it’s about asset ownership. Land remains the primary store of wealth for the elite, with agrarian reforms failing to redistribute property effectively. Meanwhile, the middle class, though growing, faces stagnant wages and rising costs, making it harder to accumulate savings. A lesser-discussed factor is the gender wealth gap. Women, who make up 60% of OFWs, often see their earnings pooled into household expenses rather than personal assets. Even when they return home, cultural norms discourage them from controlling family finances. This systemic exclusion means that while Filipino women may contribute disproportionately to national wealth, their individual net worth lags behind male counterparts."Wealth in the Philippines isn’t just about money—it’s about who you know and what you can pass on. For most families, the real net worth isn’t in the bank; it’s in the relationships that keep the money flowing." — Economic sociologist Maria Santos, University of the Philippines
| Metric | Key Statistic |
|---|---|
| Average adult net worth (2023 est.) | $12,000–$15,000 |
| Top 1% wealth share | ~30% of total assets |
| OFW remittance share of GDP | ~10% |
| HNWI growth (2018–2023) | ~40% (slowing post-pandemic) |

Conclusion
The Filipino net worth is a mosaic of global labor, cultural norms, and systemic inequalities. For millions, wealth is a collective project—one where an individual’s success abroad directly lifts their family’s standing at home. Yet for others, the barriers to building personal wealth remain insurmountable, trapped in cycles of debt or informal economies. The country’s financial future will depend on whether it can move beyond remittance dependency and create pathways for domestic wealth accumulation. What’s clear is that traditional measures of net worth—stocks, real estate, cash—only tell part of the story. In the Philippines, social capital and transnational networks often outweigh liquid assets. The challenge ahead isn’t just economic; it’s cultural and political. Without addressing how wealth is inherited, shared, and taxed, the gap between the Filipino net worth of the elite and the average citizen will only widen.Comprehensive FAQs
Q: How do remittances impact the average Filipino’s net worth?
Remittances are the primary driver of household wealth for millions, often funding home ownership, education, or small businesses. However, because these funds are frequently spent on consumption rather than saved, their long-term impact on individual net worth is limited unless invested in appreciating assets like land or stocks.
Q: Are there tax incentives for Filipinos to repatriate wealth?
The Philippine government offers tax holidays for certain investments, such as the Special Economic Zones Act, which can benefit repatriated capital. However, many high-net-worth Filipinos use offshore accounts to avoid capital gains taxes, leading to debates over tax reform. The BIR has tightened scrutiny on undeclared foreign earnings, but enforcement remains inconsistent.
Q: How does the Philippines compare to other Southeast Asian nations in wealth distribution?
The Philippines has higher inequality than neighbors like Vietnam or Thailand, with the top 10% holding a larger share of wealth. Unlike Singapore or Malaysia, where state-driven industrialization created a broader middle class, the Philippines’ wealth growth has been remittance-dependent, reinforcing asset concentration among elites and landowners.
Q: What are the biggest threats to growing Filipino net worth?
The three biggest risks are:
- Inflation: The Philippines has seen double-digit inflation in recent years, eroding savings and asset values.
- Limited financial literacy: Many Filipinos lack access to investment education, leading to poor asset allocation.
- Political instability: Frequent policy shifts—such as sudden tax hikes or currency devaluations—disrupt long-term wealth planning.
Q: Can the next generation of Filipinos expect higher net worth than their parents?
It depends on geographic and social mobility. Urban professionals in tech or finance may see growth, but rural families reliant on remittances face stagnation unless migration patterns shift. The key variable will be whether the Philippines develops high-paying domestic jobs or if its economy remains tied to low-wage labor exports.
