
The Short Answers
- The FAFSA assumes property net worth equals quick-sale proceeds, not appraised value—even if selling fast means accepting a lower offer.
- If you sell property before the FAFSA filing deadline, the proceeds become reportable income for the next tax year, potentially increasing your EFC.
- Assets held in trusts or LLCs may be treated differently, but the FAFSA still expects realistic liquidation timelines (typically 12–18 months).
- Tax implications (capital gains, depreciation recapture) don’t factor into FAFSA calculations—only the net sale amount matters for aid eligibility.
- Consulting a financial aid advisor before selling high-value property can prevent overpaying for college or losing aid due to misreported asset values.
Deep Dive: The Full Picture
The FAFSA’s asset rules operate on a hypothetical liquidation model: it assumes you could sell any asset—including a primary residence, rental property, or undeveloped land—within a reasonable timeframe and at a price close to fair market value. This assumption is baked into the net worth formula, where property values are subtracted from total assets to determine how much a family can contribute to college costs. But the reality of forced or expedited sales rarely aligns with this model. A homeowner might list a property at $800,000, but after six months of stagnant offers, they accept $720,000—leaving them with $80,000 less in liquid assets than the FAFSA originally assumed they’d have.
The problem deepens when families attempt to time asset sales with FAFSA deadlines. For example, selling a vacation home in January to fund summer tuition might seem logical, but the FAFSA treats the proceeds as available income for the following year’s aid cycle. This creates a paradox: liquidating assets to pay for college can increase your EFC by making more money reportable. The FAFSA’s asset protection allowance (which exempts a portion of home equity) doesn’t shield proceeds from sales—only the original value of the home at the time of purchase. This means that even if you’ve lived in a home for decades, selling it triggers a reassessment of your reportable net worth based on current market conditions.
#### The Context You Need
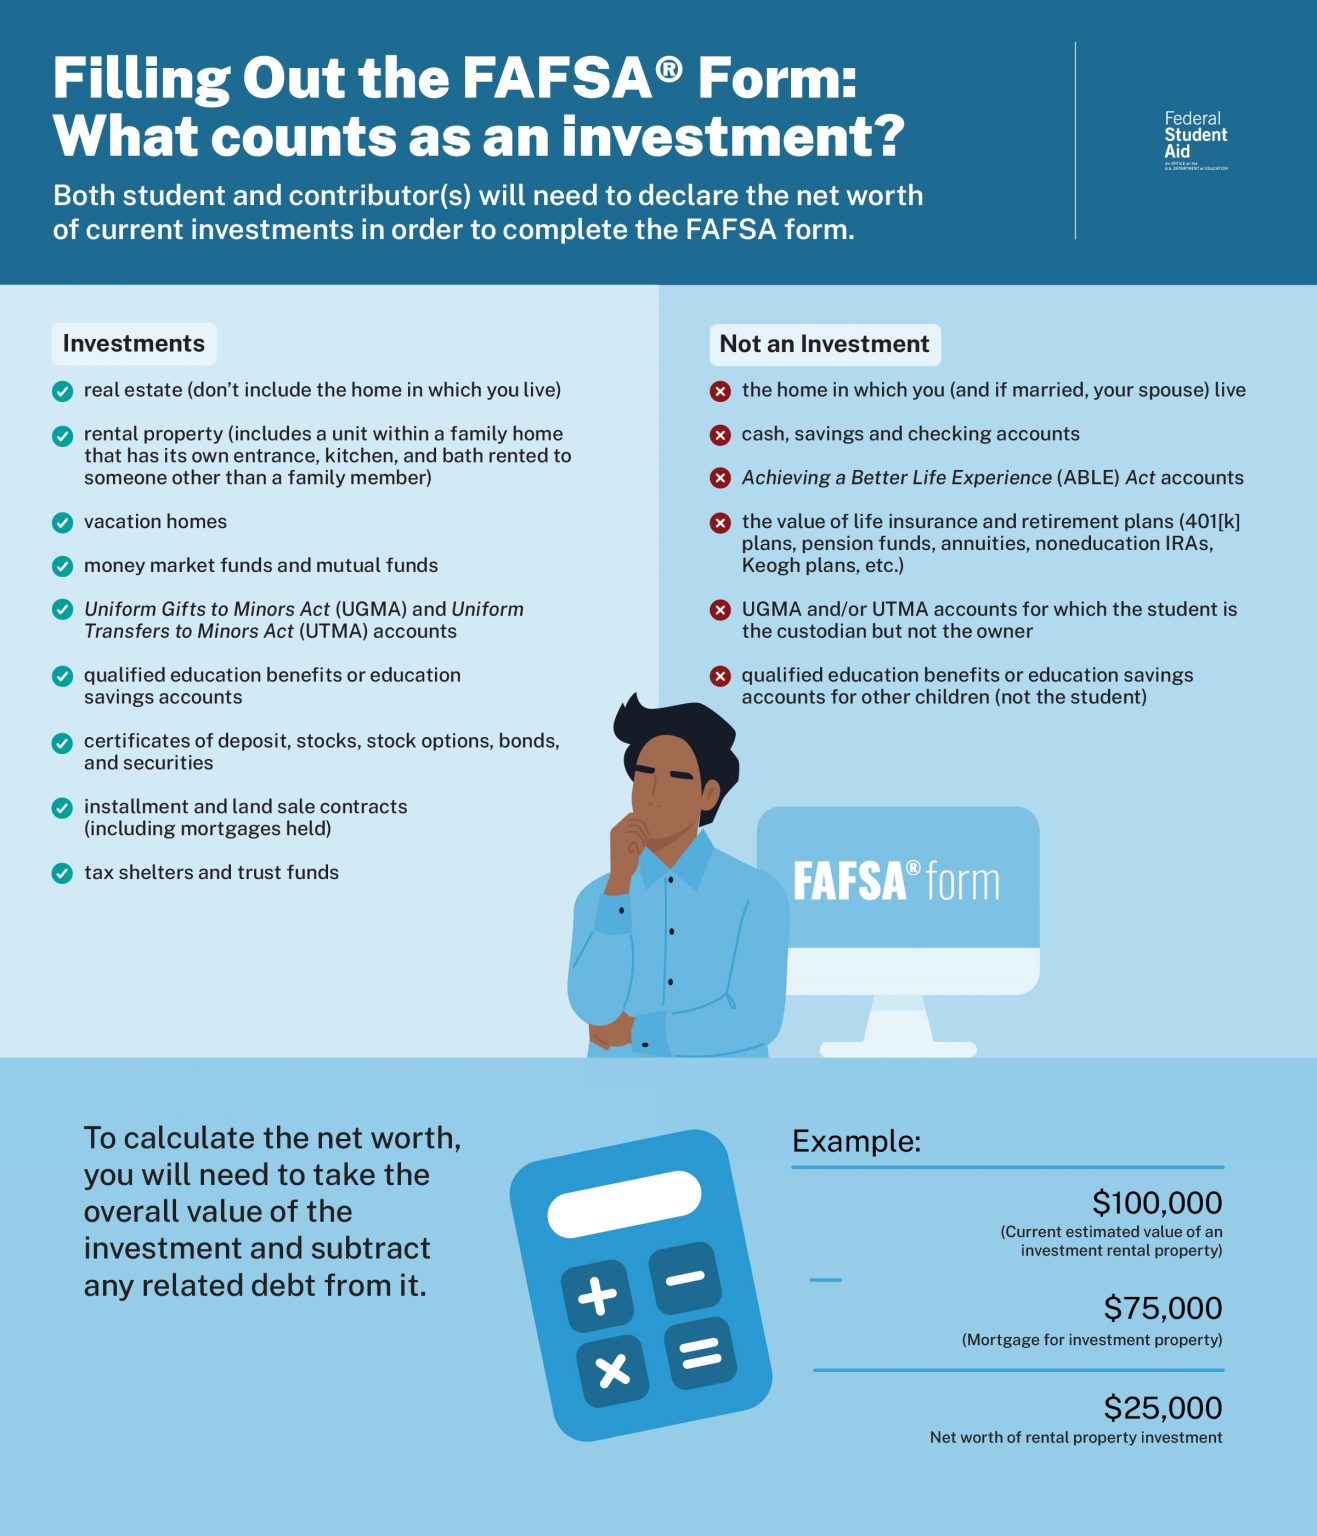
The FAFSA’s treatment of property stems from its need-based aid philosophy: the government expects families to contribute to college costs based on their demonstrated ability to pay, not just current cash flow. Property is classified as a non-liquid asset, but the FAFSA doesn’t distinguish between readily marketable assets (like stocks) and illiquid ones (like a single-family home in a slow market). This creates a valuation gap—the difference between what an asset is worth and what it would realistically fetch in a quick sale. For example: - A rental property in a high-demand city might appraise at $1.2 million but sell for $1 million after agent fees and repairs. - Undeveloped land in a rural area could have a high assessed value but no buyers willing to pay it. - A primary residence with sentimental value might sit unsold for years, forcing a family to accept a discounted offer to avoid foreclosure. The FAFSA doesn’t adjust for these scenarios. Instead, it uses appraised or purchase prices (whichever is lower) as the baseline for net worth calculations. This means that if you underreport a property’s value to qualify for more aid, you risk audits or penalties—but if you overreport, you may pay thousands in unnecessary college costs. ####The Mechanics
The FAFSA’s asset rules are governed by Federal Student Aid (FSA) Handbook Volume 3, which outlines how property is assessed. Key mechanics include: 1. Home Equity Exemption: The first $20,000 of home equity (or $40,000 for married couples) is not counted toward net worth. However, any equity above this threshold is fully reportable—regardless of whether the home is mortgaged. 2. Non-Primary Residences: Vacation homes, rental properties, and investment real estate are fully counted at their current fair market value, even if they’re encumbered by debt. 3. Sale Proceeds Timing: If you sell property after the FAFSA filing deadline but before the aid year starts, the proceeds do not affect that year’s EFC. However, they will be considered for the next year’s FAFSA, potentially reducing aid eligibility. 4. Debt Deduction: Mortgages and liens reduce net worth, but only if they’re secured by the property in question. Unsecured debt (like credit cards) doesn’t offset property values. The critical variable here is what the FAFSA considers a "reasonable" sale timeline. While the FAFSA doesn’t specify an exact window, financial aid experts generally agree that any sale expected to take longer than 12–18 months should be treated as non-liquid—meaning it won’t be fully counted toward net worth. However, this is not explicitly stated in FAFSA guidelines, leaving room for interpretation by aid officers.Details That Change the Picture
Not all property is treated equally under FAFSA rules. The type of property, ownership structure, and market conditions can drastically alter how net worth is calculated—and whether selling quickly will help or hurt aid eligibility. For instance:
- Primary residences benefit from the home equity exemption, but selling one before the FAFSA deadline can trigger a reassessment of liquid assets, increasing your EFC for the following year.
- Rental properties are fully counted at fair market value, but if you sell below market to avoid a long vacancy, the FAFSA may still expect you to report the higher appraised value—leading to overpayment.
- Inherited property is assessed at its current value, not the original purchase price. If you inherit a home worth $600,000 but sell it for $500,000 due to market downturns, the FAFSA will still use $600,000 in its net worth calculation.
Another critical factor is tax implications, which the FAFSA ignores entirely. Selling property often triggers capital gains taxes, reducing the actual liquid funds available for college. For example:
- A home sold for a $200,000 profit could owe $60,000 in taxes, leaving only $140,000 for tuition—yet the FAFSA will count the full $200,000 as available income for the next aid cycle.
> > "The FAFSA doesn’t care about your tax bill—it only cares about what you could have if you sold everything tomorrow." > —Mark Kantrowitz, publisher of SavingForCollege.com >To illustrate how these variables interact, consider the following scenarios:
| Scenario | FAFSA Net Worth Impact |
|---|---|
| Sell primary home at 90% of appraised value before FAFSA deadline. | FAFSA uses full appraised value in net worth calculation, increasing EFC for next year. |
| Rent out inherited property for 2 years before selling. | Rental income is reportable, but property value is frozen at purchase price (if lower than current market). |
| Use sale proceeds to pay off mortgage after FAFSA filing. | Proceeds are not counted in current year’s EFC, but reduce home equity for future filings. |
| Sell land with no zoning approval at 50% of assessed value. | FAFSA may disallow the discount, forcing full assessed value to be reported. |
| Transfer property to a child before selling. | FAFSA treats this as a gift, reducing parent’s net worth but increasing student’s assets (which hurt aid more). |

Conclusion
The FAFSA’s approach to property net worth is simplistic by design—it assumes assets can be liquidated at will, even when real-world constraints make that impossible. Families who sell property to fund college often find themselves in a worse position than if they had borrowed strategically or tapped home equity loans instead. The key takeaway is that on the FAFSA property net worth is what you would get if sold quickly? is a hypothetical benchmark, not a reflection of actual liquidity. Ignoring this distinction can lead to overpaying for education or losing aid eligibility due to misreported asset values.
The solution lies in proactive planning. Families should:
1. Consult a financial aid advisor before selling high-value property.
2. Avoid selling assets within 12–18 months of FAFSA deadlines unless absolutely necessary.
3. Explore alternatives like home equity loans, 529 plans, or private student loans to bridge funding gaps.
4. Document market conditions if selling below appraised value to justify lower reported values (though this is risky).
5. Monitor tax implications separately from FAFSA calculations—capital gains and deductions don’t affect aid, but they do affect disposable income.
The FAFSA’s asset rules are rigid, but they’re not insurmountable. Understanding the gap between appraised value and quick-sale proceeds is the first step in avoiding financial missteps that could cost tens of thousands in avoidable college expenses.
Comprehensive FAQs
#### Q: If I sell my rental property before the FAFSA deadline, will the full sale price count against my aid?
A: Yes. The FAFSA counts all proceeds from sales as available income for the next aid year, even if you use them to pay current tuition. The property’s original value (not the sale price) is used in the current year’s net worth calculation, but the proceeds become part of your reportable assets for the following FAFSA cycle.
####Q: Can I exclude the value of my primary home if I’m selling it to pay for college?
A: Only if you keep the home equity exemption (up to $20K for singles, $40K for couples). If you sell the home before the FAFSA deadline, the full proceeds (minus mortgage payoff) become reportable income for the next year’s aid calculation. Selling after the deadline but before the aid year starts does not affect current-year aid—but the proceeds will be considered for the following year.
####Q: What if I sell property below market value due to a bad economy? Will the FAFSA accept the lower price?
A: No. The FAFSA uses fair market value (appraised or purchase price, whichever is lower) in its net worth calculations. Selling below market does not reduce your reported asset value—only the actual sale price affects your liquid assets for the next aid cycle. However, if you can document that the property was sold under duress (e.g., foreclosure, family emergency), you may have a case to adjust reported values, but this is not guaranteed and requires professional guidance.
####Q: Does the FAFSA care if I use sale proceeds to pay off debt instead of tuition?
A: Indirectly. While the FAFSA doesn’t track how you spend proceeds, reducing debt (like a mortgage) lowers your net worth for future filings. However, if you pay off student loans with sale proceeds, the FAFSA does not recalculate your EFC—it only looks at remaining assets. The bigger risk is that reduced debt may increase your future EFC if you no longer qualify for asset protection allowances.
####Q: Can I transfer property to my child to avoid FAFSA penalties?
A: No—this is a major red flag. The FAFSA treats gifts or transfers as available student assets, which are penalized more heavily than parental assets. For example, if you transfer a $300,000 property to your child, the FAFSA will count the full value against your student’s aid eligibility (up to 20% of the asset value reduces aid). Additionally, the IRS may treat this as a taxable gift if the property’s value exceeds the annual exclusion ($18,000 per recipient in 2023).
####Q: What’s the best way to use property sales to fund college without hurting aid?
A: The safest approach is to: 1. Sell property after the FAFSA deadline but before the aid year starts (e.g., sell in June 2024 for Fall 2024 tuition). 2. Use a home equity loan or HELOC instead of selling—this keeps the property’s value intact while providing liquid funds. 3. Borrow strategically (e.g., private loans, PLUS loans) to avoid triggering asset reassessments. 4. Consult a CPA and financial aid advisor to structure the sale in a way that minimizes tax and aid impacts.
####Q: How does the FAFSA treat inherited property differently from other assets?
A: Inherited property is assessed at its current fair market value (not the decedent’s purchase price) when reported on the FAFSA. If you hold the property for over a year, the FAFSA does not penalize you for its value—only liquid assets (like cash or stocks) are counted. However, if you sell inherited property quickly, the full proceeds become reportable income for the next aid cycle, just like any other sale.
####Q: What happens if I underreport property value to get more aid, but get audited later?
A: Severe penalties. The FAFSA considers intentional misreporting a federal offense. If audited, you may: - Owe back taxes on underreported income. - Lose eligibility for future aid. - Face civil penalties (fines up to $10,000 or 50% of the misreported amount). - Be flagged for fraud, which can affect scholarships and loans. Financial aid offices do not tolerate underreporting, and audits are increasing for high-net-worth families. Always err on the side of overreporting—it’s better to pay slightly more for college than risk legal consequences.
