Common Myths About the Empower Net Worth App
The Empower net worth app operates at the intersection of accessibility and sophistication, which makes it a magnet for misconceptions. One persistent belief is that it’s merely a fancy calculator—a tool for crunching numbers without adding real value. In reality, the app’s algorithmic backbone doesn’t just sum assets and liabilities; it simulates thousands of market scenarios to stress-test a user’s portfolio. Another myth frames it as a one-size-fits-all solution, ignoring that its customizable alerts and goal-setting modules adapt to everything from early-career savers to pre-retirees with complex estates. These oversimplifications stem from a broader industry tendency to conflate financial tools with either basic budgeting or high-end advisory—Empower occupies the middle ground where most people actually live. The confusion also extends to security. Some assume that linking multiple accounts—especially those with high balances—invites unnecessary risk. Yet the app employs bank-level encryption and read-only access, meaning no transactions are initiated through its platform. The real vulnerability isn’t the app itself, but users who neglect basic cyber hygiene, like reusing passwords across platforms. This misconception reveals a deeper issue: people often judge tools by their own habits, not their inherent design.Myth 1: It’s Only for the Ultra-Wealthy
The Empower net worth app’s ability to handle six- and seven-figure portfolios has led some to assume it’s irrelevant for average earners. In truth, its threshold-free architecture makes it useful at any income level. A freelancer with $50,000 in savings can use its cash-flow projections just as effectively as a physician with a diversified trust. The app’s strength lies in its scalability—whether you’re tracking a single brokerage account or a mosaic of real estate, private equity, and retirement funds. The misconception arises because marketing often highlights high-net-worth use cases, but the core functionality remains equally valuable for those with modest but growing assets. What often gets overlooked is how the app democratizes financial literacy. For someone with limited investing experience, seeing their net worth visualized alongside benchmarks (like age-based milestones) can be more educational than a semester of finance classes. The app doesn’t require prior knowledge—it builds it incrementally. This makes it particularly valuable for younger professionals who might otherwise dismiss it as “too complex” or “not for me yet.”Myth 2: It’s Just a Fancier Version of Mint
Comparing the Empower net worth app to Mint is like comparing a Swiss Army knife to a pocketknife—both serve basic purposes, but one does far more. Mint excels at transaction tracking and bill reminders, while Empower’s focus is on asset optimization and long-term planning. The latter doesn’t just categorize spending; it analyzes how every dollar contributes to (or detracts from) future wealth. For example, it might flag that your emergency fund is sitting in a low-yield savings account while high-yield alternatives exist. Mint wouldn’t catch that because it wasn’t designed to. The confusion persists because both apps fall under the “personal finance” umbrella, but their architectures serve different goals. Mint’s strength is operational—managing day-to-day finances—while Empower’s is strategic, aligning current actions with future objectives. This isn’t a competition; it’s a matter of recognizing that financial health requires both short-term discipline and long-term vision. The Empower net worth app fills the latter gap, which is why users often pair it with Mint or YNAB for a complete picture.Myth 3: Your Data Isn’t Really Safe
Security concerns about the Empower net worth app typically stem from two sources: a general distrust of digital finance tools and a lack of understanding about how the app interacts with banks. The reality is that Empower uses Plaid’s secure API, the same technology trusted by banks and credit unions to verify account details. No user credentials are stored on Empower’s servers—only encrypted tokens that allow read-only access. This is more secure than many traditional banking logins, which often require users to share passwords or answer security questions that can be phished. The bigger risk isn’t the app itself, but user behavior. For instance, someone who enables two-factor authentication on their bank account but not on their Empower login creates a weak link. The app’s security model is only as strong as the weakest link in the chain. Transparency reports from Empower also show that it undergoes regular third-party audits, a rarity among consumer finance apps. Yet the myth endures because security is intangible—users can’t see it, so they assume it’s not there.
What Holds Up to Scrutiny
At its core, the Empower net worth app delivers on three verifiable promises: real-time aggregation, actionable insights, and behavioral nudges. The aggregation isn’t just about pulling in account balances—it’s about reconciling discrepancies, like a 401(k) statement that doesn’t match the plan’s actual value. The insights go beyond generic advice; they’re tailored to a user’s specific risk tolerance, time horizon, and liquidity needs. And the nudges—like alerts when a credit card balance exceeds 30% of the limit—are designed to interrupt bad habits before they compound. What sets it apart from competitors is its portfolio stress-testing engine. While other apps might show a static net worth figure, Empower simulates how that number could shift under market downturns, inflation spikes, or unexpected expenses. This isn’t hypothetical; it’s based on historical data and Monte Carlo simulations. Users who’ve relied on this during volatile periods report feeling less reactive to market noise because they’ve already mentally prepared for worst-case scenarios.“Empower doesn’t just tell you where you stand—it shows you how to move forward. That’s the difference between a snapshot and a roadmap.” — Sarah Chen, Certified Financial Planner (non-affiliated)
| Common Belief | What the Evidence Says |
|---|---|
| The app is only useful for tracking investments. | It also monitors cash flow, debt payoff timelines, and even non-financial goals (e.g., saving for a home). |
| It’s too complex for beginners. | Onboarding guides users through setup step-by-step, and the dashboard simplifies complex data. |
| Your net worth is the only metric that matters. | The app tracks liquidity ratios, debt-to-income, and asset allocation—context that raw net worth lacks. |
| It replaces the need for a financial advisor. | It’s a collaboration tool—advisors use it to review client portfolios remotely, but it doesn’t replace human judgment. |
| The free version is useless. | Even the free tier provides core aggregation and basic goal tracking; premium unlocks advanced projections. |
Why the Confusion Persists
The Empower net worth app occupies a liminal space in the fintech ecosystem—it’s neither a bank, nor a robo-advisor, nor a budgeting tool. This ambiguity creates friction for users who expect clear categories. Additionally, the app’s subtle evolution over time has led to outdated perceptions. Early versions focused heavily on retirement planning, while recent updates prioritize liquidity and emergency preparedness. Those who adopted it years ago might not recognize its current capabilities, assuming it’s stagnant when it’s actually refining its approach. Marketing also plays a role. The fintech industry often frames tools as either “simple” or “powerful,” but Empower defies this binary. It’s simple enough for a first-time investor to grasp, yet powerful enough to handle a trust fund’s tax-lot optimization. This duality makes it hard to pitch—it doesn’t fit neatly into “for beginners” or “for experts” narratives. The result? Users either underestimate its depth or overestimate its limitations, both of which distort its true value.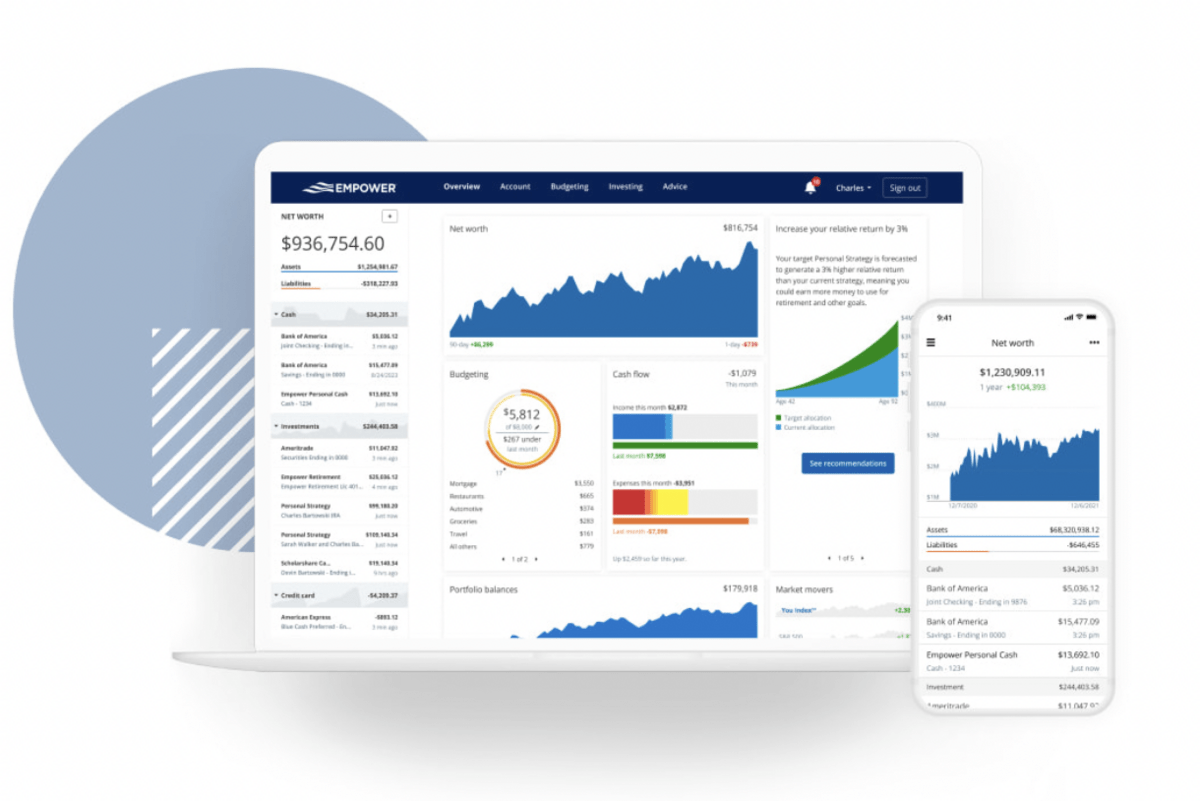
Conclusion
The Empower net worth app isn’t a panacea, but it’s one of the few tools that treats personal finance as a dynamic system, not a static ledger. Its strength lies in turning opaque data into actionable intelligence—whether that’s identifying a hidden fee drain or projecting how a side hustle could accelerate wealth growth. The myths around it reveal deeper truths about how people engage with money: many still view financial tools as either overly simplistic or prohibitively complex, when the best ones exist in the tension between the two. For those willing to look past the noise, the app offers a rare combination of granularity and clarity. It doesn’t just answer the question “How much do I have?”—it asks “What can I do with it?” That shift in perspective is what separates a net worth tracker from a financial co-pilot. The confusion will always linger, but the evidence is clear: for users who treat money as a strategic asset, Empower isn’t just another app—it’s a financial operating system.Comprehensive FAQs
Q: Is the Empower net worth app free to use?
The app offers a free tier with core features like account aggregation and basic goal tracking. Premium plans (starting around $10/month) unlock advanced tools such as portfolio stress testing, tax-lot optimization, and custom financial planning scenarios. Some employers or financial institutions also provide free access as part of employee benefits.
Q: Can I link my 401(k) or IRA to the Empower net worth app?
Yes, the app supports most major retirement accounts, including 401(k)s, IRAs, and 403(b)s. However, some plans—particularly those with unique investment options or employer stock—may require manual entry for certain holdings. The app’s support team can guide users through setup for less common account types.
Q: How does Empower protect my sensitive financial data?
The app uses bank-level encryption and Plaid’s secure API to connect accounts, ensuring no credentials are stored on Empower’s servers. It also employs read-only access, meaning no transactions are initiated through the platform. Users are encouraged to enable two-factor authentication on both their bank and Empower accounts for added security.
Q: Does the Empower net worth app work with international accounts?
Limited support exists for international accounts, primarily those in USD or major currencies like EUR or GBP. Accounts in less common currencies or those with non-standard banking structures may not sync fully. The app’s team is gradually expanding support for global users, but functionality varies by region.
Q: Can financial advisors use the Empower net worth app with clients?
Yes, Empower offers a Professional version designed for advisors to review client portfolios remotely. Advisors can access aggregated (but not transaction-level) data, set collaborative goals, and even send secure messages through the platform. This feature is particularly useful for hybrid advisory models where in-person meetings are less frequent.
Q: What happens if I close my Empower account?
Closing your account deletes all user data from Empower’s servers, but you can export a full financial summary before deletion. Linked accounts remain unaffected—you’ll need to manually remove Empower as a connected service from your bank or investment platform. The app provides a step-by-step guide during the closure process to ensure no data is left behind.
