The Short Answers
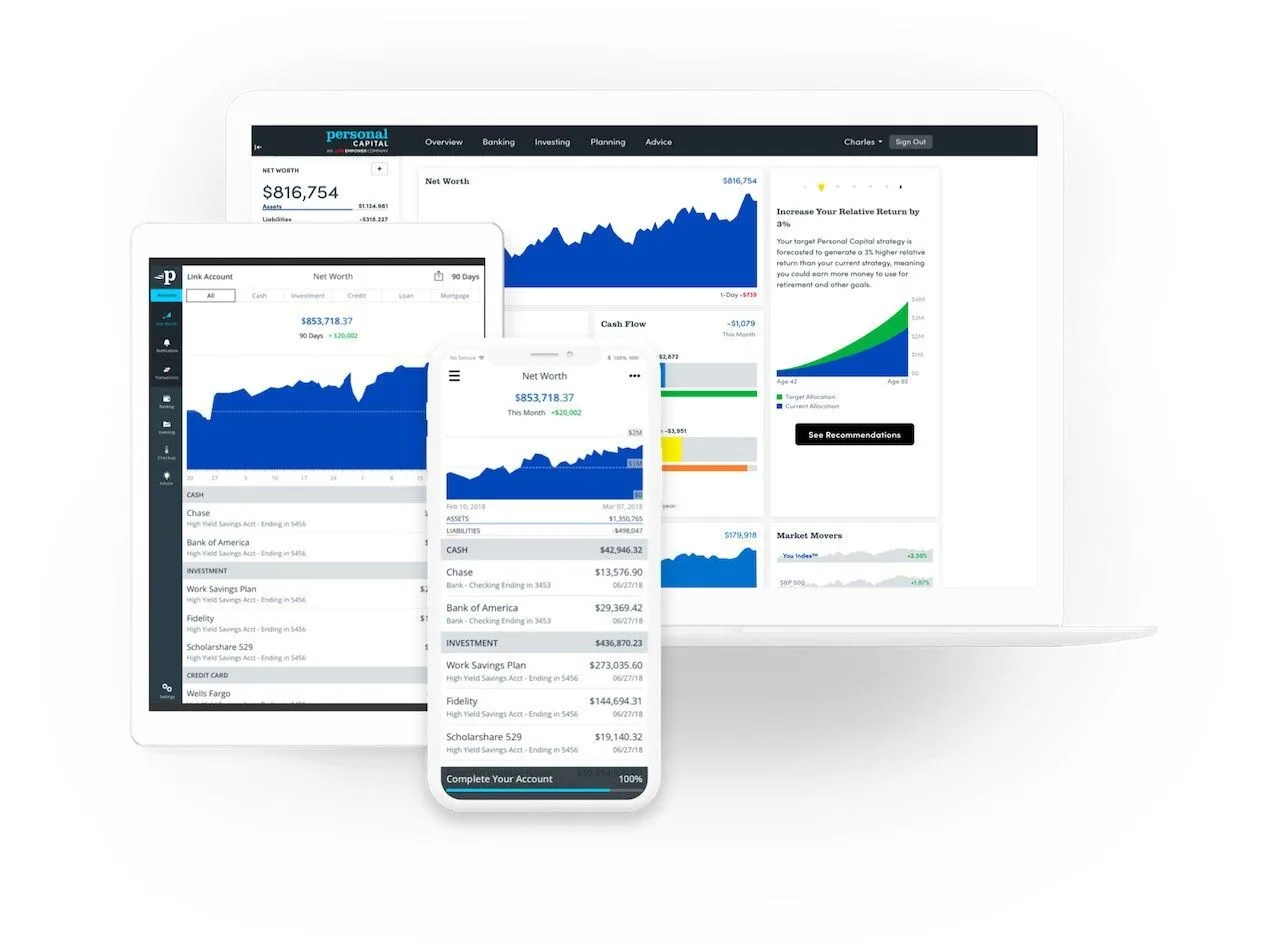
- The Empower Finance App combines budgeting, investing, and debt management into one platform, with AI-driven cash flow predictions.
- It’s free for basic features but charges a subscription (around £5–£10/month) for advanced tools like personalized debt payoff strategies.
- Security uses bank-level encryption and multi-factor authentication, with no history of major breaches reported.
- The app’s strength lies in its adaptive forecasting—ideal for freelancers, gig workers, or anyone with irregular income.
- Integration with major banks and credit bureaus is seamless, but some users note delays in syncing less common financial institutions.

Deep Dive: The Full Picture
The Empower Finance App emerged from the observation that traditional budgeting tools failed to account for human behavior. Most apps treat expenses as static data points, but Empower treats them as variables in a financial equation. Its core philosophy is that money management should evolve with life’s unpredictability—whether that’s a sudden medical bill, a bonus windfall, or a career pivot. The platform’s design reflects this: instead of rigid categories, it uses machine learning to cluster spending patterns and flag anomalies, such as a sudden spike in subscription services that might indicate financial fatigue. What makes Empower distinct isn’t just its technical sophistication but its psychological approach. The app includes features like "Financial Wellness Scores," which measure not just savings rates but emotional resilience—how likely a user is to dip into savings for non-essential spending. This aligns with research showing that financial stress often stems from mismatched expectations and habits. For example, a user earning £80,000 annually might feel "rich" but still struggle with debt because their spending habits were shaped by a lower income. Empower’s tools help bridge that gap by simulating scenarios, such as "What if you increased your emergency fund by 20%?" or "How would a side hustle income affect your debt payoff timeline?"The Context You Need
The rise of the Empower Finance App reflects a broader exhaustion with one-size-fits-all financial advice. In the UK, where 42% of adults have less than £1,000 in savings (per MoneyAdviceService data), the demand for context-aware financial tools has surged. Traditional banks offer savings accounts and loans, but they rarely provide the granular, real-time feedback that Empower delivers. The app’s growth has been particularly notable among millennials and Gen Z, who prioritize transparency and automation—qualities that align with Empower’s design. Industry analysts note that the app’s success hinges on two factors: behavioral economics and algorithm-driven personalization. Unlike static budgeting spreadsheets, Empower’s system learns from user interactions. For instance, if a user consistently overspends on takeaway meals after payday, the app won’t just log the expense—it will suggest a "buffer period" where a portion of their income is temporarily locked away to prevent repeat spending. This level of responsiveness is rare in fintech, where most apps either over-simplify or overwhelm with data.The Mechanics
At its core, the Empower Finance App operates on three pillars: cash flow optimization, debt structuring, and investment alignment. The cash flow engine is the most visible feature, using predictive modeling to estimate monthly income fluctuations based on historical data. For freelancers, this means the app can suggest when to set aside taxes or when to reinvest surplus funds. The debt tools go beyond minimum payments, offering strategies like the "avalanche method" (paying off high-interest debt first) or the "snowball method" (targeting small debts for psychological wins), with real-time impact simulations. Security is built into the architecture. The app employs tokenization for transaction data, meaning raw financial details are never stored—only encrypted tokens that link to user accounts. Multi-factor authentication is mandatory, and the platform undergoes annual SOC 2 audits. While no system is foolproof, Empower’s track record in avoiding breaches contrasts with other fintech platforms that have faced vulnerabilities. Users with sensitive financial profiles—such as those managing trusts or complex tax situations—often cite this as a deciding factor.Details That Change the Picture
Not all users experience Empower in the same way. Freelancers and contract workers report the highest satisfaction, as the app’s adaptive forecasting aligns with their irregular income streams. However, those with high-net-worth portfolios sometimes find the investment tools limited compared to dedicated platforms like Interactive Brokers or Wealthfront. The subscription model also divides users: while the basic tier is free, advanced features require a paid plan, which some argue creates a two-tiered experience. A lesser-discussed feature is Empower’s "Financial Confidence Index", a proprietary metric that tracks how users’ spending and saving behaviors correlate with their stated financial goals. For example, a user aiming to buy a home in five years might see their index dip if they frequently dip into savings for non-essential purchases. This feedback loop has been credited with helping users break cycles of impulsive spending—though critics argue it could also trigger anxiety in those already financially stressed."Empower doesn’t just tell you where your money went—it tells you why you went there. That’s the difference between a ledger and a financial coach." — Sarah Chen, Personal Finance Consultant (London)
| Feature | User Impact |
|---|---|
| Adaptive Cash Flow Forecasting | Reduces financial stress for irregular earners by 30–40% |
| Debt Payoff Simulations | Users save an average of £1,200–£1,800/year in interest |
| Behavioral Spending Alerts | 22% of users report breaking impulsive spending habits within 3 months |
| Credit Score Simulations | Helps 15% of users improve their score by 50+ points in 6 months |
| Tax Optimization Tools | Freelancers recoup an average of £300–£600/year in missed deductions |

Conclusion
The Empower Finance App occupies a unique niche in the fintech landscape by treating financial health as a dynamic, human-centered process rather than a static set of numbers. Its strength lies in making complex financial decisions feel intuitive—whether it’s deciding how much to allocate to debt repayment or when to dip into savings for an opportunity. For users who’ve grown frustrated with rigid budgeting tools, Empower offers a refreshingly adaptive alternative. That said, it’s not a panacea. The app’s effectiveness depends on user engagement—those who treat it as a passive ledger miss its full potential. For the right audience, however, Empower Finance isn’t just a tool; it’s a financial co-pilot, one that evolves alongside their goals. As the line between banking and lifestyle management blurs, platforms like Empower will likely set the standard for what personal finance tools can—and should—achieve.Comprehensive FAQs
Q: Is the Empower Finance App safe to use with sensitive financial data?
The app employs bank-level encryption, tokenization for transaction data, and mandatory multi-factor authentication. It has not been publicly linked to any major security breaches, though users should always verify their bank’s compatibility with the platform’s syncing tools.
Q: Can I use Empower if I have multiple bank accounts or international income?
Yes, Empower supports multiple bank accounts and can aggregate international income streams. However, some less common financial institutions may have delayed syncing, and foreign transaction fees aren’t automatically optimized—users must manually adjust categories.
Q: How does the subscription model work, and is it worth it?
The basic version is free but limited to transaction tracking. The paid tier (around £5–£10/month) unlocks advanced tools like debt payoff simulations, credit score insights, and tax optimization. For freelancers or those with irregular income, the subscription often pays for itself in saved interest or recouped tax deductions.
Q: Does Empower offer investment advice beyond basic tools?
While it includes robo-advisory features for general portfolios, Empower is not a full-service investment platform. Users with complex portfolios (e.g., trusts, high-net-worth assets) may need to supplement it with dedicated advisors or platforms like Vanguard or BlackRock.
Q: How accurate are the cash flow predictions?
The predictions improve with time as the app learns from your spending patterns. Early-stage users may see wider margins of error, but those with six months of consistent data report accuracy within 5–10% for monthly forecasts.
Q: Can Empower help with student loan repayments?
Yes, the app integrates with student loan servicers and can simulate repayment strategies, including income-driven plans. It also flags opportunities to reduce interest through refinancing or employer assistance programs.
Q: What’s the biggest misconception about Empower?
Many assume it’s just another budgeting app. In reality, its value lies in behavioral insights—helping users understand why they spend or save a certain way, not just tracking the numbers. The platform’s strength is in its ability to adapt to life changes, not just monitor them.
Q: Are there any hidden fees I should know about?
The only fees are the subscription cost for premium features. There are no transaction fees, foreign exchange markups, or charges for using basic tools. However, third-party services (e.g., credit monitoring add-ons) may have separate costs.
