The Short Answers
- The earnin app net worth was estimated at $100 million+ in its last major funding round (2021), though exact figures remain private.
- Earnin’s valuation relied on user engagement (millions of active users) and employer partnerships (e.g., Walmart), not traditional revenue streams.
- Its business model—voluntary tips for early pay access—made it unprofitable by conventional metrics, leading to its eventual acquisition.
- The app’s shutdown in 2023 left unanswered questions about whether its valuation was justified or if it was a speculative fintech bubble.
- Earnin’s legal risks—particularly around unregulated lending—were a key factor in its valuation challenges.
- Industry observers now view it as a case study in how fintech startups balance social impact with profitability.
Deep Dive: The Full Picture
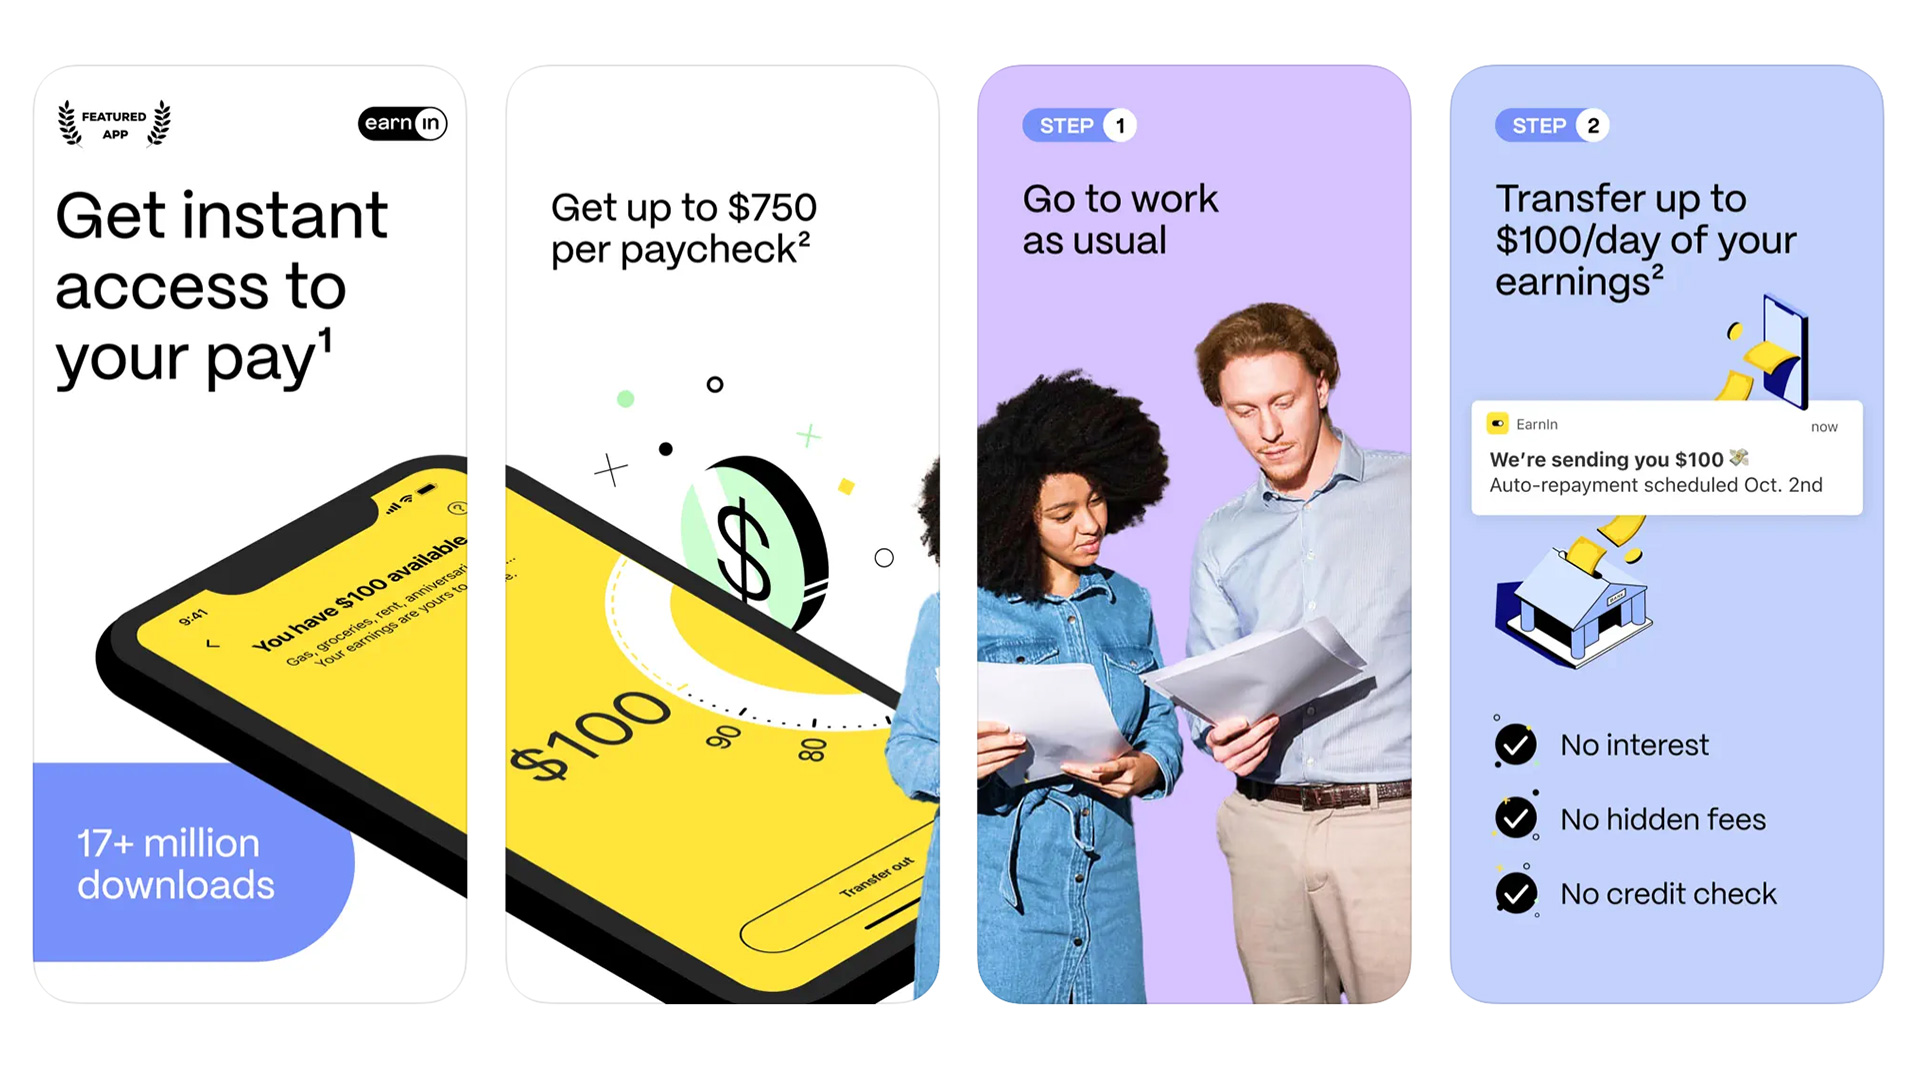
Earnin’s ascent wasn’t just about technology; it was about exploiting a gap in the financial system. The app allowed workers to withdraw up to $100 per day from their earned—but not yet paid—wages, using a tip-based system to fund advances. This avoided interest charges, which made it appealing compared to payday loans. But the earnin app net worth wasn’t just about user numbers. Investors bet on whether Earnin could scale beyond its core user base—primarily low-wage workers—and whether employers would adopt its "instant pay" infrastructure. The answer would determine if the valuation held.
The company’s funding rounds—backed by figures like PayPal co-founder Peter Thiel—hinted at a valuation that outstripped its revenue. By 2020, it had raised over $200 million, with estimates suggesting its worth could exceed $1 billion if it successfully monetized employer integrations. Yet those projections assumed a shift from tips to B2B revenue, a transition that never fully materialized. The earnin app net worth became a moving target, tied to unproven assumptions about corporate adoption and regulatory tolerance.
#### The Context You Need
The gig economy’s financial pain points were Earnin’s market. A 2019 Federal Reserve study found that 40% of Americans couldn’t cover a $400 emergency, and hourly workers were disproportionately affected. Earnin positioned itself as a lifeline, but its lack of underwriting made it a legal gray area. State usury laws treat advances as loans, and Earnin’s model—no interest, no credit checks—walked the line between innovation and exploitation. This ambiguity was baked into its valuation: investors weighed the risk of regulatory backlash against the potential to disrupt payroll systems. The app’s growth also reflected broader fintech trends. Companies like Dave and Chime had proven that neobanks could attract unbanked users, but none had tackled the timing of pay as directly as Earnin. Its valuation wasn’t just about user acquisition; it was about whether it could become a default infrastructure for employers. If Walmart or DoorDash adopted Earnin’s system, the earnin app net worth could skyrocket—but only if it could prove scalability beyond early adopters. ####The Mechanics
Earnin’s revenue model was deliberately unconventional. Users could access cash early by tipping the app, typically $0–$12 per withdrawal, with no hard cap. This created a freemium dynamic: the company’s survival depended on users voluntarily subsidizing the service. The earnin app net worth, then, was less about profit margins and more about user stickiness. Retention rates were high—many workers relied on the app weekly—but without a clear path to profitability, investors grew impatient. The company’s pivot to employer partnerships was critical. By integrating with payroll systems, Earnin could shift from consumer tips to B2B fees, charging businesses for instant pay access. This was the key to unlocking its valuation. Yet the transition was slow. Employers resisted the cost, and the app’s shutdown in 2023 suggested that the earnin app net worth may have been overstated—built on hopes rather than execution.Details That Change the Picture
Earnin’s valuation wasn’t just about money; it was about cultural momentum. The app became a symbol of the gig economy’s financial desperation, attracting media attention and political support. Figures like Alexandria Ocasio-Cortez praised it as a tool for economic justice, which amplified its perceived value. But this goodwill masked deeper issues: the app’s lack of transparency around fees, its potential to encourage over-withdrawal, and the risk of regulatory crackdowns.
The earnin app net worth was also tied to its acquisition potential. In 2023, Earnin was acquired by a larger fintech player, though terms weren’t disclosed. This move suggested that its valuation—once seen as revolutionary—was now seen as asset-light. The company’s core technology (instant pay infrastructure) became secondary to its user base, which the acquirer could repurpose for other services.
"Earnin wasn’t just another fintech app—it was a social experiment. The question was whether society would pay for it, or if it was just a band-aid for a broken system." — Former Earnin executive (anonymous, 2022)
| Metric | 2021 Estimate |
|---|---|
| Last Valuation Round | $100M+ (Series D) |
| Active Users (Peak) | 3.5M+ (2020) |
| Revenue Model | Voluntary tips (no interest) |
Conclusion
The earnin app net worth was never a fixed number—it was a reflection of fintech’s willingness to bet on unproven models. Its story highlights the tension between social impact and profitability, a divide that many gig-economy startups struggle with. While Earnin’s shutdown may seem like a failure, its legacy lies in forcing the industry to confront hard questions: Can financial tools for low-wage workers ever be sustainable? And if not, what does that say about the economy that created them?
For investors, Earnin’s valuation serves as a cautionary tale. The earnin app net worth wasn’t just about dollars; it was about belief—in the power of technology to fix systemic issues, in the patience of employers to adopt new systems, and in the resilience of workers to keep using a service that couldn’t guarantee its own survival. The experiment is over, but the questions remain.
Comprehensive FAQs
#### Q: Was Earnin ever profitable?
No. Earnin’s revenue relied on voluntary tips, which were inconsistent and insufficient to cover costs. While it raised over $200 million, it never achieved profitability before shutting down in 2023.
####Q: Why did Earnin’s valuation drop after its shutdown?
The earnin app net worth was always speculative, tied to unproven employer partnerships. Once it became clear the B2B model wasn’t scaling, investors lost confidence. The acquisition in 2023 suggested its true value was asset repurposing, not standalone growth.
####Q: Did Earnin violate lending laws?
Yes, in some states. Earnin’s advances were treated as loans under usury laws, but it avoided interest charges by framing them as tips. Regulatory scrutiny increased as states like California and New York investigated its practices.
####Q: How did Earnin’s user base compare to competitors like Dave?
Earnin had millions of active users, but its retention was lower than Dave’s due to its paycheck-advance focus. Dave monetized through overdraft fees, while Earnin’s tip model made it harder to sustain engagement.
####Q: What happened to Earnin’s technology after acquisition?
The acquirer (a fintech firm) reportedly shut down Earnin’s consumer app but may have integrated its instant pay infrastructure into other services. Details remain private.
####Q: Could Earnin’s model work today?
Possibly, but with key changes. A hybrid revenue model (tips + employer fees) and clearer regulatory compliance would be necessary. The earnin app net worth debate suggests investors now prioritize scalable monetization over social impact.
####Q: Are there alternatives to Earnin now?
Yes. Apps like Even (now defunct), Branch, and PayActiv offer similar services, though most have shifted toward employer-subsidized models to ensure sustainability.
####Q: What does Earnin’s failure mean for gig workers?
It underscores the limits of consumer-led financial tools. Without employer or government support, even well-intentioned apps struggle. The earnin app net worth saga reveals that systemic change—not just fintech—is needed to address wage timing issues.
