The Short Answers
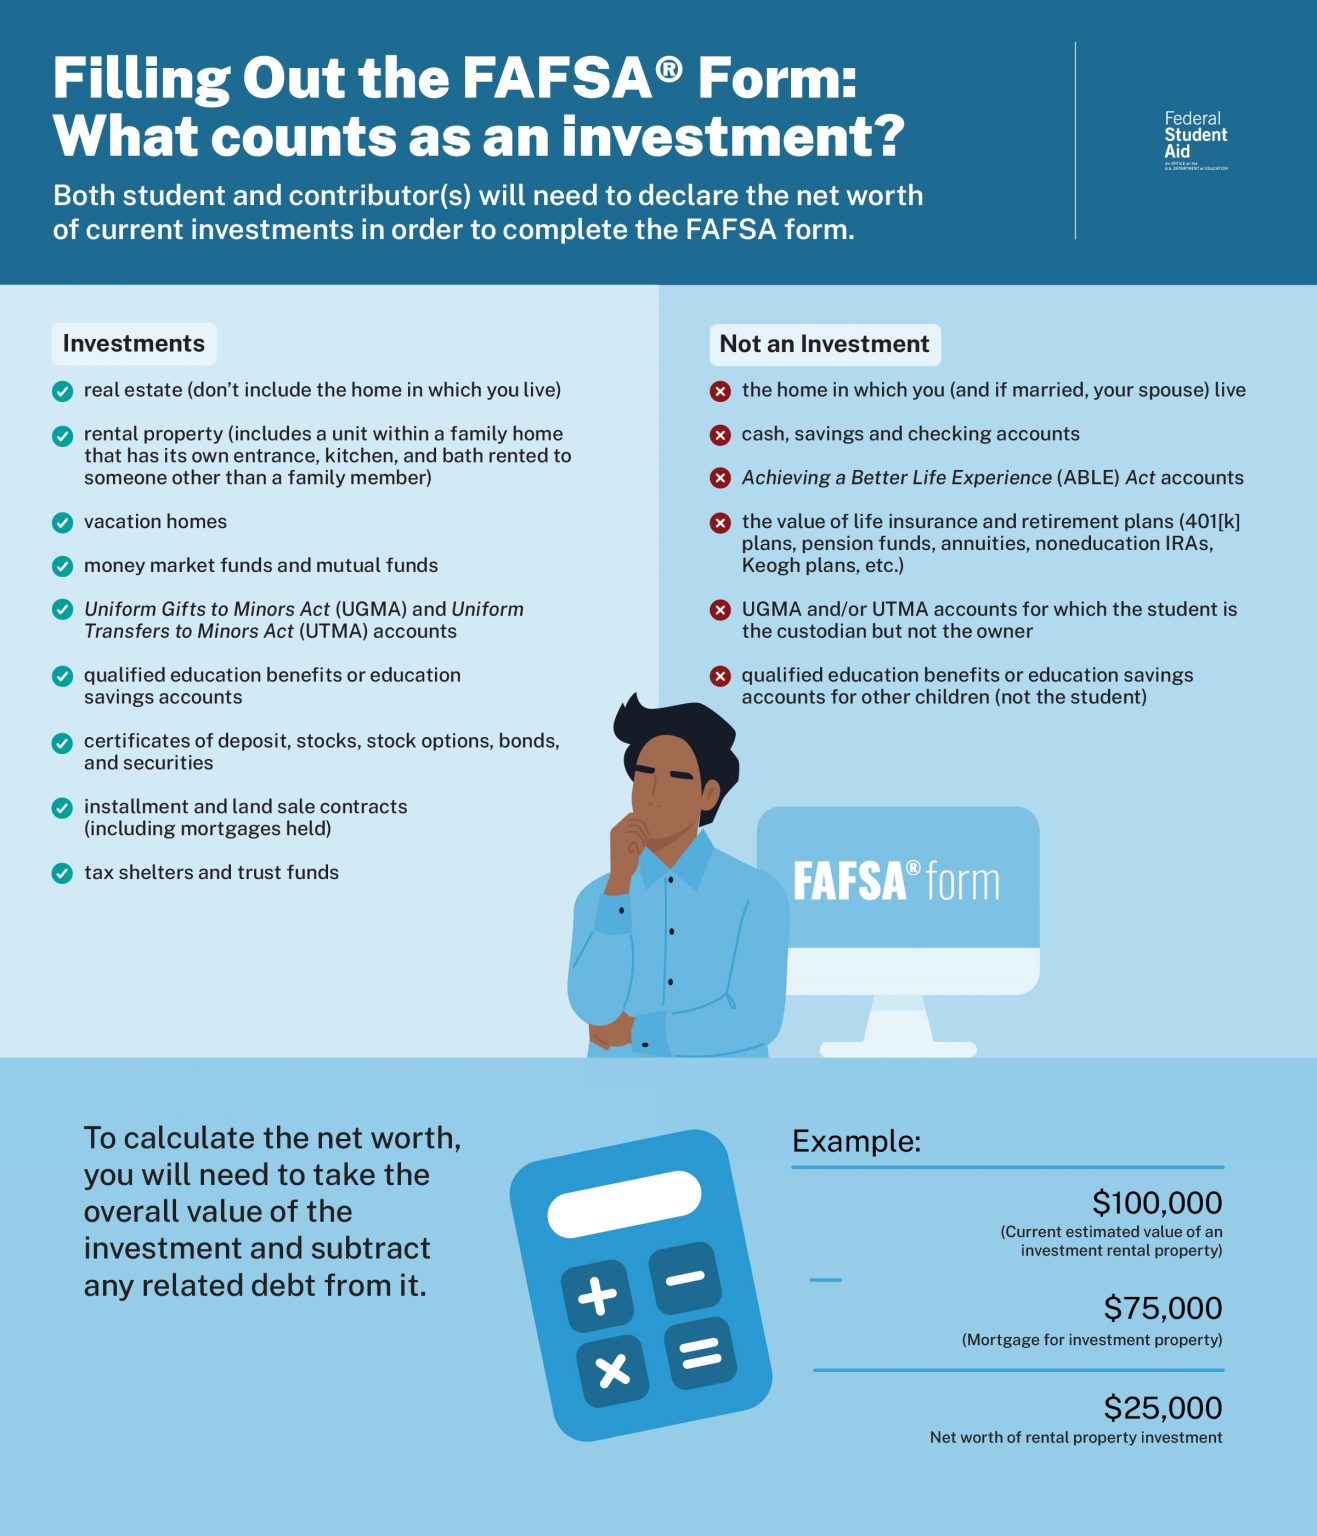
- FAFSA counts current net worth of investments as an asset, but only certain types (e.g., stocks, mutual funds) are assessed at 20% of their value.
- Retirement accounts like 401(k)s and IRAs are excluded from FAFSA calculations, but 529 plans are treated as parental assets—with major implications for dependent students.
- Business interests over 100 full-time equivalent employees or valued above $100,000 are reported differently, often reducing assessed value.
- Cryptocurrency and other digital assets must be reported at their current market value, not cost basis, and are fully assessed.
- FAFSA uses the prior-prior year’s income (PPY) for most filers, but asset values are based on the date of application—meaning a market dip in January could improve eligibility.
- Independent students (age 24+) report their own assets, while dependents use parental investment net worth, which can create strategic planning opportunities.
Deep Dive: The Full Picture
The FAFSA’s treatment of investments isn’t about punishing wealth—it’s about predicting a family’s ability to contribute to education costs over the next 18 months. But the system’s rigid formulas often overlook real-world financial behavior. For example, a family with a diversified portfolio might see their current net worth of investments swing wildly between filings due to market fluctuations, yet FAFSA’s static asset rules don’t account for liquidity or intent. The result? A family with $500,000 in stocks could be assessed as having $100,000 in "available" assets for college costs—even if those stocks are locked in a long-term strategy and untouchable. Where the confusion deepens is in the distinction between taxable and non-taxable accounts. A traditional brokerage account is fully assessed, but a Coverdell Education Savings Account (ESA) is treated as a parental asset—meaning only 5.64% of its value counts against the Expected Family Contribution (EFC). The discrepancy stems from FAFSA’s assumption that some assets are more easily converted to cash for education expenses. Yet this logic fails to consider that a 529 plan’s growth is earmarked for education, while a brokerage account might fund retirement or other priorities. The system’s one-size-fits-all approach forces families into binary choices: either hide assets to qualify for aid or accept higher out-of-pocket costs.The Context You Need
FAFSA’s asset rules were last overhauled in 2011, when Congress updated the formula to better reflect economic realities. The goal was to reduce complexity while maintaining fairness—but the trade-off was precision. Today, the formula relies on three key metrics: income (weighted more heavily for the prior-prior year), assets (valued at the time of application), and family size. The problem? Asset values don’t correlate with spending power. A family with $1 million in a non-liquid business might struggle to pay tuition, while another with $300,000 in easily accessible investments could cover costs without aid. The current net worth of investments is particularly volatile because it’s tied to market conditions. A family that filed FAFSA in October 2022—when the S&P 500 was near its peak—might have seen their assessed assets inflated by 20% compared to a January 2023 filing, post-February’s correction. This timing effect is why some financial aid advisors recommend filing FAFSA as late as possible in the eligibility window, though the risk of missing institutional deadlines must be weighed carefully.The Mechanics
Not all investments are created equal in FAFSA’s eyes. The formula divides assets into two broad categories: parental and student-owned. For dependent students, only parental assets matter—unless the student is 24 or older, in which case their own investment net worth is assessed. Here’s how key account types are treated: - Taxable brokerage accounts, stocks, bonds, mutual funds: Assessed at 20% of their value. This means only a fraction of their current net worth of investments counts toward the EFC, reflecting FAFSA’s assumption that not all assets are liquid. - Retirement accounts (401(k), IRA, Roth IRA): Excluded entirely from asset calculations. The logic? These funds are restricted for retirement, not education. - 529 plans and Coverdell ESAs: Treated as parental assets if owned by parents or guardians. Only 5.64% of their value is assessed, but distributions are reported as income on the FAFSA the following year. - Real estate (primary home): Excluded if it’s the family’s principal residence. Rental properties or vacation homes are assessed at their full value. - Business interests: Reported at their net value (assets minus liabilities). If the business has over 100 full-time employees or is valued above $100,000, only a portion of its value is assessed. - Cryptocurrency and digital assets: Fully assessed at current market value, not cost basis. This is a relatively new wrinkle, as FAFSA only began explicitly requiring crypto reporting in 2022. The assessment rate for most assets is 20%, but this doesn’t mean families can simply move money into retirement accounts to reduce eligibility. FAFSA’s verification process can flag suspicious contributions or withdrawals, especially if they coincide with the application period.Details That Change the Picture
The biggest misconception about the current net worth of investments on FAFSA is that it’s a static snapshot. In reality, it’s a moving target influenced by market conditions, account types, and even the order in which questions are answered. For instance, a family with a $200,000 529 plan might see their EFC drop by $11,280 (5.64% of $200,000) compared to holding the same amount in a brokerage account, which would only add $40,000 to their assessed assets. This isn’t just about numbers—it’s about asset location strategy, where the right account structure can mean the difference between qualifying for Pell Grants or being priced out of public universities. Another critical factor is the timing of asset sales or transfers. FAFSA’s asset rules assume families can liquidate investments to pay for college, but this ignores real-world constraints. Selling stocks at a loss to reduce investment net worth might trigger capital gains taxes or violate wash-sale rules. Similarly, transferring assets to a dependent student’s name (to take advantage of lower assessment rates) can backfire if the student is under 24—their assets would then be assessed at a higher rate. The IRS and FAFSA verification teams are increasingly scrutinizing such moves, particularly when they occur in the 60 days before or after filing."The FAFSA formula is designed to be blunt instrument—it’s not about fairness, it’s about simplicity. Families who understand the nuances can optimize, but the system is set up to penalize those who don’t. The real tragedy is that the rules often work against the very people they’re supposed to help." —Mark Kantrowitz, publisher of SavingForCollege.com
| Asset Type | FAFSA Assessment Rate |
|---|---|
| Taxable brokerage accounts, stocks, bonds | 20% of value |
| Retirement accounts (401(k), IRA, Roth IRA) | 0% (excluded) |
| 529 plans, Coverdell ESAs (parent-owned) | 5.64% of value |
| Primary residence | 0% (excluded) |
| Cryptocurrency, digital assets | 100% of current market value |
Conclusion
The current net worth of investments isn’t just a line item on the FAFSA—it’s a reflection of how the financial aid system balances accessibility with accountability. The rules favor families who can navigate asset reporting strategies, but the penalties for missteps can be severe. The key is to treat FAFSA not as a static form but as a dynamic interaction between market conditions, account structures, and timing. For example, a family with a volatile investment portfolio might benefit from filing FAFSA earlier in the year when asset values are lower, or restructuring holdings to maximize excluded accounts like retirement funds. Ultimately, the system’s rigidity forces families into a choice: either accept that their investment net worth will reduce aid eligibility or engage in complex (and sometimes risky) financial maneuvers to optimize their position. The lack of transparency around how asset values are assessed—particularly for non-traditional investments like crypto or private businesses—only adds to the frustration. Yet for those who take the time to understand the rules, the FAFSA can still be a powerful tool, not just a barrier.Comprehensive FAQs
Q: Does FAFSA count my parent’s 401(k) if they’re helping me pay for college?
A: No. Retirement accounts like 401(k)s and IRAs are excluded from FAFSA asset calculations entirely, regardless of who owns them. However, if your parents take withdrawals from these accounts to contribute to your education, those distributions will count as untaxed income on the FAFSA the following year.
Q: I have a 529 plan with $150,000. How much will it affect my EFC?
A: Only 5.64% of the 529 plan’s value is assessed for the EFC. For $150,000, that’s roughly $8,460 added to your assessed assets. However, distributions from the 529 plan (used for qualified education expenses) are reported as income on the FAFSA the year after withdrawal, which could further impact eligibility.
Q: My child is 23 and working full-time. Do I still have to report my investments?
A: If your child is considered an independent student (age 24 or older, married, or otherwise qualifying), they must report their own current net worth of investments—not yours. However, if they’re still a dependent (e.g., under 24 and unmarried), your assets (including investments) will be assessed at the parental rate.
Q: I sold some stocks at a loss before filing FAFSA. Will this help my aid eligibility?
A: Not directly. FAFSA only cares about the current market value of your investments as of the date of application, not your cost basis or capital gains/losses. However, selling at a loss could trigger tax implications or draw attention during verification if the timing seems suspicious (e.g., large sales right before filing).
Q: How are rental properties treated on FAFSA compared to my primary home?
A: Your primary residence is excluded from FAFSA asset calculations, but rental properties or vacation homes are assessed at their full value. This means if you own a rental property worth $300,000, the entire amount could be counted toward your EFC—unlike your primary home, which doesn’t factor in at all.
Q: My spouse and I have separate investment accounts. Do we combine them on FAFSA?
A: Yes. FAFSA treats all parental assets as a single pool, regardless of whose name is on the account. This includes brokerage accounts, 529 plans, and other investments. The total current net worth of investments is summed and assessed according to the standard rates.
Q: What happens if I underreport my investments on FAFSA?
A: Underreporting assets is a fraudulent misrepresentation under federal law and can result in denied aid, repayment of all received funds, and potential criminal charges. FAFSA’s verification process—especially for high-asset families—often includes random selections for asset documentation. If discrepancies are found, the family may face penalties or be barred from future aid.
Q: Can I use a trust to reduce the impact of my investments on FAFSA?
A: It depends on the type of trust. Irrevocable trusts (where you relinquish control) may exclude assets from FAFSA calculations, but the rules are complex and often require professional guidance. Revocable trusts (where you retain control) are typically treated the same as individual assets. Additionally, trusts created solely to manipulate FAFSA eligibility can be challenged by verification teams or the IRS.
Q: Does FAFSA consider my spouse’s student loans or my own?
A: No. Student loans (including private loans) are not counted as assets on the FAFSA, regardless of whether they’re in your name or your spouse’s. However, the loan payments themselves are considered when calculating your discretionary income, which can indirectly affect aid eligibility.
