
The Short Answers
- Cash App’s cash loading program lets users deposit cash at select retailers (e.g., Walmart, CVS) instantly, with funds available in minutes.
- Fees range from 0% to 3% per transaction, depending on the retailer and account type, with a $250 daily limit for unverified users.
- No bank account is required, but verification (via ID or SSN) unlocks higher limits and lower fees for some partners.
- Disputes or failed loads are rare but can occur due to retailer errors or app bugs; support resolution times vary.
- The program is most useful for unbanked users, gig workers, or those needing quick access to digital funds without a card.
Deep Dive: The Full Picture
Cash App’s cash loading program operates at the intersection of fintech and physical commerce, blending digital convenience with analog cash handling. The feature was launched in 2017 as a pilot with a handful of stores before scaling aggressively in 2020, coinciding with pandemic-driven cash shortages. Today, it processes millions of transactions annually, though exact figures remain proprietary. The program’s design reflects Cash App’s broader strategy: lowering barriers to financial inclusion while monetizing through transaction fees and upselling other services. For users, the appeal is clear—no waiting for checks to clear, no need to visit an ATM, and no reliance on a bank. But the trade-off is visibility: fees and limits are buried in the app’s settings, not its marketing. Under the hood, the cash loading program relies on a network of retail partners who act as cash deposit agents. When a user visits a participating location, they scan a QR code or provide a reference number to initiate a deposit. The retailer then verifies the amount, processes the cash, and submits it to Cash App’s backend. Funds typically arrive in the user’s account within minutes, though delays can occur during peak hours or if the retailer’s system is slow. The program’s success hinges on this partnership model—retailers earn a cut per transaction, while Cash App avoids the overhead of physical branches. However, the arrangement isn’t without friction: some stores report cash handling inefficiencies, and users occasionally encounter long lines or staff unfamiliar with the process.The Context You Need
The cash loading program’s growth mirrors broader trends in financial services, where instant access and frictionless transactions are prioritized over traditional banking hurdles. According to a 2023 Pew Research study, 60% of unbanked Americans cite high fees or minimum balance requirements as reasons for avoiding banks. Cash App’s program taps into this demand by offering a no-frills alternative. The feature also aligns with Block’s (formerly Square) expansion into consumer finance, complementing its Square Reader for small businesses and Afterpay for buy-now-pay-later services. For Cash App, the cash loading program is less about profit margins and more about locking in users—once someone starts depositing cash, they’re more likely to use the app for payments, investments, or even Bitcoin purchases. Yet the program’s reach is limited by its reliance on retail partners. Not all stores participate, and those that do may have varying fee structures or deposit limits. Cash App’s app interface doesn’t always clarify these differences, leaving users to discover them through trial and error. For example, a deposit at Walmart might incur a 1.5% fee, while CVS could charge 3%—a discrepancy that’s only visible after the transaction. This opacity has led to frustration among some users, particularly those who assume the program is uniformly free or low-cost. Additionally, the app’s verification process can create barriers: while unverified users can load cash, they face lower daily limits ($250 vs. $1,000 for verified accounts), which may deter heavier cash users.The Mechanics
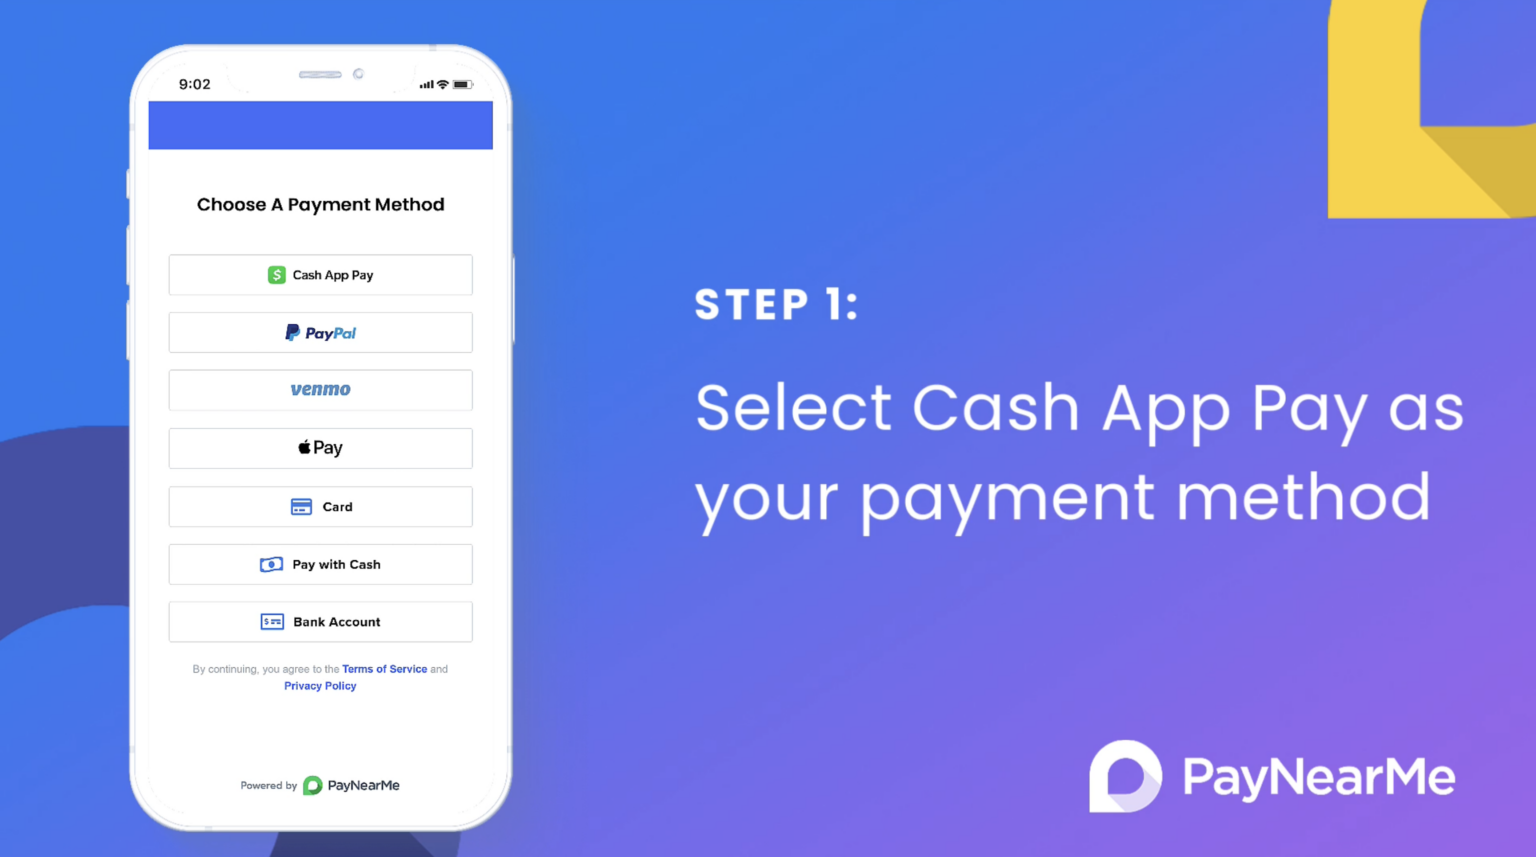
The technical workflow behind Cash App’s cash loading program is deceptively simple. When a user initiates a deposit, the app generates a unique reference code or QR link tied to their account. At the retail partner’s end, an employee scans this code (or manually enters the number) along with the cash amount. The retailer then submits the transaction to Cash App’s payment processor, which deducts its fee (if applicable) and credits the user’s balance. The entire process is designed to be reversible for a short window—if a user disputes a deposit, Cash App can refund the amount and return the cash to the retailer for reconciliation. However, this system is vulnerable to errors: a misread QR code, a typo in the reference number, or a retailer’s cash register malfunction can all derail the transaction. Behind the scenes, Cash App’s infrastructure must handle high volumes of near-instant transactions while mitigating fraud. The app employs machine learning to flag suspicious activity, such as unusually large deposits from a single location or rapid-fire transactions from the same device. Retailers are also trained to verify IDs for high-value deposits, though enforcement varies by store. The program’s speed is its biggest selling point—unlike bank deposits, which can take days to clear, Cash App’s cash loading program delivers funds in minutes. But this velocity comes at a cost: the app’s servers must process thousands of transactions per hour, requiring robust backend systems to prevent downtime. During outages or maintenance, users may encounter delays, though Cash App’s support team often resolves issues within hours.Details That Change the Picture
Cash App’s cash loading program isn’t just about moving money—it’s about reshaping user behavior. Studies show that people who frequently load cash are more likely to engage with other Cash App features, such as sending payments or investing in stocks. This "stickiness" is intentional: the program serves as a gateway to the app’s broader ecosystem. However, the feature’s impact isn’t uniform. In urban areas with high cash usage, the program thrives; in suburban or rural regions, adoption lags due to fewer participating retailers. Additionally, the program’s reliance on physical locations creates a digital divide—users without reliable internet or transportation may still struggle to access it. Another layer of complexity lies in the program’s fee structure. While Cash App itself doesn’t charge a flat fee for deposits, retail partners often do, and these costs aren’t always transparent. For example, a $100 deposit at a store charging a 3% fee would deduct $3 before crediting the user’s account. Over time, these fees can add up, particularly for gig workers or small business owners who frequently load cash. Cash App’s app provides a fee breakdown post-transaction, but the lack of upfront disclosure has led to criticism. Some users report being surprised by unexpected deductions, especially when switching between retailers with different fee tiers."The cash loading program works best for people who already use Cash App for payments. If you’re only depositing cash and not sending money elsewhere, the fees start to feel like a tax on convenience." — Financial tech analyst, speaking on the program’s cost-benefit trade-offs
| Scenario | Key Consideration |
|---|---|
| Unbanked users | No ID required for small deposits, but daily limits cap usage. |
| Gig workers | Fees can eat into earnings; verify account to access lower rates. | Retailers | Earn per transaction but face cash handling and training costs. |
| High-volume users | Verification unlocks higher limits, but frequent loads may trigger fraud alerts. |
| Cash App’s business model | Program drives engagement but relies on retail partnerships for scalability. |
Conclusion
Cash App’s cash loading program is a double-edged tool: it democratizes access to digital finance for those excluded by traditional systems, but its fees and limitations can undermine its promise. For the unbanked or underbanked, the program offers a lifeline—no credit checks, no minimum balances, and no need to wait for a check to clear. Yet for others, the convenience comes at a cost, particularly when fees or retailer errors disrupt the process. The program’s success hinges on its ability to balance accessibility with profitability, a tightrope walk that Block has navigated with mixed results. As competition from Venmo, PayPal, and even traditional banks intensifies, Cash App’s cash loading program remains a critical differentiator—but one that must evolve to stay ahead. The future of the program may lie in deeper integration with Cash App’s other services. If Block can tie cash loading to higher-margin offerings—such as Bitcoin purchases, stock trading, or tax filing tools—it could turn a low-margin feature into a growth driver. For now, the program’s strength lies in its simplicity: a quick way to move cash into the digital world. But as users grow more sophisticated, transparency and lower costs will become non-negotiable. Whether Cash App can meet these demands without sacrificing its core appeal remains the million-dollar question.Comprehensive FAQs
Q: Can I load cash at any store?
A: No. Cash App’s cash loading program only works at participating retailers, which include major chains like Walmart, CVS, 7-Eleven, and some local grocery stores. The full list is available in the app under "Cash Out" or "Deposit Cash," but not all locations support it. Some stores may also have temporary restrictions due to operational issues.
Q: Are there any fees for loading cash?
A: Fees depend on the retailer. Cash App itself doesn’t charge a flat fee, but the store may take a cut (typically 1.5%–3%). For example, depositing $200 at a 2% fee location would net you $196. Unverified users may face additional limits or higher fees at some partners. Always check the fee breakdown after completing a transaction.
Q: How long does it take for loaded cash to appear in my account?
A: Funds are usually available within minutes, but delays can occur during peak hours (e.g., weekends or holidays) or if the retailer’s system is slow. In rare cases, transactions may take up to an hour. If funds don’t appear, contact Cash App support or the retailer for assistance.
Q: What’s the maximum I can deposit in a day?
A: Unverified users are limited to $250 per day, while verified users (with ID or SSN) can deposit up to $1,000 daily. These limits apply per account, not per transaction. Exceeding them may require additional verification or result in temporary holds.
Q: Can I dispute a failed or incorrect cash load?
A: Yes, but the process depends on the issue. For retailer errors (e.g., wrong amount entered), contact the store directly—they may issue a correction. For app-side issues (e.g., funds not appearing), open a dispute in Cash App’s support center within 30 days. Refunds for disputed loads are processed manually and may take several business days.
Q: Do I need a bank account to use the cash loading program?
A: No. Cash App’s cash loading program is designed for users without bank accounts. You only need a valid phone number to create an account. However, linking a bank account later allows for higher limits and additional features like direct deposits.
Q: What happens if the retailer makes a mistake with my deposit?
A: If a retailer enters the wrong amount or fails to process your cash, you’ll need to resolve it directly with them. Cash App’s support can assist if the store is unresponsive, but the retailer typically handles corrections. Keep your receipt or reference number as proof of the transaction.
Q: Are there any security risks with loading cash?
A: The process is secure, but risks exist at the retailer’s end. For example, if an employee enters the wrong reference number, your cash may go to another user’s account. To mitigate this, double-check the QR code or reference number before handing over cash. Cash App also employs fraud detection to monitor unusual activity.
Q: Can businesses use the cash loading program for payments?
A: Not directly. The program is for personal use only—businesses must use Cash App’s commercial features (like Cash App for Business) for payments. However, sole proprietors or gig workers can use the cash loading program to deposit earnings before transferring them to a business account.
Q: Why does Cash App ask for my ID sometimes?
A: ID verification is required for higher deposit limits ($1,000/day vs. $250) and may be prompted if Cash App detects suspicious activity (e.g., rapid-fire small deposits). Verification also helps prevent fraud and may be necessary for certain retail partners. You can verify your account in the app’s settings under "Personal" or "Security."
