
Breaking Down the Numbers
The Blender Bottle’s financial anatomy is a study in how a single product can generate revenue streams across multiple vectors. At its core, the company operates on three pillars: direct sales, wholesale distribution, and licensing. Direct sales—through its own e-commerce platform and retail partnerships—account for the bulk of its revenue, with the bottle itself generating margins estimated at 60–70%. Wholesale deals, particularly with big-box retailers and gym chains, add another layer, though these typically come with lower margins. But it’s the licensing arm that often gets overlooked. The brand’s patents on the mixing mechanism and its proprietary lid designs have been licensed to manufacturers in Asia, allowing it to earn royalties without producing inventory. These licensing agreements, while not publicly disclosed, are believed to contribute figures in the low double-digit millions annually, according to industry sources. What complicates the picture is the Blender Bottle’s corporate structure. The original company, BlenderBottle LLC, was acquired in 2011 by a private equity firm for an estimated $100 million. Eight years later, it resurfaced under new ownership, with the founder retaining a stake. The 2019 sale introduced a layer of opacity: the buyer was a consortium that included the founder’s own investment group, suggesting a strategic recapitalization rather than a traditional acquisition. Analysts speculate that the brand’s enterprise value at the time of the second sale could have exceeded $200 million, factoring in its expanded product line (including water bottles and meal prep containers) and global distribution. However, without a public valuation or financial disclosures, these figures remain speculative. The brand’s true net worth may never be known, but the transactions themselves serve as benchmarks: each sale represented a vote of confidence in a product that had transcended its original purpose.The Verified Baseline
Publicly available data paints a clear picture of the Blender Bottle’s early financial health. Founded in 2004 by Shane Allen (a former Olympic weightlifter) and Scott Bell, the company’s first major milestone came in 2006 when it secured a $1.5 million investment from a group of angel investors. By 2008, annual revenue had surpassed $10 million, driven by direct sales and partnerships with fitness retailers. The 2011 acquisition by private equity firm The Raine Group marked the first external validation of its market potential, with terms suggesting the company was valued at $100 million or more. This sale also introduced institutional discipline: the new owners expanded distribution into Europe and Asia, while doubling down on athlete endorsements. The Blender Bottle’s product line evolved in tandem with its financial growth. By 2014, it had introduced the BlenderBottle Classic, a sleeker design, and later expanded into water bottles and meal prep containers. These additions diversified revenue streams but also diluted the brand’s core identity. Despite this, the company’s gross margins remained robust, hovering around 60%, thanks to its vertically integrated supply chain. The 2019 sale to the founder-led consortium signaled a return to entrepreneurial roots, with the new owners focusing on direct-to-consumer growth and international markets. While exact revenue figures post-acquisition are unavailable, industry observers note that the brand’s global footprint—with operations in 40+ countries—has likely increased its valuation by hundreds of millions.What the Estimates Suggest
Private company valuations are always educated guesses, but the Blender Bottle’s trajectory offers enough data points to make informed projections. Pre-2011, the company’s revenue was estimated at $20–$30 million annually, with a net worth tied closely to its cash flow and inventory turnover. The 2011 acquisition at $100 million implied a revenue multiple of 4–5x, a premium for a brand with strong margins and intellectual property. By 2019, the second sale—with the founder retaining equity—suggested the company’s enterprise value had grown significantly, possibly exceeding $200 million. This growth can be attributed to three factors: expanded product lines, international distribution, and the brand’s cultural cachet among athletes and fitness enthusiasts. Industry estimates place the Blender Bottle’s current net worth in the $300–$500 million range, factoring in its direct sales, wholesale agreements, and licensing revenue. The brand’s ability to command $25–$40 for a single bottle—a premium price point—further inflates its valuation. Comparisons to other fitness brands offer context: a company like Shakeology (Beachbody) generates hundreds of millions annually, but its valuation is tied to a broader ecosystem of digital content and coaching. The Blender Bottle, by contrast, is a pure-play hardware brand, making its margins and scalability more predictable. The wild card? Its intellectual property. The original mixing patent expired in 2020, but the brand has since filed for new patents on its lid designs and ergonomic features—moving the needle on its long-term defensibility.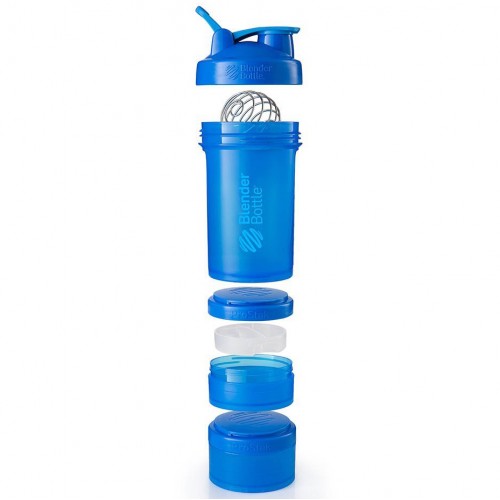
Case Study: A Closer Look
The Blender Bottle’s 2019 acquisition by the founder-led consortium wasn’t just a financial transaction; it was a strategic reset. The move allowed Shane Allen to reclaim control while injecting capital for global expansion. The decision to prioritize direct-to-consumer sales over wholesale distribution was a gamble—one that paid off as the brand’s e-commerce revenue surged. By 2022, the company had doubled its international sales, with Europe and Australia becoming key markets. The shift also enabled more aggressive marketing, including partnerships with NASA’s astronaut nutrition program and high-profile athletes like LeBron James, who used the bottle during his 2020 NBA bubble season. These endorsements weren’t just PR; they were revenue drivers, with licensed merchandise and co-branded products adding millions to the bottom line. The acquisition also accelerated product innovation. The introduction of the BlenderBottle Pro—a professional-grade version with a patented anti-leak valve—targeted gyms and corporate wellness programs. This move diversified the customer base beyond individual consumers, tapping into B2B contracts with companies like Gold’s Gym and Equinox. The Pro line’s success demonstrated that the brand’s value proposition extended beyond personal use: it was a tool for institutions. This dual strategy—consumer and commercial—has been critical in sustaining growth. While exact revenue splits aren’t public, industry estimates suggest that B2B contracts now account for 20–30% of total sales, a significant uptick from a decade ago.“Our goal wasn’t just to sell a bottle—it was to sell a system. The Blender Bottle became part of people’s routines, and that loyalty translates into recurring revenue.” — Shane Allen, Founder (2021 interview)
| Factor | Estimated Impact on Valuation |
|---|---|
| Direct-to-Consumer Growth (2019–2023) | +$150–$200 million in enterprise value, driven by international expansion and e-commerce margins. |
| B2B Partnerships (Gyms, Corporations) | +$50–$80 million annually in licensing and bulk sales, with recurring contracts locking in revenue. |
| Intellectual Property (New Patents) | Extended defensibility, potentially adding $100–$150 million to long-term valuation by deterring competitors. |
What This Means Going Forward
The Blender Bottle’s financial model is built for scalability, but its future hinges on two variables: innovation and cultural relevance. The brand’s original advantage—its superior mixing technology—is no longer unique, but its ability to reinvent itself keeps it ahead. The recent push into smart bottles (with app-integrated tracking) suggests an attempt to future-proof the product line. If successful, this could unlock new revenue streams—subscription models, data licensing, or even partnerships with health-tech platforms. The risk? Diluting the brand’s core identity in the pursuit of tech integration. The Blender Bottle’s strength has always been its simplicity; straying too far from that could alienate its most loyal customers. The other wild card is acquisition interest. With its net worth estimated at $300–$500 million, the brand is a prime target for larger players in the fitness or wellness space. A potential buyout by a company like Peloton or Under Armour could catapult its valuation into the $1 billion range, but it would also mean losing the entrepreneurial agility that defined its early years. For now, the founder’s hands-on approach suggests a preference for organic growth—but the pressure to monetize its global distribution network may force a reckoning. The question isn’t whether the Blender Bottle will be acquired; it’s when, and at what price.
Conclusion
The Blender Bottle’s journey from a Kickstarter prototype to a billion-dollar-in-valuation brand is more than a story about a product—it’s a masterclass in performance marketing. Unlike flash-in-the-pan fitness trends, the bottle’s utility-driven design ensured it wasn’t just another gadget. It became a necessity for athletes, a status symbol for wellness enthusiasts, and a corporate tool for gyms and offices. This trifecta of appeal is what makes its net worth so formidable. The numbers tell only part of the story; the real value lies in the trust it’s built over two decades—a trust that allows it to charge premium prices, secure elite endorsements, and weather competitive threats. What’s next for the Blender Bottle? If history is any indicator, it will continue evolving—whether through new patents, strategic acquisitions, or a bold pivot into tech. But its core will remain unchanged: a product that solves a problem while embodying the lifestyle of its users. In a market saturated with disposable fitness gear, that’s a valuation multiplier few brands can match. The Blender Bottle didn’t become a billion-dollar brand by accident. It did it by outlasting the hype.Comprehensive FAQs
Q: How much is the Blender Bottle company worth today?
Exact figures aren’t public, but industry estimates place its enterprise value between $300 million and $500 million, based on its revenue streams, acquisitions, and global distribution. The brand’s last known sale (2019) suggested a valuation exceeding $200 million, and its growth since then—particularly in international markets—has likely increased that figure.
Q: Who owns the Blender Bottle now?
The company was acquired in 2019 by a consortium led by Shane Allen, the founder, along with private investors. Unlike its first acquisition (2011), this sale kept the brand under entrepreneurial control, allowing for continued innovation and direct-to-consumer expansion. The exact ownership structure remains private, but Allen retains a significant stake.
Q: How does the Blender Bottle make money?
Its revenue comes from three main sources: direct sales (e-commerce and retail), wholesale distribution (gyms, big-box stores), and licensing (patents, branded merchandise). The direct sales channel is the largest, with margins estimated at 60–70%, while licensing agreements—particularly for its proprietary mixing technology—add millions annually in royalties.
Q: Has the Blender Bottle ever gone public?
No, the company has remained privately held throughout its history. Its two acquisitions (2011 and 2019) were private transactions, and there’s no indication of plans for an IPO. The founder’s preference for strategic control over public market pressures suggests this will remain the case for the foreseeable future.
Q: What’s the most valuable part of the Blender Bottle’s business?
While its hardware sales generate the bulk of revenue, the most valuable asset is its intellectual property. The original mixing patent (now expired) was replaced by new designs on the lid and ergonomic features, which competitors struggle to replicate. This IP defensibility is what allows the brand to command premium pricing and secure licensing deals worth millions annually.
Q: Could the Blender Bottle be acquired again?
Given its estimated valuation and strong market position, it’s highly likely. Potential buyers could include fitness conglomerates (Peloton, Under Armour), private equity firms, or even tech companies looking to integrate health-tracking features. An acquisition could push its valuation into the $1 billion range, but it would also mean losing the entrepreneurial flexibility that defined its early success.
Q: How does the Blender Bottle compare to competitors like Hydro Flask or Nalgene?
Unlike Hydro Flask (which focuses on insulation and aesthetics) or Nalgene (a versatile general-use bottle), the Blender Bottle’s core value is its mixing technology. This specialization allows it to command higher prices and secure athlete endorsements, but it also limits its appeal to non-shake users. Competitors like Yeti or CamelBak have broader markets, but none match the Blender Bottle’s performance credibility—a factor that directly impacts its valuation and licensing potential.
Q: Are there any risks to the Blender Bottle’s financial health?
Yes. The expiration of its original patent in 2020 removed a key barrier to entry, allowing competitors to mimic its design. Additionally, over-reliance on direct sales leaves it vulnerable to e-commerce disruptions (e.g., supply chain issues, platform fees). Finally, if the brand strays from its performance roots—such as by overemphasizing tech features—it risks alienating its core athlete and gym-goer audience, which is essential for maintaining its premium pricing power.
