The Short Answers
- The average Midwest farmer net worth is estimated at $1.8 million, but this varies wildly by region, crop, and generational stage.
- Land makes up 60-80% of total farm wealth, but its value is volatile and often leveraged.
- Debt levels have surged since 2020, with younger farmers carrying 3-5x more debt relative to assets than older operators.
- Diversification (e.g., renewable energy, agri-tourism) can boost net worth but requires upfront capital most farmers lack.
- Succession planning is critical—60% of Midwest farms will change hands in the next decade, but only 30% have formal transfer plans.
- Climate risks (drought, flooding) and trade policies (tariffs, export bans) directly erode average Midwest farmer net worth by 10-20% in bad years.

Deep Dive: The Full Picture
The average Midwest farmer net worth is a composite of three interlocking forces: asset appreciation, debt structure, and operational efficiency. Take Iowa, the nation’s top corn producer. A typical 1,500-acre row-crop farm there might show a net worth of $2.5 million on paper—$2 million in land, $300,000 in equipment, and $200,000 in cash reserves. But peel back the layers: that land is mortgaged at $1.5 million, the equipment is financed at $150,000, and the "cash reserves" include a $100,000 line of credit. The real equity? Maybe $500,000. This isn’t unique to Iowa. In Nebraska, where cattle ranching dominates, a 5,000-acre operation might list a net worth of $4 million, but feed costs and veterinary debt can swallow 40% of gross margins in a single year.
What’s often missing from discussions about Midwest farmer net worth is the role of opportunity cost. A farmer who holds onto land during a downturn isn’t just preserving equity—they’re betting that future prices will recover. But that bet requires liquidity to cover living expenses, taxes, and unexpected repairs. The USDA’s 2022 Farm Economics Report noted that farmers aged 55-64—the group most likely to hold land—have seen their net worth stagnate since 2018, while younger farmers (under 35) have lost ground due to higher input costs and lower commodity prices. The average Midwest farmer net worth isn’t just about what’s owned; it’s about what’s accessible without triggering a fire sale.
#### The Context You Need
The Midwest’s agricultural economy runs on two pillars: commodity production and land ownership. Corn, soybeans, and wheat are the cash crops that define average Midwest farmer net worth, but their prices are globally traded and subject to geopolitical whims. When China imposes tariffs on U.S. soybeans, Midwest farmers don’t just lose revenue—they lose equity. Land, meanwhile, operates on a different cycle. In the 1980s, farmland was a speculative asset; today, it’s a hedge against inflation. But that hedge only works if the farmer can hold onto it. During the 2008 financial crisis, land values in some regions dropped by 30%, forcing distress sales that wiped out decades of accumulated wealth. The other context is generational transfer. The USDA estimates that only 1 in 10 family farms will remain family-owned by 2030 without a formal succession plan. This isn’t just about wills and trusts—it’s about liquidity. Heirs often lack the capital to buy out siblings or cover estate taxes, leading to forced sales that fragment land and dilute Midwest farmer net worth. In North Dakota, where oil revenues have inflated local land prices, some farmers are sitting on paper gains of 200% over the past decade—but those gains are meaningless if the next generation can’t afford to take over. ####The Mechanics
Net worth in farming isn’t calculated like a corporate balance sheet. It’s a living ledger, where assets and liabilities shift with seasons. Take a diversified farm in Illinois: 800 acres of corn, 400 acres of soybeans, a 50-cow dairy herd, and a small-scale organic vegetable operation. The corn and soybeans might contribute $1.2 million to gross revenue, but input costs (seed, fertilizer, fuel) eat up $800,000. The dairy herd adds $300,000 but requires $200,000 in feed and labor. The organic side brings in $100,000 with minimal overhead. After debt service ($400,000) and living expenses ($150,000), the farm breaks even—or loses money. Yet the land alone is worth $3 million. That’s the paradox of average Midwest farmer net worth: the business may be struggling, but the collateral is valuable. The mechanics of debt are where many farmers get trapped. Variable-rate loans on land or equipment can become unmanageable when interest rates rise. In 2022, the average interest rate on farm loans jumped to 6.5%, up from 4.2% in 2019. For a farmer with $2 million in debt, that’s an extra $30,000 annually. Couple that with a 20% drop in corn prices (as seen in 2023), and the margin for error disappears. The average Midwest farmer net worth isn’t just about what’s on the balance sheet; it’s about the cash flow cushion that lets a farmer ride out a bad year. Without it, even a high net worth can turn toxic.Details That Change the Picture
Not all Midwest farms are created equal. A corn-and-soybean operation in Indiana will have a different average Midwest farmer net worth profile than a dairy farm in Wisconsin or a beef ranch in Kansas. The crop mix, scale, and diversification strategies create stark divides. For example, farms that integrate renewable energy—like installing solar panels on unused land—can see their net worth grow by 15-20% annually, but the upfront costs are prohibitive for most. Meanwhile, farms that rely solely on commodity crops are at the mercy of global markets. A single trade dispute can erase years of built-up equity.
Another critical factor is farm size. Small farms (under 500 acres) often have lower net worth but higher debt-to-asset ratios because they lack economies of scale. Large operations (over 2,000 acres) may have higher net worth but face different risks, like labor shortages and regulatory burdens. The USDA’s 2023 report highlighted that farms with annual revenues over $1 million account for just 7% of all farms but hold 42% of total farm assets. That concentration of wealth isn’t just about size—it’s about access to capital. A young farmer starting out with $200,000 in savings will struggle to compete with an established operator who can secure low-interest loans based on decades of credit history.
"You can have a $5 million farm on paper, but if you’re paying $300,000 a year in interest and your crops are worth $2 million, you’re not rich—you’re leveraged to the gills." — Mark Draper, agricultural economist at Purdue University
| Factor | Impact on Net Worth |
|---|---|
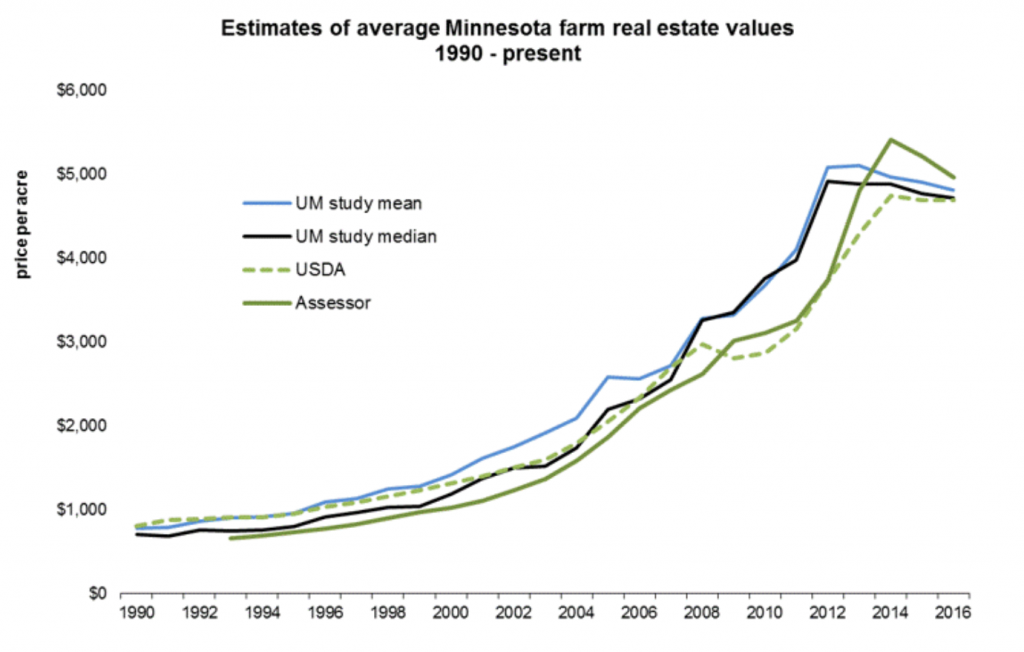
| Land Value Volatility | Can swing net worth by ±30% in a 5-year cycle (e.g., 2013 peak vs. 2019 trough). |
| Debt Levels | Young farmers carry 3-5x more debt relative to assets than farmers over 65. |
| Commodity Prices | A 20% drop in corn prices reduces average Midwest farmer net worth by ~$500,000 for a 2,000-acre operation. |
| Diversification | Farms with multiple revenue streams (e.g., crops + livestock + agri-tourism) see 10-15% higher net worth than monoculture operations. |
| Succession Planning | Farms with formal transfer plans have 40% higher net worth at retirement due to reduced fragmentation. |
Conclusion
The average Midwest farmer net worth is less about individual success and more about systemic resilience. It’s the product of inherited land, deferred debt, and the ability to endure when markets turn. But the numbers tell a story of uneven progress: while some farmers thrive, others are trapped in a cycle of high debt and low margins. The biggest threat isn’t bad luck—it’s structural risks: climate change, trade wars, and the shrinking pool of young farmers willing to take on the financial burden. The farmers who adapt—those who diversify, plan for succession, and manage debt carefully—will preserve and grow their net worth. The rest may find themselves selling out, not by choice, but by necessity.
What’s clear is that average Midwest farmer net worth isn’t a benchmark to aspire to—it’s a snapshot of a precarious balance. The farmers who weather storms aren’t the ones with the highest net worth on paper; they’re the ones who understand that wealth in agriculture isn’t just about assets. It’s about liquidity, timing, and the ability to say no—whether to a risky loan, an unprofitable crop, or a land sale that would break the family’s legacy.
Comprehensive FAQs
#### Q: How does the average Midwest farmer net worth compare to other U.S. farmers?
The Midwest’s average Midwest farmer net worth is higher than the national average ($1.8M vs. $1.3M, per USDA), thanks to larger-scale operations and higher land values. But regional differences exist: Pacific Northwest farmers (with timber and specialty crops) often have higher net worth, while Southern farmers (with smaller landholdings) lag behind.
####Q: Can a young farmer build significant net worth without inheriting land?
Yes, but it’s extremely difficult. Young farmers typically start with $100,000–$300,000 in savings and must secure debt to buy land or equipment. Without inherited equity, they’re at a disadvantage in bidding wars for land. Success stories often involve renting land initially, diversifying income (e.g., custom farming, agritourism), or securing government programs like USDA’s Beginning Farmer Loan Program.
####Q: How do droughts or floods affect Midwest farmer net worth?
Climate disasters directly erode net worth by reducing crop yields and increasing input costs (e.g., irrigation, replanting). A severe drought can cut a farm’s revenue by 30-50%, while flooding may destroy infrastructure (e.g., grain bins, fences). Insurance covers some losses, but deductibles and coverage gaps leave many farmers $200,000–$500,000 underwater after a major event.
####Q: Is it common for Midwest farmers to have negative net worth?
Negative net worth is rare but not unheard of, typically affecting beginning farmers or those in distress. The USDA estimates that 5-10% of farms operate at a net worth loss in any given year, often due to high debt, poor crop prices, or health crises. These farmers may rely on off-farm income, government subsidies, or family support to stay afloat.
####Q: How do farm subsidies impact average Midwest farmer net worth?
Subsidies (e.g., crop insurance, ARC/PLC payments) temporarily boost net worth by offsetting losses. In 2023, the average Midwest farm received $50,000–$150,000 in subsidies, which can mean the difference between breaking even and a net loss. However, subsidies don’t build long-term wealth—they’re a band-aid for structural issues like low commodity prices or high input costs.
####Q: What’s the biggest financial mistake Midwest farmers make?
The top mistake is overleveraging land. Many farmers treat land as a liquid asset, taking on debt to buy more acres during price peaks—only to face payment shocks when prices drop. Another common error is underestimating living expenses; even profitable farms can bleed cash if the operator assumes revenue will cover personal costs without a buffer.
####Q: How do farmers in the Midwest protect their net worth during downturns?
Strategies include:
- Diversifying income (e.g., adding livestock, agritourism, or renewable energy).
- Reducing debt by refinancing at lower rates or selling non-core assets.
- Locking in prices via futures contracts or supply agreements.
- Cutting discretionary spending (e.g., delaying equipment upgrades).
- Seeking off-farm income (e.g., farm management consulting, teaching).
Q: Will the average Midwest farmer net worth keep rising in the next decade?
It depends on three key factors:
- Land prices: If inflation persists, land values may rise, but debt costs could offset gains.
- Commodity prices: Geopolitical stability (e.g., U.S.-China trade) will determine crop profitability.
- Succession trends: If fewer farms transfer to the next generation, land consolidation could increase net worth for remaining operators but reduce overall farm numbers.
