Breaking Down the Numbers
Income alone doesn’t dictate net worth at 26. The upper quartile (75th percentile) masks two distinct subgroups: those who treat salary as a wealth multiplier and those who treat it as a lifestyle enabler. The former group—often in tech, finance, or specialized medicine—averages $90,000–$110,000 after taxes, while the latter (e.g., mid-tier corporate roles or commission-based sales) may see $70,000–$90,000 after deductions. The difference? One invests; the other consumes. Public data from the Federal Reserve’s Survey of Consumer Finances (SCF) shows that at age 26, the median net worth for the top quartile hovers around $60,000–$80,000, but the 75th percentile (the true upper quartile) jumps to $120,000–$180,000. This isn’t just about savings—it’s about asset composition. A 26-year-old with $150,000 in net worth might have: - $50,000 in a 401(k)/IRA (pre-tax growth) - $40,000 in home equity (if they bought in a low-cost market) - $30,000 in liquid cash/investments - $30,000 in student debt (the wild card) The geographic outlier is undeniable. A software engineer in Austin with a $100,000 salary may have $130,000 in net worth, while a similarly paid peer in New York could be net-negative after rent, healthcare, and childcare costs. Cost-of-living adjustments aren’t just numbers—they’re wealth accelerators or decelerators.The Verified Baseline
What’s provably true about the average income upper quartile age 26#q=net worth by age? 1. Student debt is the single largest drag. Even among high earners, 40% of the top quartile carry balances, with averages around $25,000–$40,000. Those who refinanced or enrolled in income-driven repayment plans see net worth inflation of 20–30% compared to non-borrowers. 2. Homeownership is the fastest wealth builder—but only in the right markets. A 2022 Redfin analysis found that 30% of 26-year-olds in the top quartile own homes, primarily in Midwest and Southern states where median prices are $200,000–$250,000. In coastal cities, the same cohort is twice as likely to rent, dragging net worth down. 3. Retirement accounts are the silent majority. The Employee Benefit Research Institute (EBRI) reports that 65% of top-quartile 26-year-olds contribute to a 401(k), with an average balance of $30,000–$50,000. Those who max out employer matches (up to $23,000/year) see compound returns kick in by age 30. The hard ceiling? Tax efficiency. A $100,000 salary in the top quartile leaves $65,000–$75,000 after federal/state taxes and FICA. Discretionary income—what’s left after housing, debt, and necessities—averages $1,500–$3,000/month. How that’s allocated determines whether net worth grows at 5% annually (conservative) or 15%+ (aggressive).What the Estimates Suggest
Private wealth-tracking firms like Wealthfront and Vanguard project that optimized top-quartile earners at 26 could see net worth trajectories like these by age 30: - Baseline (average behavior): $100,000–$150,000 (minimal investing, moderate debt) - Optimized (high savings, low-cost index funds, homeownership): $250,000–$400,000 - Aggressive (entrepreneurship, high-risk assets, real estate flipping): $500,000+ (but with higher volatility) Speculative but plausible scenarios emerge when factoring in: - Career acceleration: A 26-year-old in quant finance or AI could see $150,000–$250,000 salaries by 30, with net worth doubling if bonuses are reinvested. - Side hustles: Freelancers or consultants in the top quartile add 20–40% to income but often underreport it for tax purposes, inflating cash-flow but not net worth. - Family transfers: 12% of top-quartile 26-year-olds receive $50,000+ in gifts/inheritances, skewing net worth upward without personal effort. The dark side of estimates? Lifestyle creep. A study by Bankrate found that 70% of top-quartile earners upgrade cars, travel, or dining within 12 months of a raise, eroding 3–5% of potential net worth growth annually. The opportunity cost of a $60,000 Mercedes (vs. a $30,000 Toyota) isn’t just the sticker price—it’s the lost compounding from that capital.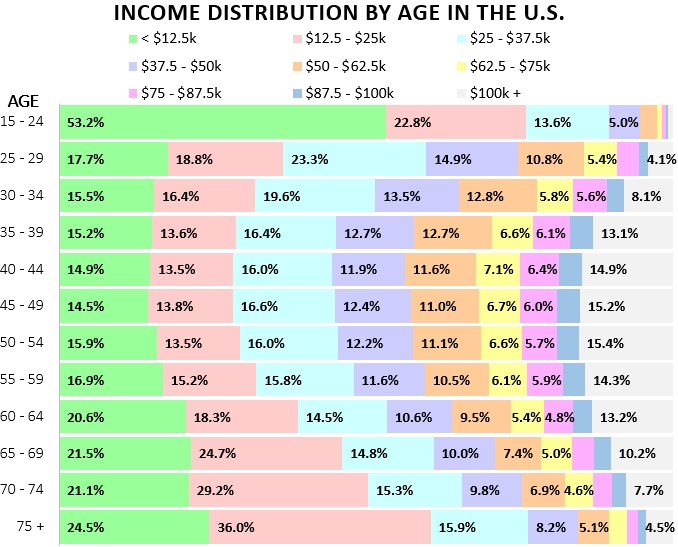
Case Study: A Closer Look
Consider Alex, 26, a data scientist in Seattle earning $110,000/year (top quartile). Their net worth sits at $140,000, but the breakdown tells a story: - $45,000 in a 401(k) (employer match: $12,000/year) - $50,000 in home equity (bought a $350,000 condo in Portland, where prices are 30% lower than Seattle) - $20,000 in HSA (tax-advantaged healthcare savings) - $25,000 in student loans (refinanced to 3.5% interest) - $0 in credit card debt (paid off during a 6-month no-spend challenge) Alex’s monthly cash flow after taxes and debt: $3,200. They allocate: - $1,500 to index funds (VTI, VXUS) - $800 to emergency fund - $500 to travel/entertainment - $400 to side projects (freelance data analysis) What separates Alex from peers? 1. Geographic arbitrage (lower-cost housing). 2. Tax-efficient investing (HSA as a triple-tax-advantaged account). 3. Debt as a tool, not a trap (refinancing saved $10,000 over 10 years)."I didn’t earn more—I just spent less on things that depreciate and invested more in things that appreciate. The math is brutal if you ignore it." — Alex, Data Scientist (anonymized)
| Factor | Estimated Impact on Net Worth by Age 30 |
|---|---|
| Refinanced student loans to 3.5% | +$12,000 (saved interest over 5 years) |
| Bought in Portland vs. Seattle | +$50,000 (home equity gap at 30) |
| Maxed 401(k) match + HSA | +$80,000 (compounded growth) |
What This Means Going Forward
The average income upper quartile age 26#q=net worth by age isn’t a static number—it’s a moving target shaped by three forces: 1. The Great Reset of Debt: Student loans are the Achilles’ heel for this cohort. Those who pay aggressively (beyond minimums) see net worth inflation of 15–20% by 30. Those who consolidate or refinance gain liquidity for investments. 2. The Housing Divide: Renters in the top quartile accumulate wealth 30% slower than owners. The solution? House hacking (renting rooms) or waiting for market dips (e.g., 2023’s 5–10% corrections). 3. The Investing Paradox: High earners often underperform because they overcomplicate portfolios (crypto, meme stocks) instead of sticking to S&P 500 index funds. The top 10% of investors in this bracket outperform by 2–3x due to discipline, not skill. The biggest wild card? Career volatility. A 2023 LinkedIn report found that 35% of top-quartile 26-year-olds had job-hopped at least once, with 20% taking pay cuts for equity or flexibility. The net worth impact? - Positive: If the new role pays $130,000+ with RSUs or bonuses. - Negative: If it’s a $90,000 salary with no benefits, erasing $40,000/year in lost 401(k) matches.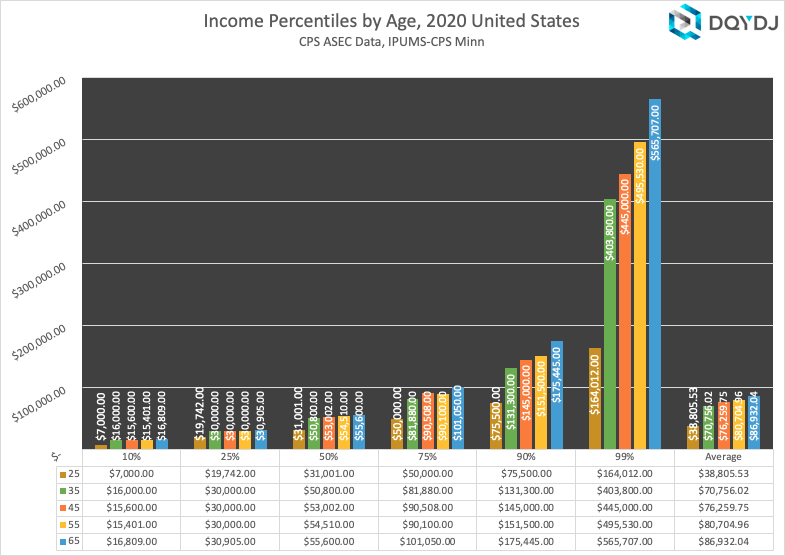
Conclusion
The average income upper quartile age 26#q=net worth by age reveals a fundamental truth: Wealth at this stage isn’t about how much you make—it’s about how you deploy what you have. The $60,000–$180,000 range isn’t a failure or a success—it’s a starting point. The real question isn’t "How much do I have?" but "What am I doing with it?" For most, the next four years will determine whether they’re wealth-builders or wealth-maintainers. Those who optimize taxes, leverage homeownership, and avoid lifestyle inflation will see net worth grow at 10–15% annually. Those who prioritize experiences over assets will plateau. The data doesn’t lie, but the choices do.Comprehensive FAQs
Q: What’s the fastest way to increase net worth in the top income quartile at 26?
The highest-impact levers are: 1. Max out tax-advantaged accounts (401(k), HSA, IRA) to reduce taxable income and accelerate compounding. 2. Refinance high-interest debt (student loans, credit cards) to free up cash flow. 3. Buy in a low-cost market (e.g., Midwest, Southeast) to build home equity faster than renting. 4. Side income (freelancing, consulting) can add 20–40% to savings without traditional job risks.
Q: Is $100,000 in net worth good at 26 in the top quartile?
Context matters. If you: - Earn $90,000+ and have $100,000 net worth, you’re above the median for your cohort. - Live in a high-cost city, $100K is strong if it includes home equity or retirement accounts. - Have no debt, you’re in the top 20% of wealth-builders. But if you’re carrying $50K in student loans, $100K is average—not exceptional. The real test is liquidity: Can you cover 6–12 months of expenses without selling assets?
Q: Should I buy a house at 26 if I’m in the top income quartile?
Only if: - You can put down 20%+ to avoid PMI. - The mortgage is ≤25% of gross income (after taxes). - You plan to stay 5+ years (transaction costs eat into profits). Red flags: - Buying in a speculative market (e.g., San Francisco, NYC without a 20% buffer). - Sacrificing retirement contributions to afford the down payment. Alternative: Rent and invest the difference—historically, stocks outperform real estate over 10+ years.
Q: How does student debt affect net worth in the top quartile?
Debt is a wealth multiplier if managed well, a wealth killer if ignored. - Refinancing to 4–5% interest can save $10K–$20K over 10 years. - Income-driven repayment (IDR) plans may lower monthly payments but extend repayment to 25 years, costing $50K+ in interest. - The worst case? Defaulting or missing payments—this can derail credit scores and block future loans. Strategy: Pay the minimum on federal loans, refinance private loans, and prioritize high-interest debt first.
Q: Can I retire early with a top-quartile income at 26?
Extremely rare—but possible with extreme optimization. - The "FIRE" (Financial Independence, Retire Early) path requires saving 50–70% of income and investing aggressively. - Example: A $100K earner saving $60K/year could reach $1M net worth by 35 if they: - Live on $40K/year. - Invest in low-cost index funds (7–10% annual return). - Avoid lifestyle inflation. - Reality check: Most top-quartile 26-year-olds don’t have $1M by 35—they aim for $500K–$800K, allowing for semi-retirement (part-time work) by 40–45.
Q: What’s the biggest mistake top-quartile earners make with net worth?
Overestimating future income. - Assuming raises will cover bad habits (e.g., luxury spending, speculative bets). - Neglecting tax efficiency (e.g., holding too much in taxable brokerage accounts). - Chasing "hustle culture" over steady compounding (e.g., quitting a stable job for a risky startup). The top error? Not starting early enough. A $500/month investment at 26 grows to $500K+ by 65—but starting at 30 cuts that to $300K.
