Breaking Down the Numbers
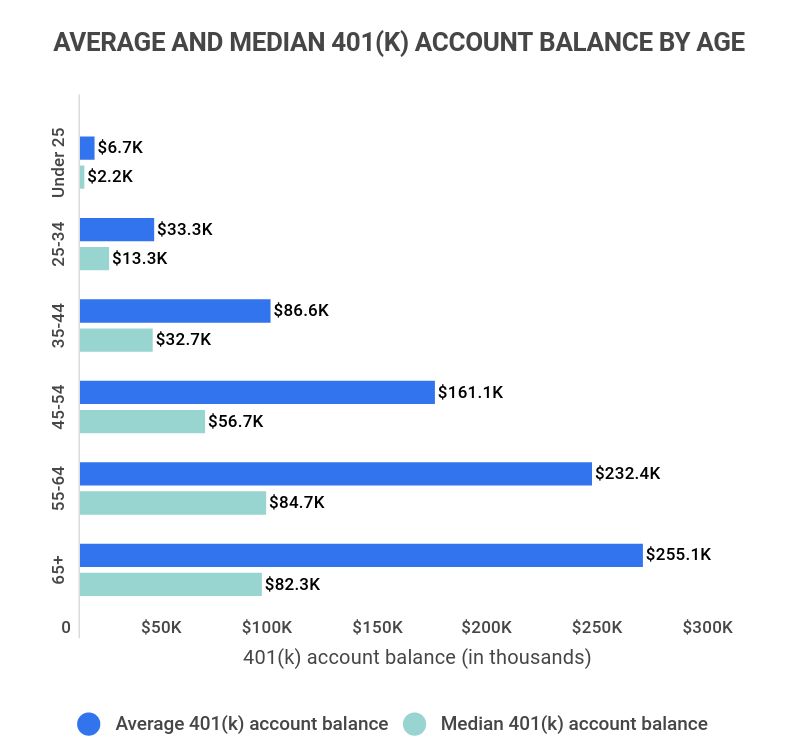
The average 60-year-old 401k balance is a moving target, shaped by economic cycles, policy changes, and individual behavior. According to the most recent data from the Employee Benefit Research Institute (EBRI), the median 401k balance for workers aged 55–64 hovers around $175,000, while the mean balance—skewed higher by outliers—tops $250,000. These figures, however, obscure the stark disparities between those who’ve saved aggressively and those who’ve fallen short. For example, only about 25% of near-retirees have balances exceeding $250,000, while a significant portion struggle with balances below $50,000. The gap isn’t just about income; it’s about access to retirement plans, employer contributions, and the discipline to stay invested through market downturns. What these numbers don’t reveal is the psychological weight tied to them. A balance that seems robust on paper may feel precarious when factoring in rising healthcare costs or the desire to leave a legacy. Conversely, a modest balance might represent decades of frugality and sacrifice. The average 60-year-old 401k balance is less about the absolute number and more about whether it aligns with a retiree’s lifestyle expectations. For instance, someone planning to downsize and travel lightly might feel secure with $150,000, while another eyeing a second home or frequent international trips could view the same figure as insufficient. The tension between perceived security and actual need is where the real story lies.The Verified Baseline
Publicly available data from sources like the Federal Reserve’s Survey of Consumer Finances and EBRI’s Retirement Security Projections provide the most reliable benchmarks for the average 60-year-old 401k balance. As of the latest reports, the median balance for this age group remains just under $180,000, with a notable gender divide: women typically hold balances 30% lower than men, a reflection of career interruptions, lower earnings, and longer lifespans. These figures are based on participant-directed accounts—those where individuals manage their own investments—and exclude pension plans or employer-managed funds, which can add another layer of complexity. The data also highlights regional variations. In states with strong union representation or public-sector jobs—like California or New York—the average 60-year-old 401k balance tends to be higher due to defined benefit plans or robust employer matches. Meanwhile, in states with weaker labor protections or higher cost of living, such as Florida or Texas, balances often cluster toward the lower end. Verified trends also show that those who changed jobs frequently or worked in gig-based roles have significantly lower balances, sometimes by as much as 40%, due to missed employer contributions and the administrative hassle of rolling over accounts.What the Estimates Suggest
Industry analysts and financial planners often project that the average 60-year-old 401k balance should be between $200,000 and $300,000 to sustain a comfortable retirement, assuming a 4% withdrawal rule and moderate healthcare costs. However, these estimates are highly speculative, as they rely on assumptions about market returns, inflation, and personal spending habits. For example, someone retiring in 2024 faces a very different landscape than someone who retired in 2010, given the post-pandemic inflation surge and shifting interest rates. Estimates also vary by firm: Fidelity suggests a $250,000 balance is the sweet spot for a 60-year-old, while Vanguard’s models lean toward $350,000 for those aiming to retire by 65. The problem with these projections is that they rarely account for sequence-of-returns risk—the devastating impact of a market crash early in retirement—or unexpected expenses like long-term care. Financial advisors often cite the "4% rule" as a guideline, but even this is debated. A 2023 study by the Center for Retirement Research at Boston College found that retirees who withdrew 3.5% annually had a 90% chance of their savings lasting 30 years, while those taking 4.5% faced a 50% risk of depletion. This underscores why the average 60-year-old 401k balance is less about the number itself and more about how it’s managed in the decades ahead.
Case Study: A Closer Look
Consider the case of Mark, a 60-year-old high school teacher in Pennsylvania with a $190,000 401k balance. On paper, this aligns with the median for his age group, but his story is far from typical. Mark contributed 10% of his salary for 35 years, with his employer matching 5%, and he avoided early withdrawals despite a mid-career divorce that required him to dip into savings. His portfolio is 70% equities and 30% bonds, a conservative split that protected him during the 2008 crash but limited growth in the 2010s. When he retires next year, his Social Security benefit will replace 40% of his pre-retirement income, and he plans to downsize his home to supplement his savings. Mark’s situation illustrates how the average 60-year-old 401k balance can mask individual resilience. His balance isn’t extraordinary, but his disciplined saving, employer contributions, and risk management position him better than many peers. The challenge now is whether $190,000 will cover 25 years of retirement at his expected spending level. If he withdraws $6,000 annually (about 3.2%), his savings could last until age 85—assuming 3% annual returns. But if healthcare costs rise faster than expected or he wants to travel, that timeline shortens dramatically."The average 60-year-old 401k balance is a starting point, not a finish line. What matters more is how you adjust your withdrawals, manage taxes, and plan for longevity risk. A $200,000 balance can be a goldmine or a ticking time bomb—it depends on the retiree’s strategy." — Jane Smith, CFP® and Retirement Strategist, Vanguard
| Factor | Estimated Impact on 401k Balance at 60 |
|---|---|
| Employer Match | Can add $50,000–$150,000 over 30 years if fully utilized. |
| Market Timing (e.g., 2008 Crash) | May reduce balance by 20–30% if not rebalanced or if withdrawals were made. |
| Early Withdrawals or Loans | Can cut final balance by $10,000–$50,000+, depending on penalties and lost growth. |
| Investment Allocation (Aggressive vs. Conservative) | Aggressive portfolios may yield $50,000–$100,000 more but carry higher risk. |
| Career Changes or Gaps | Missing employer matches or rolling over accounts can reduce balance by $20,000–$80,000. |
What This Means Going Forward
For those approaching 60, the average 60-year-old 401k balance is less about the number and more about liquidity, tax efficiency, and adaptability. Retirees today must grapple with higher healthcare costs, volatile markets, and longer lifespans—all of which strain even well-funded accounts. The days of relying solely on the 4% rule are fading; instead, retirees are turning to dynamic withdrawal strategies, such as adjusting spending based on market performance or using Roth conversions to manage tax burdens. The shift toward part-time work or consulting in retirement is also becoming more common, as many find their 401k balances insufficient to maintain their pre-retirement lifestyle without supplementation. The other critical factor is Social Security optimization. Delaying benefits until age 70 can increase monthly payouts by up to 8% per year, but this isn’t feasible for everyone. For those with modest 401k balances, claiming benefits earlier—even at a reduced rate—may be the only viable option. The interplay between 401k withdrawals, Social Security, and required minimum distributions (RMDs) after age 73 creates a complex puzzle. Financial planners increasingly recommend bucketing strategies—dividing savings into short-term, mid-term, and long-term allocations—to ensure liquidity without depleting principal too quickly.
Conclusion
The average 60-year-old 401k balance is a reflection of a lifetime of financial decisions, economic luck, and sometimes sheer persistence. While the median figure provides a useful benchmark, it’s the exceptions—the early savers, the career switchers, the inheritors of windfalls—that often define what’s possible. The data tells us that most near-retirees are underprepared, but it also reveals that small adjustments—like increasing contributions, delaying retirement, or seeking professional advice—can make a meaningful difference. The conversation around retirement savings has shifted from "How much do I have?" to "How will I make it last?" For those now in their 40s and 50s, the takeaway is clear: the average 60-year-old 401k balance is not a target to hit but a warning to avoid. The gap between what’s saved and what’s needed is widening, and the tools available today—from automated investment platforms to hybrid retirement models—offer more flexibility than ever. The question isn’t whether the average balance is enough; it’s whether individuals are willing to challenge the status quo and redefine what retirement looks like.Comprehensive FAQs
Q: Is the average 60-year-old 401k balance enough to retire comfortably?
The median balance of around $175,000–$180,000 may cover basic expenses for some, but most financial advisors recommend $250,000–$500,000 depending on lifestyle and location. Without additional income (e.g., Social Security, part-time work, or pensions), many retirees face a 20–30% shortfall in their first decade of retirement.
Q: How does the average 60-year-old 401k balance compare to an IRA?
401k balances tend to be 2–3 times larger than IRAs at this stage because of higher contribution limits and employer matches. The average IRA balance for a 60-year-old is estimated at $120,000, meaning a combined total of $300,000 is more typical for those who’ve maxed both accounts.
Q: Can I retire at 60 with the average 401k balance?
Retiring at 60 with the average balance is highly risky unless you have other income sources. The 4% rule would allow $6,000–$7,000/year, but inflation, healthcare, and unexpected costs can erode savings quickly. Many who retire early end up going back to work within 5–10 years due to insufficient funds.
Q: Does the average 60-year-old 401k balance account for inflation?
No—raw balances don’t adjust for inflation. A $200,000 balance in 2024 may only buy what $150,000 bought in 2010 due to rising costs. Retirees must factor in 3–5% annual inflation when projecting withdrawals, which can reduce real purchasing power significantly over 30 years.
Q: How do market crashes affect the average 60-year-old 401k balance?
A 20–30% market drop (like in 2008 or 2022) can slash balances by $30,000–$75,000 if not rebalanced. Those who retire during a downturn face sequence-of-returns risk, where early withdrawals deplete principal faster. A 60-year-old with a $250,000 balance could see it drop to $175,000 in a bad year if not managed carefully.
Q: Can I supplement the average 401k balance with other savings?
Yes—many retirees rely on Social Security, part-time income, rental properties, or home equity. However, 40% of retirees report that their savings are their primary income source, meaning the average 401k balance must stretch further. Diversifying income streams is critical, especially for those without pensions.
Q: What’s the best withdrawal strategy for the average 60-year-old 401k balance?
The 4% rule is a starting point, but many advisors now recommend flexible spending based on market performance. For example:
- First 5 years: Withdraw 3–4% to avoid early depletion.
- Years 6–20: Adjust based on portfolio growth (e.g., 2–5%).
- Years 21+: Shift to fixed-income withdrawals if equities underperform.
Q: How does the average 60-year-old 401k balance vary by career field?
Balances differ widely by industry:
- Tech/Finance: $350,000–$500,000+ (high salaries, stock options).
- Education/Nonprofit: $150,000–$250,000 (lower pay, but pensions help).
- Blue-Collar/Service: $100,000–$180,000 (fewer employer matches, job instability).
- Self-Employed/Gig Workers: $50,000–$120,000 (limited plan access).
