
The Short Answers
- The median 401k balance at 35 is estimated at $45,000, but this varies sharply by income and location.
- By 50, the average balance climbs to $120,000–$150,000, assuming consistent contributions and market returns.
- Top earners in the 90th percentile at 60 may have $750,000+, while the median hovers around $200,000.
- Employer matches and catch-up contributions (after 50) are the two biggest levers moving these averages.
Deep Dive: The Full Picture
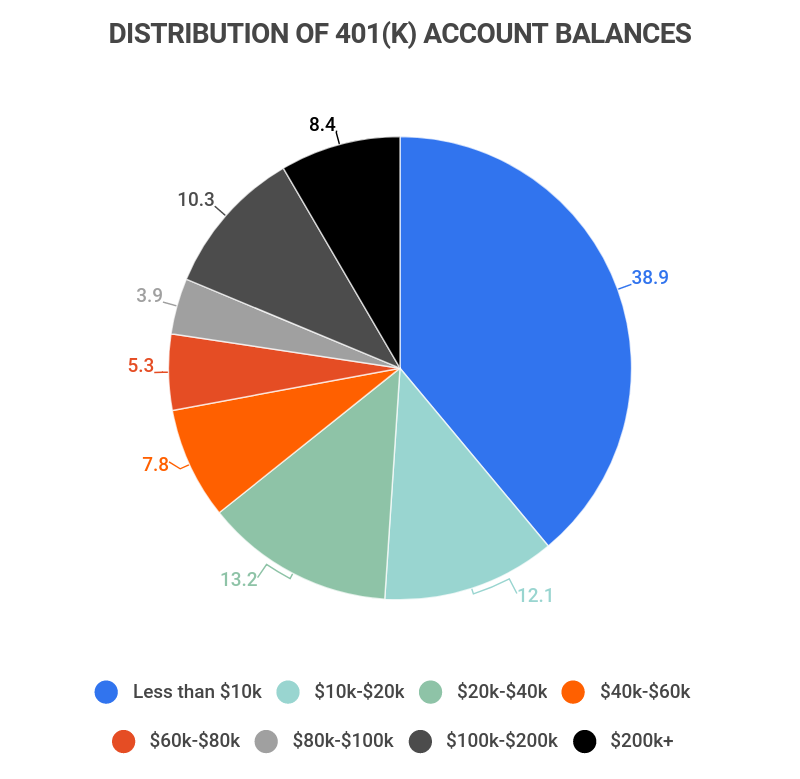
The average 401k balance by age is often cited as a benchmark, but its usefulness depends on context. A 2023 Fidelity report suggested that by age 40, the median balance was around $70,000, yet this figure obscures critical details. For instance, a teacher in a defined-benefit system might have a pension covering 80% of their salary, making a 401k less critical. Conversely, a gig worker with no employer plan relies entirely on personal savings, skewing the data. The averages also flatten regional differences: a $100,000 balance in Austin might fund a comfortable retirement, while the same in New York could require drastic adjustments. What’s less discussed is how these balances interact with other retirement accounts. Many high-net-worth individuals supplement 401ks with IRAs, HSAs, or brokerage accounts, creating a fragmented savings picture. The average 401k balance by age thus understates total retirement readiness. Additionally, the data doesn’t reflect behavioral shifts—such as pausing contributions during downturns or taking early withdrawals—which can derail long-term growth. The numbers are static; real-life finances are dynamic.The Context You Need
Understanding the average 401k balance by age requires acknowledging two forces: structural economics and individual agency. Structural factors include wage stagnation, rising healthcare costs, and the decline of traditional pensions. Since the 1980s, defined-contribution plans like 401ks have replaced defined-benefit pensions, shifting risk from employers to employees. This transition explains why younger workers face higher volatility in their retirement trajectories. Meanwhile, individual agency—salary negotiations, investment choices, and debt management—determines how closely one’s balance aligns with the average. The data also reflects generational differences. Gen Xers, who entered the workforce during the dot-com boom, saw their 401ks grow faster than millennials, who faced the 2008 crash and stagnant wages. By contrast, Gen Z workers today benefit from lower student debt (for some) but enter a market with higher living costs. These shifts mean the average 401k balance by age isn’t just a function of time—it’s a product of economic eras.The Mechanics
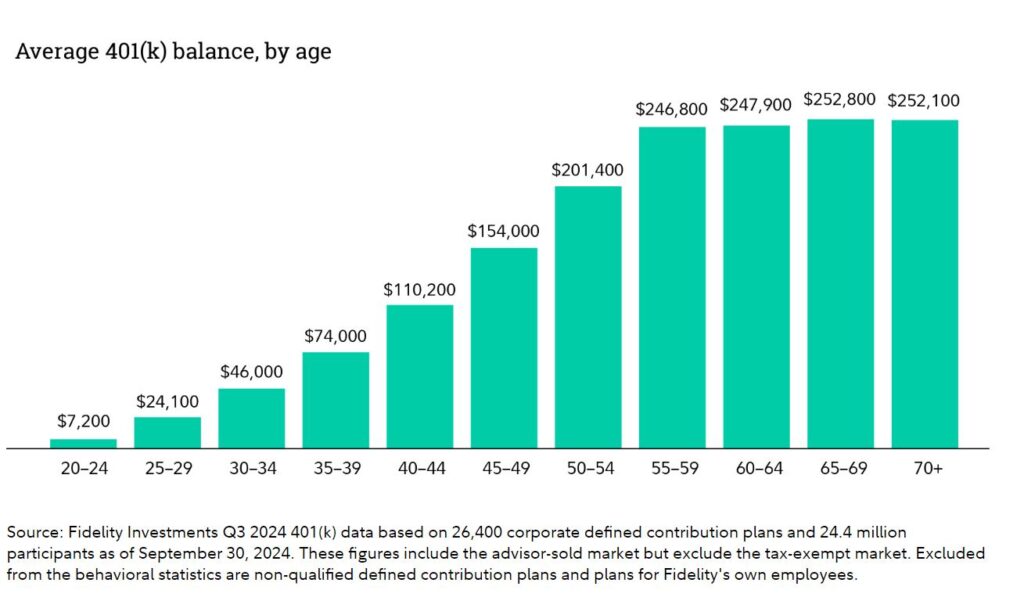
The mechanics behind the average 401k balance by age revolve around three pillars: contribution limits, employer matches, and market performance. The IRS sets annual contribution caps ($23,000 in 2024 for under-50, $30,500 for 50+), but most workers contribute far less. A 2022 EBRI study found the average deferral rate was just 7.5% of salary, leaving significant room for growth. Employer matches—typically 3–5%—are the wild card. Someone earning $80,000 with a 4% match could add $3,200 annually without lifting a finger, a boost that compounds over decades. Market performance is the third variable. A 401k’s average balance by age assumes a 7% annual return, but real-world outcomes vary. The S&P 500’s 10-year return (2014–2024) was ~12%, while the 20-year return (2004–2024) was ~8%. A worker who retired in 2000 with a $200,000 balance saw it halved by 2002; those who stayed invested recovered by 2013. These fluctuations mean the average 401k balance by age is a moving target, not a fixed benchmark.Details That Change the Picture
The average 401k balance by age hides regional and occupational divides. A financial analyst in Boston with a $150,000 salary and a 6% match will outpace a barista in Dallas earning $30,000 with no match, even if both contribute 10% of their pay. The cost of living distorts comparisons: a $300,000 balance in San Francisco may not stretch as far as $200,000 in rural Mississippi. Similarly, industries with high turnover—hospitality, retail—see lower balances because workers switch jobs frequently, leaving gaps in contributions. Another layer is loan activity. Nearly 20% of 401k holders take loans or hardship withdrawals, often to cover emergencies or medical bills. These actions create a permanent drag on balances. A $50,000 loan taken at 40, repaid with interest, might reduce the average 401k balance by age 50 by 15–20%. The data doesn’t capture these penalties, yet they’re common enough to skew long-term outcomes."The average 401k balance by age is a red herring if you don’t account for the hidden costs of living—healthcare, long-term care, and inflation. A $500,000 nest egg in 2024 might not cover a $10,000 annual premium for Medicare Supplement Plan G in 2044." — Todd Tressider, CFP and Retirement Strategist
| Age | Median 401k Balance (Est.) |
|---|---|
| 30 | $40,000–$50,000 |
| 40 | $100,000–$120,000 |
| 50 | $180,000–$220,000 |
| 60 | $250,000–$350,000 |
| 67 (Full Retirement Age) | $300,000–$500,000+ |
Conclusion
The average 401k balance by age serves as a rough guide, but its limitations are obvious. It doesn’t account for pensions, Social Security benefits, or side income. It ignores the fact that a $1 million balance at 65 might not be enough if healthcare costs rise 5% annually. The real takeaway is that retirement readiness isn’t about hitting a number—it’s about sustainability. Someone with $200,000 at 50 could retire comfortably if they live frugally, while a $500,000 balance might vanish quickly if inflation outpaces withdrawals. The data also underscores the need for personalized planning. A 30-year-old earning $60,000 should aim for a $150,000 balance by 40, but a 50-year-old earning $120,000 might need $300,000 to retire by 60. The averages are starting points, not destinations. The most successful savers don’t chase benchmarks—they adjust for their own circumstances, whether that means contributing more, investing in low-fee funds, or negotiating better employer matches.Comprehensive FAQs
Q: How does a 401k loan affect the average 401k balance by age?
A: A 401k loan reduces your balance temporarily, but if repaid with interest, it doesn’t eliminate growth. However, if you leave your job or can’t repay, the loan becomes a taxable withdrawal, often with a 10% penalty. This can derail long-term savings, especially if taken in your 40s or 50s when compounding is critical.
Q: Can I rely solely on the average 401k balance by age to plan retirement?
A: No. The averages are median figures—they don’t account for your specific expenses, healthcare costs, or inflation. A better approach is to calculate your annual withdrawal rate (e.g., 4% rule) and adjust for your lifestyle. Tools like the Trinity Study or a CFP can help tailor a plan.
Q: Why do some people have much higher 401k balances than the average by their age?
A: Higher balances often result from earlier starts, higher salaries, employer matches, or aggressive investing (e.g., stock-heavy portfolios). Top earners also benefit from catch-up contributions (after 50) and may supplement 401ks with IRAs or brokerage accounts. Location matters too—high-cost areas require larger balances to maintain the same lifestyle.
Q: What’s the biggest mistake people make when comparing their 401k to the average by age?
A: Assuming the average applies to them without context. A single parent with student debt, a healthcare worker with irregular hours, or a freelancer with no employer plan won’t follow the same trajectory as a corporate employee with a 401k match. The mistake is benchmarking without adjusting for personal circumstances—like comparing apples to oranges.
Q: How can I improve my 401k balance if I’m behind the average for my age?
A: Focus on three levers: 1) Increase contributions (even by 1–2% of salary), 2) optimize investments (low-cost index funds), and 3) leverage catch-up contributions (if over 50). If your employer offers a match, contribute enough to get the full match—it’s free money. For those far behind, consider side income or part-time work to boost savings.
