The Arnault family companies don’t just compete in luxury—they redefine it. Bernard Arnault, the patriarch, built LVMH into the world’s largest luxury conglomerate by acquisition, not just organic growth. His empire now spans wine, fashion, jewelry, and even media, with brands like Louis Vuitton, Dior, and Tiffany & Co. under one roof. The strategy isn’t just about selling products; it’s about controlling the narrative of exclusivity, supply chains, and even cultural trends.
What sets the Arnault family companies apart is their vertical integration. Unlike traditional conglomerates, LVMH owns everything from leather workshops in Italy to vineyards in Bordeaux. This control ensures quality—but it also raises questions about labor practices, pricing power, and whether luxury is becoming a monopoly. The family’s influence extends beyond commerce: Arnault’s stakes in media outlets like
Les Échos and
Le Parisien allow him to shape public perception of his brands.
Critics argue the Arnault family companies operate with an opacity that borders on secrecy. While financial disclosures exist, the lack of granular transparency—especially around private deals—fuels speculation. The family’s wealth, estimated in the hundreds of billions, is tied to these entities, yet their exact valuations and internal dynamics remain guarded. This article cuts through the noise to examine what’s known, what’s assumed, and where the confusion lies.
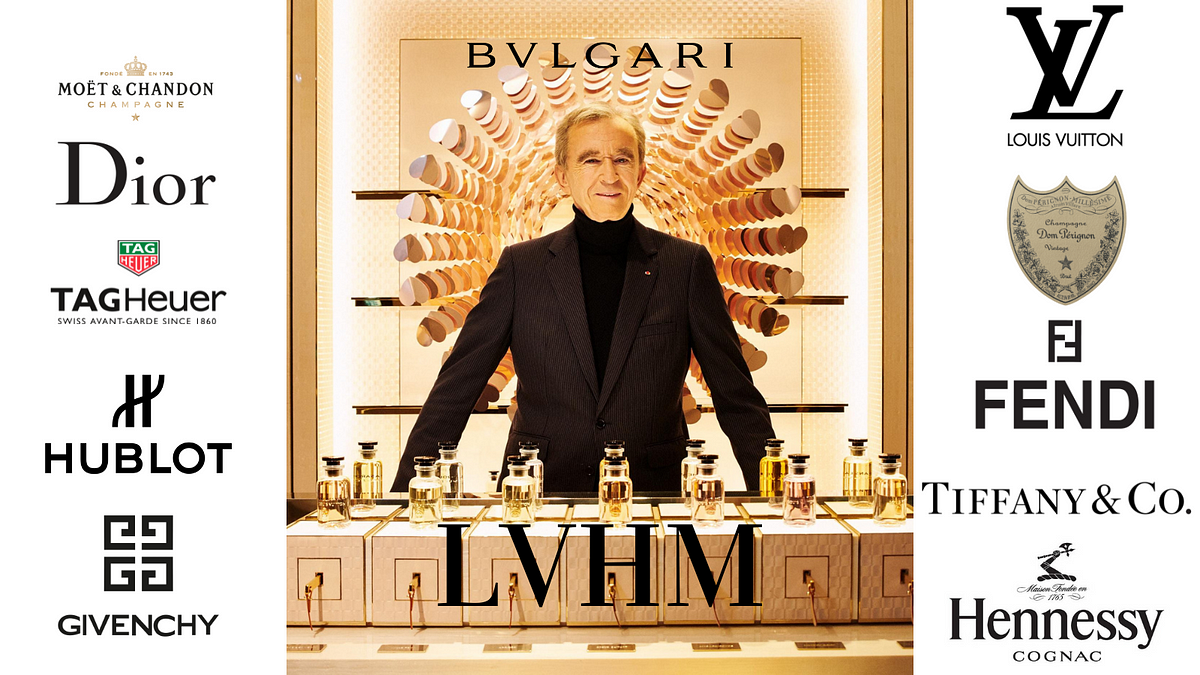
Common Myths About the Arnault Family Companies
The Arnault family companies are often misunderstood as a monolithic force where Bernard Arnault makes all decisions. In reality, the group operates through a complex web of holding companies, with key executives at LVMH and its subsidiaries wielding significant autonomy. The myth of a single "Arnault mind" controlling every move ignores the decentralized nature of luxury brand management—where creative directors at Dior or Tiffany have more leeway than most CEOs in corporate America.
Another persistent myth is that the Arnault family companies rely solely on Chinese demand to drive growth. While Asia remains a critical market, LVMH’s revenue streams are diversified across Europe, the U.S., and emerging economies. The family’s long-term strategy involves balancing geographic risks, not betting everything on one region. Even during the pandemic, when Chinese tourism stalled, LVMH’s e-commerce and wholesale channels in the West mitigated losses—a resilience that contradicts the "China-dependent" narrative.
####
Myth 1: The Arnault Family Companies Are Purely About Luxury Goods
The assumption that LVMH and its subsidiaries exist only to sell handbags and perfume overlooks the group’s aggressive expansion into adjacent sectors. Wine—through Moët Hennessy—accounts for nearly a third of LVMH’s revenue, with brands like Dom Pérignon and Veuve Clicquot outperforming many fashion lines. The family’s companies also own retail media networks (like
Vogue and
Elle) and even real estate ventures, blurring the line between product and platform.
Beyond revenue, this diversification serves a cultural purpose. By owning
Le Parisien or
Les Échos, the Arnault family companies subtly influence public discourse around their brands. A positive editorial on Dior’s latest collection isn’t just advertising—it’s shaping how the brand is perceived globally. This multi-pronged approach ensures that the Arnault family companies aren’t just selling products; they’re curating lifestyles.
####
Myth 2: Bernard Arnault’s Wealth Comes Solely from LVMH Stock
While LVMH’s public shares form the backbone of Arnault’s fortune, private holdings and family trusts play a far larger role. The Arnault family companies structure their wealth through complex entities, including offshore vehicles and real estate assets. Arnault himself owns less than 1% of LVMH’s shares directly; the rest is held by his family’s trusts and private companies, which are opaque by design.
This dispersion isn’t just tax strategy—it’s risk management. By not concentrating wealth in a single entity, the family protects against volatility in LVMH’s stock or luxury market downturns. The result? A net worth that fluctuates with private valuations, not just quarterly earnings reports. Speculation about Arnault’s exact wealth often ignores these layers, leading to exaggerated or understated figures.
####
Myth 3: The Arnault Family Companies Avoid Controversy
LVMH’s PR machine is formidable, but scandals still emerge—often tied to labor practices or environmental concerns. In 2021, reports surfaced about underpaid workers in LVMH’s leather tanneries, prompting investigations. The family’s companies have also faced criticism for greenwashing, with critics arguing that sustainability initiatives are superficial compared to their carbon footprint. Yet, these issues rarely dent LVMH’s market dominance, proving that even controversies can be managed within the luxury ecosystem.
The myth persists because the Arnault family companies invest heavily in crisis communications. When a scandal breaks, LVMH’s legal and PR teams act swiftly to contain damage, often burying stories in legal settlements or shifting focus to new collections. This doesn’t mean controversies don’t exist—just that they’re rarely fatal to the brand’s image.
What Holds Up to Scrutiny
At its core, the Arnault family companies’ success hinges on two verifiable pillars:
asset consolidation and brand synergy. Unlike rivals that acquire brands and let them operate independently, LVMH integrates acquisitions into its ecosystem. A new acquisition like Tiffany & Co. isn’t just added to the portfolio—it’s folded into LVMH’s global distribution, marketing, and supply chains. This creates a flywheel effect where each brand benefits from the others’ strengths.
The evidence supports this model. LVMH’s revenue has grown
consistently for decades, outpacing competitors like Kering or Richemont. While exact margins are private, industry analysts cite LVMH’s gross margins—often above 60%—as proof of its pricing power. The family’s companies also benefit from cross-brand promotions, where a Dior perfume ad might feature Louis Vuitton accessories, maximizing revenue per customer.
>
"LVMH doesn’t just own brands; it owns the language of luxury." —
Financial Times, 2022
|
Common Belief | What the Evidence Says |
|----------------------------------|------------------------------------------------------|
| The Arnault family companies are all about China. | Asia drives ~30% of revenue; Europe and the U.S. are equally critical. |
| Bernard Arnault controls everything. | Subsidiaries like Dior have creative autonomy. |
| LVMH’s growth is unsustainable. | Revenue growth outpaces GDP in luxury markets. |
| The family avoids all criticism. | Labor and environmental issues resurface periodically. |
Why the Confusion Persists
The Arnault family companies thrive in ambiguity. Their financial disclosures are
voluntary—LVMH publishes annual reports, but private deals (like the Tiffany acquisition) are structured to minimize public scrutiny. The family’s use of holding companies, trusts, and offshore entities creates layers of opacity, making it difficult to trace wealth flows. Even when details emerge, they’re often framed as "strategic moves" rather than revelations.
Media also plays a role. Outlets focused on Arnault’s wealth often rely on proxy metrics (like LVMH’s stock price) rather than digging into private valuations. The result? A narrative that conflates public performance with private reality. Until the Arnault family companies adopt full transparency—unlikely given their competitive edge—this confusion will persist.
Conclusion
The Arnault family companies represent a rare convergence of industrial might and cultural influence. Their ability to merge business acumen with brand storytelling has made them untouchable in luxury—yet their methods remain a subject of debate. The family’s empire isn’t just about selling products; it’s about controlling the systems that define what luxury means.
For outsiders, the opacity is frustrating. But for competitors, it’s a blueprint: own the supply chain, dominate distribution, and shape the narrative. Whether through wine, fashion, or media, the Arnault family companies don’t just participate in luxury—they dictate its rules.
Comprehensive FAQs
#### Q: How many brands does LVMH own?
A: LVMH’s portfolio includes over 75 brands, spanning fashion (Louis Vuitton, Dior), wine (Moët & Chandon, Dom Pérignon), watches (Tag Heuer), and retail media (
Vogue,
Le Parisien). The exact number fluctuates with acquisitions and divestments, but the group’s strategy prioritizes quality over quantity—focusing on brands that align with its "luxury" identity.
#### Q: Is Bernard Arnault the sole decision-maker in the Arnault family companies?
A: No. While Arnault sets long-term strategy, LVMH’s subsidiaries operate with significant autonomy. Creative directors at Dior or Tiffany have final say on designs, and regional executives manage local markets. Arnault’s role is more about vision and acquisitions than micromanagement—though his influence is undeniable in high-stakes decisions like the Tiffany purchase.
#### Q: How does the Arnault family companies’ structure protect against market downturns?
A: Diversification is key. LVMH’s revenue streams—wine, fashion, jewelry, media—are designed to offset risks. For example, when luxury goods sales dipped during the pandemic, wine and e-commerce revenue held steady. Additionally, the family’s wealth isn’t concentrated in LVMH stock; private holdings and trusts provide a buffer against volatility.
#### Q: Have the Arnault family companies faced major legal challenges?
A: Yes, but most have been resolved quietly. Labor disputes in Italy and France (over wages and conditions in tanneries) led to settlements. Environmental concerns—like accusations of greenwashing—have prompted internal audits but no major lawsuits. The family’s companies also navigate antitrust scrutiny, particularly in Europe, where regulators watch mergers like the Tiffany deal closely.
#### Q: What’s the biggest misconception about the Arnault family companies’ growth strategy?
A: The idea that they only chase short-term profits. While LVMH’s stock performance is a priority, the family’s long-term play involves building moats—controlling distribution, owning iconic brands, and shaping consumer behavior. Acquisitions like Tiffany weren’t just financial moves; they were about securing dominance in the jewelry market for decades.
#### Q: How do the Arnault family companies influence fashion trends?
A: Through ownership and cultural leverage. Brands like Dior and Louis Vuitton set trends, but LVMH’s media assets (
Vogue,
Elle) amplify them. A Dior runway show isn’t just a fashion event—it’s a global spectacle promoted across LVMH’s networks. This vertical integration ensures that trends don’t just emerge from designers; they’re orchestrated by the conglomerate itself.

