
The Short Answers
- Yes, some high-net-worth individuals qualify for ACA subsidies if their MAGI falls below 400% of the federal poverty level, even if their assets exceed $1 million.
- The IRS primarily audits subsidies when income spikes (e.g., bonus payments, capital gains) or documentation is inconsistent (e.g., missing W-2s for freelance work).
- Trusts and LLCs can complicate eligibility—distributions from these entities are taxable income, even if not withdrawn.
- States with their own exchanges (like California or New York) may have stricter income verification than Healthcare.gov.
- If caught, repayment includes back taxes, penalties, and potential fraud charges—though the IRS often resolves cases via settlements.

Deep Dive: The Full Picture
The ACA subsidy high net worth low income scenario thrives on a fundamental mismatch: the law’s income thresholds ignore asset-based wealth. A couple with a $2 million home but no other income might still qualify for subsidies if their MAGI—calculated after deductions—lands below 400% of the poverty line. This isn’t a bug; it’s a byproduct of how the ACA defines eligibility. The IRS treats primary residences as exempt assets for subsidy purposes, provided they’re not rented out or used for business. The problem arises when other income sources (rental properties, dividends, or even cryptocurrency sales) slip through cracks in reporting. Tax professionals exploit this by structuring income in ways that delay recognition—for example, deferring bonuses into the next tax year or using qualified business income (QBI) deductions to lower MAGI. The IRS has cracked down on offshore accounts and shell companies, but domestic strategies (like health savings account contributions) remain underutilized by those who could benefit. The result? A two-tiered system where liquid income triggers audits, but hidden wealth often doesn’t.The Context You Need
The ACA’s subsidy structure was built on a pre-2008 assumption: most wealth was tied to homeownership, not volatile markets. Today, passive income from stocks, real estate, or digital assets dominates for many high-net-worth households. The law’s 9.83% income cap for subsidies (above 400% FPL) means families earning $120,000 could pay less than half what a $150,000 earner does—even if their lifestyles are identical. This creates perverse incentives: why pay for a $1,200/month plan when a $300/month subsidy might be available with slight tax adjustments? The IRS’s Data Retrieval Tool (used to auto-populate tax returns) has reduced errors for W-2 earners, but self-employed and gig workers—a growing segment—often misreport income. A freelancer with $80,000 in cash tips might underreport by $20,000, qualifying for subsidies they wouldn’t otherwise. The agency’s Compliance Integrity Program prioritizes cases where income jumps 25%+ year-over-year, but static high-net-worth filers fly under the radar.The Mechanics
Subsidy eligibility hinges on three variables: MAGI, household size, and the second-lowest cost silver plan in your county. For a family of four in 2024, the 400% FPL threshold is ~$140,000. If your MAGI is $130,000 but your total assets exceed $5 million, you’re still eligible—unless the IRS suspects intentional underreporting. The key is timing: income recognized in December 2024 won’t affect 2024 subsidies, but a large January 2025 bonus could trigger a 90-day special enrollment period with higher premiums. Tax strategies to lower MAGI include: - Contributing to a health savings account (HSA) (reduces taxable income by up to $8,300 for families). - Deferring income via retirement accounts (401(k), IRA) or qualified business income deductions. - Claiming dependents—adding a college student to your return can drop MAGI enough to qualify for subsidies. The catch? The IRS matches ACA enrollment data with tax returns. If you claim a subsidy on Healthcare.gov but report $200,000 in income on your 1040, the system flags you. Advanced Premium Tax Credits (APTC) are reconciled at tax time—so overestimating savings can lead to repayment demands (though the law caps repayments at 100% of excess subsidies).Details That Change the Picture
Not all high-net-worth families face the same risks. Primary earners with W-2 jobs have clearer income trails, while self-employed professionals (doctors, lawyers, consultants) have more flexibility. A physician with $300,000 in practice income might structure payments via an S-corp to lower MAGI, but an investor with $200,000 in capital gains has fewer levers—unless they harvest losses or use donor-advised funds to offset gains. The state exchange factor matters. California’s Covered California has stricter income verification than Healthcare.gov, while Washington’s exchange automatically enrolls eligible residents—sometimes without proper income checks. A 2023 ProPublica investigation found that 1 in 5 subsidy recipients in some states lacked verification documents, though most were never audited."Subsidies aren’t just for the poor—they’re for people who can game the system’s blind spots. The IRS doesn’t have the resources to audit every millionaire with a side hustle. That’s why tax planners focus on paper income vs. real cash flow." — Former IRS Examiner (anonymized)
| Scenario | Risk Level |
|---|---|
| W-2 employee with rental income underreported | Moderate (IRS matches 1099s to bank records) |
| Self-employed freelancer using cash transactions | High (IRS uses Bank Secrecy Act data) |
| Trust distributions not reported as income | Critical (IRS Form 3520 audits) |
| Married couple filing separately to split subsidies | Extreme (IRS marriage penalty rules apply) |
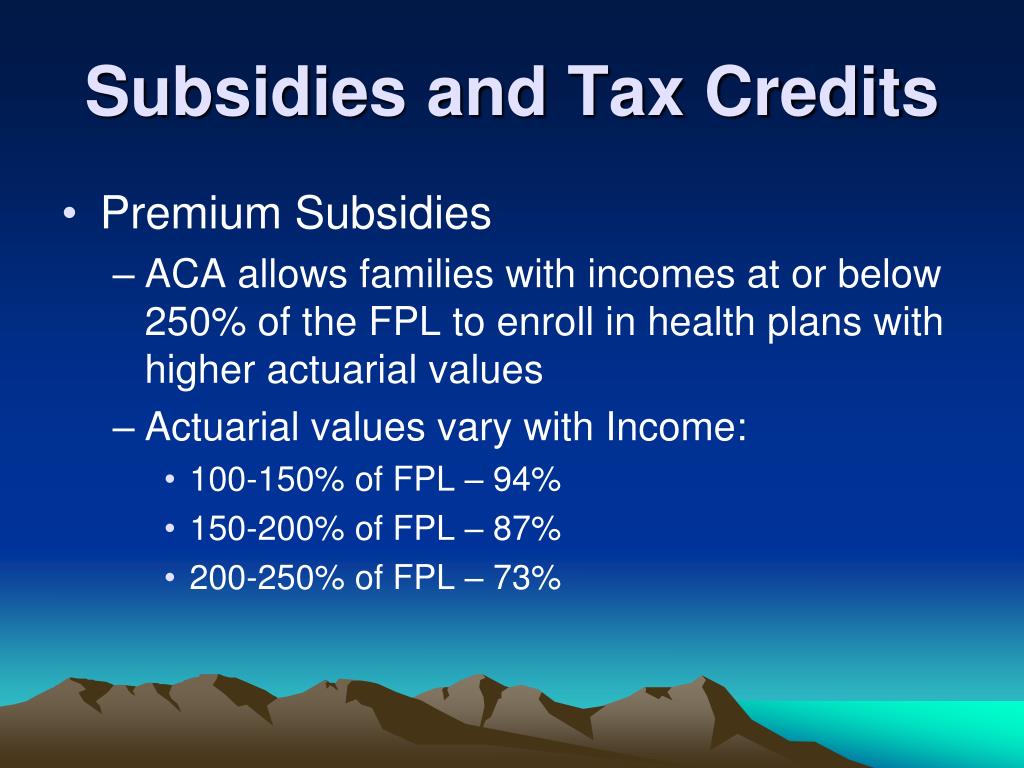
Conclusion
The ACA subsidy high net worth low income paradox isn’t a flaw—it’s a feature of a law designed for a pre-digital economy. High-net-worth families who understand MAGI manipulation, asset shielding, and state exchange quirks can legally access savings they’d otherwise miss. But the IRS’s increased use of AI for fraud detection (like Document Comparison System) means the window for exploitation is narrowing. For most, the risk isn’t worth the reward—but for those who navigate it carefully, the payoff can be six figures in lifetime savings. The bigger question is whether the ACA’s subsidy structure should adapt. As wealth inequality grows, the current system subsidizes the rich while penalizing the middle class—a contradiction that policymakers have yet to address. Until then, the ACA subsidy high net worth low income loophole will remain a high-stakes game of financial chess.Comprehensive FAQs
Q: Can I qualify for ACA subsidies if I own a home but have no other income?
A: Yes, provided your MAGI is below 400% of the federal poverty level. Primary residences are excluded from asset tests for subsidy purposes, but rental income or home equity loans (if used for non-mortgage purposes) may count. The IRS focuses on reported income, not net worth.
Q: What happens if the IRS audits me after I’ve received subsidies?
A: You’ll owe back premiums, taxes, and a 20% penalty on underreported income. The IRS often resolves cases via offer in compromise (settlements) if you can prove reasonable cause. However, intentional misrepresentation can lead to fraud charges, with penalties up to 75% of the subsidy amount.
Q: Are there safer ways to access ACA subsidies for high earners?
A: Yes. Legal strategies include:
- Maximizing HSA contributions ($8,300 for families in 2024).
- Using QBI deductions (up to 20% of business income).
- Deferring bonuses or capital gains to the next tax year.
- Exploring state-specific programs (e.g., California’s Medi-Cal for high earners in certain counties).
Q: Do states with their own exchanges (like NY or CA) have stricter rules?
A: Generally, yes. State-run exchanges (e.g., Covered California, NY State of Health) conduct pre-enrollment income verification, while Healthcare.gov relies on post-enrollment reconciliation. Some states (like Massachusetts) have income caps below the federal 400% FPL, making subsidies harder to obtain. Always check your state’s specific eligibility rules before applying.
Q: What’s the most common red flag that triggers an IRS audit?
A: Income discrepancies—for example:
- Large cash deposits not matched to 1099s or W-2s.
- Sudden spikes in reported income (e.g., a freelancer jumping from $50K to $150K).
- Missing or inconsistent documentation (e.g., no records for rental income).
- Married couples filing separately when one spouse has high income.
