
Breaking Down the Numbers
The 2022 Survey of Consumer Finances net worth percentiles table serves as a financial X-ray, exposing how wealth is distributed across the population. Median net worth—the value separating the top half from the bottom half—stood at $120,400 for all households, but this figure obscures vast regional and demographic variations. In urban centers like New York or San Francisco, the median could exceed $250,000, while in rural Appalachia or parts of the Deep South, it might not reach $20,000. The top 1% of households, meanwhile, held a median net worth of $17.1 million, a figure so stratospheric it distorts perceptions of what “average” wealth even means. The table also highlighted how home equity accounted for nearly 40% of total net worth for the top decile, compared to just 10% for the bottom 50%, revealing how property ownership remains the single most powerful wealth-building tool in the U.S. The data’s most striking feature was the persistent racial wealth gap. Black and Hispanic households had median net worths of $24,100 and $36,900, respectively, compared to $188,200 for White households. This gap wasn’t static; it had grown since 2019, partly due to the pandemic’s disproportionate impact on minority communities and the subsequent asset price inflation that favored those already holding wealth. The table also showed that student debt was a major drag on younger households, with borrowers under 35 seeing their net worth suppressed by $40,000 on average compared to non-borrowers. These patterns suggested that traditional pathways to wealth—education, homeownership, and stock market participation—were increasingly inaccessible to large segments of the population.The Verified Baseline
The Federal Reserve’s Survey of Consumer Finances is conducted every three years, with the 2022 iteration based on responses from 6,018 households nationwide. The net worth percentiles table is derived from self-reported data on assets (including cash, stocks, real estate, and retirement accounts) and liabilities (mortgages, student loans, credit card debt). While the survey is the most comprehensive snapshot of U.S. household finances, it has limitations: underreporting of assets, especially among high-net-worth individuals, and the exclusion of certain wealth forms like non-liquid assets or trusts. Despite these caveats, the 2022 data confirmed long-standing trends. For instance, the top 10% of households held 67.1% of all liquid assets, a figure that had remained relatively stable over the past decade. Meanwhile, the bottom 50% saw their share of liquid assets shrink from 3.1% in 2019 to 2.6% in 2022, a decline attributed to rising costs, stagnant wages, and the erosion of defined-benefit pensions. The racial wealth divide was equally well-documented. The median net worth of White households was $188,200, while Black households lagged at $24,100—a gap that had persisted for decades despite economic growth. The data also showed that homeownership rates remained a critical factor: 71.5% of White households owned their homes, compared to 44.5% of Black households and 49.2% of Hispanic households. This disparity wasn’t just about access to mortgages; it reflected historical redlining, discriminatory lending practices, and the intergenerational transfer of wealth through inherited property. The table’s findings were consistent with other studies, such as the Federal Reserve’s own research on racial gaps, reinforcing its credibility as a benchmark for economic inequality.What the Estimates Suggest
Beyond the verified data, estimates derived from the Survey of Consumer Finances net worth percentiles table paint a more nuanced picture of financial stress. Analysts suggest that underlying debt burdens—particularly medical debt and credit card balances—are higher than reported, as many households may have omitted these liabilities. For example, delinquent debt is estimated to have risen by 15-20% among low-income households since 2019, though the SCF doesn’t capture this directly. Additionally, the shadow wealth held in non-liquid assets (such as small business equity or illiquid real estate) could add $5 trillion to $10 trillion to the total net worth figures, though this remains speculative. The table’s implications for retirement security are also concerning: 40% of households near retirement age had less than $50,000 in retirement savings, a figure that aligns with estimates of insufficient preparedness for an aging population. Economists also point to regional disparities that the table doesn’t fully capture. In states like Texas or Florida, where asset prices surged post-pandemic, median net worth may have overstated financial stability, as many households were highly leveraged in real estate. Conversely, in Rust Belt states, depreciating home values and job market declines could have understated the true financial strain. The estimates further suggest that younger generations—particularly Millennials—are facing structural headwinds: student debt, delayed homeownership, and lower wage growth relative to inflation. While the SCF’s net worth percentiles table shows that the median net worth for households headed by someone under 35 was just $7,800, private research indicates that liquidity crises (such as unexpected medical bills or car repairs) are pushing many into debt spirals not reflected in the data.
Case Study: A Closer Look
Consider the experience of a 32-year-old Black homeowner in Atlanta with a $150,000 mortgage and $40,000 in student debt. According to the Survey of Consumer Finances net worth percentiles table, her net worth would likely place her in the 25th percentile—well below the median—but her home equity (estimated at $80,000) is a critical asset. However, rising interest rates in 2022-2023 have increased her monthly payment by $300, straining her budget. Meanwhile, her 401(k) balance—reportedly $25,000—lags behind peers due to lower wage growth in her industry. This case illustrates how asset ownership doesn’t equate to financial security when liabilities rise faster than income. The table’s percentiles don’t account for monthly cash flow challenges, which are often more pressing than static net worth figures. The Federal Reserve’s data also highlights how policy interventions—such as the First-Time Homebuyer Tax Credit or student debt relief proposals—could shift these percentiles. For instance, if student debt were forgiven for borrowers under $125,000 in income, the bottom 40% of households could see their net worth increase by an estimated 10-15%, according to Brookings Institution estimates. However, the Survey of Consumer Finances net worth percentiles table doesn’t project such scenarios; it only reflects current distributions. The Atlanta homeowner’s story underscores a broader truth: wealth percentiles are static snapshots, but financial resilience depends on dynamic factors like job stability, healthcare access, and policy support.“The net worth gap isn’t just about how much you earn—it’s about who you know, where you live, and whether your family had the chance to build wealth before you.” — Darrick Hamilton, economist and professor at The New School
| Factor | Estimated Impact on Net Worth Percentile |
|---|---|
| Student debt forgiveness (under $125k income) | +10-15% for bottom 40% households |
| Homeownership rate increase (from 44.5% to 55%) | +20-25% for Black households over 10 years |
| Rising interest rates (2022-2023) | -5-10% liquidity for highly leveraged homeowners |
| Inheritance of $50k+ from family | +30-40% percentile jump for recipient households |
What This Means Going Forward
The Survey of Consumer Finances net worth percentiles table for 2022 serves as both a diagnostic tool and a warning sign. For policymakers, it confirms that traditional wealth-building strategies—homeownership, stock market participation, and retirement savings—are no longer sufficient for broad-based prosperity. The data suggests that direct wealth transfers, such as baby bonds or reparations discussions, may be necessary to close gaps that have persisted for generations. Meanwhile, for financial planners, the table reinforces the need to diversify asset portfolios beyond traditional stocks and bonds, particularly for clients in lower percentiles where liquidity shocks can derail long-term stability. The implications for economic mobility are equally stark. If current trends continue, the top 1% will hold an even larger share of wealth, while the bottom 50% will see their percentiles stagnate or decline. This could lead to political and social unrest, as seen in other nations where wealth inequality has fueled populist movements. The table doesn’t just reflect economic conditions—it predicts potential futures. Without intervention, the intergenerational transfer of wealth will continue to favor those who already benefit from historical advantages, deepening divisions that extend beyond finances into healthcare access, education quality, and political influence.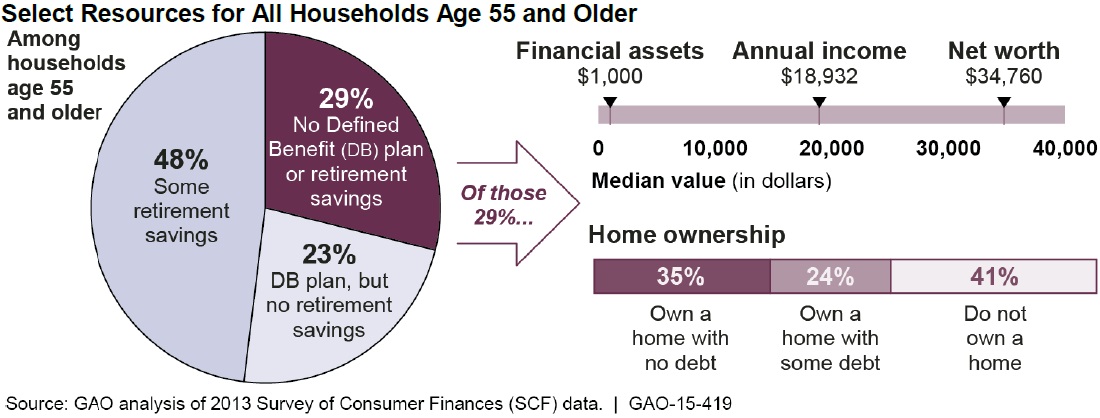
Conclusion
The 2022 Survey of Consumer Finances net worth percentiles table isn’t just a dataset—it’s a mirror held up to American society, revealing how wealth is concentrated, who benefits from economic growth, and who is left behind. The numbers tell a story of systemic advantage and disadvantage, where race, geography, and family background determine financial outcomes far more than individual effort. For economists, the table is a call to action; for policymakers, it’s a roadmap for reform; and for ordinary citizens, it’s a reality check on the challenges of building security in an unequal economy. The data won’t change overnight, but it should change priorities. Whether through expanded homeownership programs, student debt relief, or wealth-building incentives, the table provides a clear benchmark for progress. Ignoring it risks entrenching inequality, while addressing it could reshape the financial landscape for generations to come.Comprehensive FAQs
Q: How often is the Survey of Consumer Finances conducted?
The Federal Reserve’s Survey of Consumer Finances is typically released every three years, with the most recent data covering 2022. The next expected release will likely be in 2025, based on the 2025 survey cycle.
Q: What’s the difference between median and mean net worth in the SCF?
The median net worth (the middle value when all households are ranked) is $120,400, while the mean net worth (the average) is inflated by ultra-high-net-worth individuals, sitting around $1.9 million. The median is a better indicator of typical household wealth.
Q: How does the racial wealth gap compare to past SCF reports?
The 2022 gap—where White households had $188,200 in median net worth compared to $24,100 for Black households—is broadly consistent with past reports, though the absolute gap has widened due to post-pandemic asset inflation favoring those already wealthy.
Q: Can I access the full 2022 SCF net worth percentiles table?
Yes, the full dataset is available on the Federal Reserve’s Board of Governors website, where you can download the Survey of Consumer Finances net worth percentiles table along with other financial metrics.
Q: How does homeownership affect net worth percentiles?
Homeownership is the single largest driver of wealth accumulation, accounting for nearly 40% of net worth for the top decile but only 10% for the bottom 50%. Policies like down payment assistance or predatory lending reforms could shift these percentiles significantly.
Q: What’s the biggest misconception about the SCF data?
Many assume the net worth percentiles table reflects current liquidity, but it doesn’t account for monthly cash flow challenges, debt burdens, or non-liquid assets. A household could have a high net worth on paper but still struggle with day-to-day expenses.
Q: How does student debt impact net worth percentiles?
Households with student debt have median net worths 40% lower than non-borrowers. For those under 35, student loans suppress net worth by an estimated $40,000, pushing them into lower percentiles even if they earn middle-class incomes.
Q: What policy changes could improve net worth percentiles for low-income households?
Potential solutions include:
- Baby bonds (government-funded savings accounts for children)
- Expanded homeownership programs (e.g., down payment assistance)
- Student debt relief (targeted at low-income borrowers)
- Wealth-building incentives (e.g., tax credits for retirement savings)
