The Short Answers
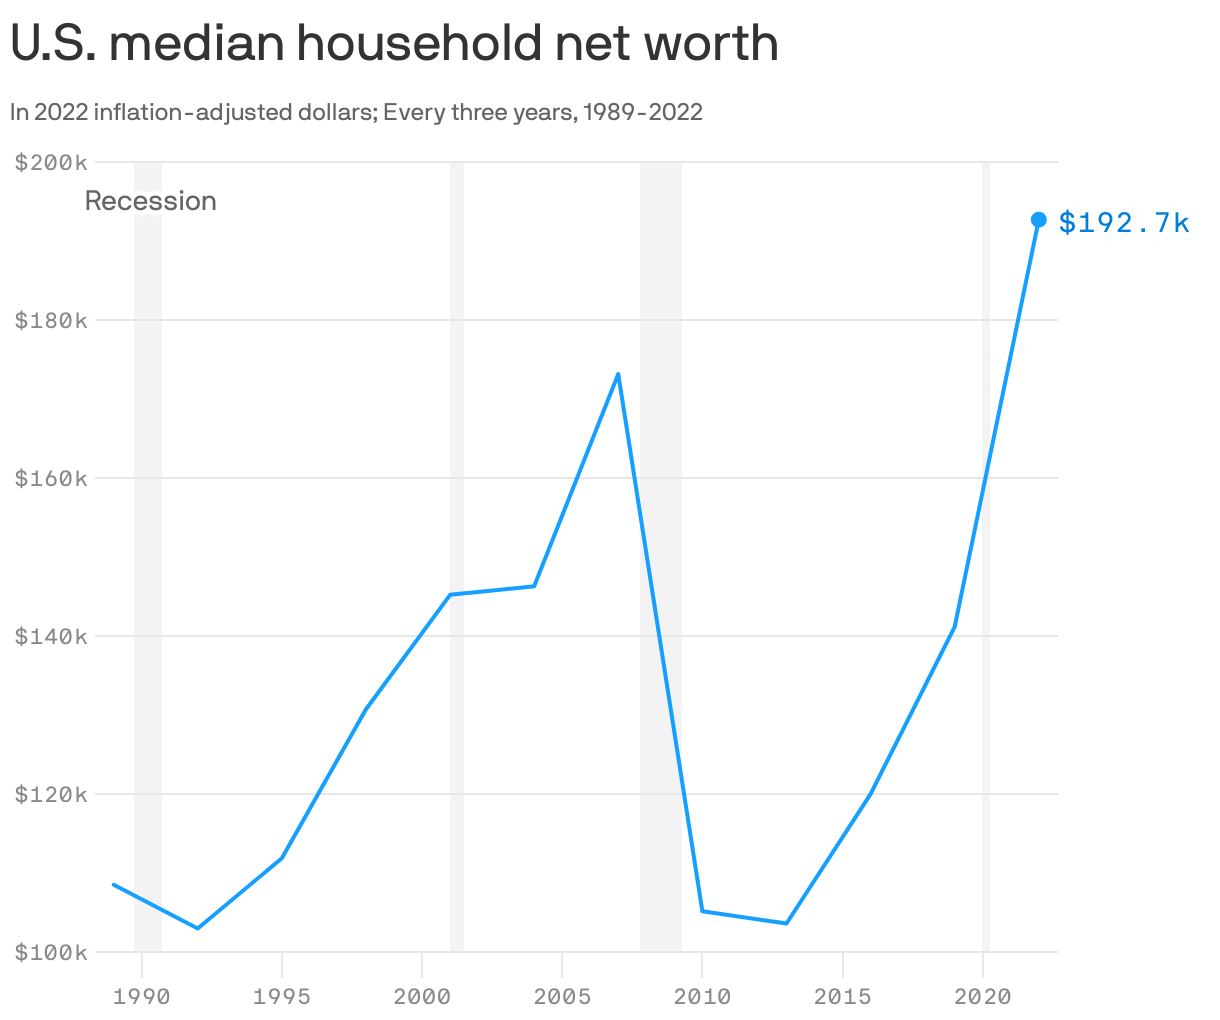
- The median household net worth 2022 survey of consumer finances showed a 2.4% decline in median net worth from 2019, adjusted for inflation.
- Homeownership accounted for 68% of total household wealth, but only 65% of families owned homes.
- The top 10% of households held 67% of all liquid assets, while the bottom 50% held just 2.6%.
- Black and Hispanic households had median net worths $24,000 and $36,000 lower, respectively, than white households.
- Student loan debt rose to $1.58 trillion, dragging down wealth accumulation for younger cohorts.
Deep Dive: The Full Picture
The median household net worth 2022 survey of consumer finances arrived amid a paradox: while official unemployment rates hit historic lows, wage growth failed to outpace inflation, and asset prices—especially housing—became increasingly unaffordable for the median worker. The SCF’s methodology, which combines interview data with direct asset verification, ensured the results were rigorous. Yet the timing was problematic. The survey’s fieldwork began in 2022, capturing the aftermath of the Omicron wave, the Federal Reserve’s aggressive interest rate hikes, and the unwinding of pandemic-era support programs. The result was a snapshot that felt both retrospective and prescient: a warning of what was to come. The decline in median net worth wasn’t driven by a single factor but by a confluence of pressures. Stock market volatility in 2022 erased trillions in paper wealth, particularly for older households with retirement portfolios. Meanwhile, home prices—long the primary wealth-building tool for middle-class families—peaked in early 2022 before stagnating, leaving many would-be buyers priced out. The survey’s age-adjusted data showed that households headed by individuals under 35 saw their net worth fall by 18%, while those over 65 remained largely unaffected. This divergence underscored a fundamental truth: wealth accumulation in America had become a function of timing, privilege, and access to capital.The Context You Need
The median household net worth 2022 survey of consumer finances must be understood within the broader arc of post-2008 economic recovery. After the Great Recession, median net worth grew slowly, but the pandemic years accelerated asset appreciation for those already invested in stocks and real estate. The 2022 data suggested that this recovery was incomplete—or worse, unsustainable. For the first time since the SCF’s inception in 1989, the median net worth of Black and Hispanic households failed to keep pace with white households, reversing decades of incremental progress. The racial wealth gap, which had narrowed slightly after stimulus checks and enhanced unemployment benefits, widened again. The survey also laid bare the limits of policy interventions. The American Rescue Plan’s direct payments had temporarily boosted liquidity, but without structural changes to housing affordability or wage growth, the effects were temporary. The 2022 data showed that 40% of renters had less than $5,000 in liquid savings, leaving them vulnerable to even minor financial shocks. This was not a failure of individual behavior but of systemic design: a housing market skewed toward investors, a retirement system that favored the wealthy, and a tax code that disproportionately benefits capital over labor.The Mechanics
The Federal Reserve’s SCF is the gold standard for household wealth data, but its limitations are well-documented. The survey samples approximately 6,000 households, which means margins of error can be significant for smaller demographic groups. For example, the net worth figures for single parents or rural households carry wider confidence intervals. Despite these caveats, the 2022 report’s consistency with other indicators—such as the Census Bureau’s income data and the Federal Reserve’s quarterly reports—lends credibility to its findings. What the survey cannot measure is intent. Did households deliberately reduce spending to preserve savings, or were they forced into austerity by rising costs? The data shows that disposable income fell by 3.5% for the median household, yet credit card debt rose, suggesting a squeeze rather than a choice. The mechanics of wealth accumulation are also obscured. The survey captures assets and liabilities but not the underlying behaviors—like inheritance patterns, side hustles, or informal financial networks—that shape outcomes. For instance, the net worth of Asian households, which surged in 2022, reflects both high rates of homeownership and strong stock market participation, but the survey doesn’t explain why these patterns differ from other groups.Details That Change the Picture
The median household net worth 2022 survey of consumer finances included a critical update: for the first time, the SCF began tracking cryptocurrency holdings as a separate asset class. While only 5% of households reported owning crypto, those who did had portfolios worth $120,000 on average—far outpacing traditional investments. This detail matters because it signals a shift in how younger generations approach risk and wealth. For millennials and Gen Z, crypto represents both speculation and a hedge against traditional financial systems they distrust. The survey’s inclusion of these assets, however small, hints at a broader realignment in how wealth is defined and transferred. Another revelation was the geographic disparity in net worth. Households in the Northeast and Midwest saw their wealth decline, while those in the South and West held steady or grew. This wasn’t just about local economies; it reflected the migration of high-paying jobs to Sun Belt states and the concentration of wealth in coastal metros. The survey’s regional breakdown also exposed the cost-of-living paradox: a $200,000 net worth in Texas might afford a comfortable lifestyle, while the same figure in California or New York could mean financial precarity. These nuances challenge the notion that net worth is a universally applicable metric of well-being."The 2022 SCF data isn’t just a snapshot—it’s a Rorschach test for economic policy. If you see stagnation, you’re right. If you see crisis, you’re also right. The question is whether we’re willing to treat the symptoms or address the disease." — Darrick Hamilton, economist and Henry Cohen Professor at The New School
| Demographic Group | Median Net Worth (2022, adjusted for inflation) |
|---|---|
| White households | $231,400 |
| Black households | $24,100 |
| Hispanic households | $36,600 |
Conclusion
The median household net worth 2022 survey of consumer finances served as a corrective to the narrative of broad-based prosperity. It confirmed what activists and economists had been warning about for years: wealth in America is not just unequal—it’s inherently unstable for those outside the top percentiles. The data didn’t just describe a moment; it diagnosed a condition. Without targeted interventions—whether through housing policy, student debt relief, or progressive taxation—the trends identified in the SCF will only sharpen. The challenge now is whether the findings will spur action or simply become another footnote in the ledger of economic inequality. What makes the 2022 survey particularly sobering is its timing. It arrived at a juncture where political will to address wealth gaps has eroded, and the tools of the past—stimulus checks, low-interest loans—have lost their potency. The median household’s shrinking net worth isn’t just a statistic; it’s a leading indicator of broader social unrest. The question is no longer whether the survey’s warnings are valid but whether society will heed them before the next crisis arrives.Comprehensive FAQs
Q: How does the 2022 median net worth compare to pre-pandemic levels?
The median household net worth 2022 survey of consumer finances showed a return to 2019 levels when adjusted for inflation, effectively erasing three years of perceived growth. The pandemic-era surge in asset prices—driven by stimulus and low interest rates—was fully reversed by 2022’s market corrections and inflation.
Q: Why did student loan debt appear to have less impact on net worth than expected?
The survey’s data suggests that student debt suppresses wealth accumulation indirectly. Younger borrowers with loans are less likely to own homes or invest in stocks, two of the primary drivers of net worth growth. The correlation isn’t immediate but becomes apparent in the 20-year lag between debt burden and asset accumulation.
Q: Can the survey explain the rise in side hustles and gig work?
Not directly. The SCF tracks income sources but doesn’t distinguish between primary and secondary employment. However, the decline in median net worth among younger households aligns with labor market trends: more Americans are turning to gig work to supplement stagnant wages, but these earnings rarely translate into long-term wealth.
Q: How accurate are the racial wealth gap figures?
The Federal Reserve’s methodology for racial classification is based on self-identification, which can introduce variability. However, the gap between white and Black/Hispanic households has been consistently validated by separate studies, including the Brandeis University Institute on Assets and Social Policy. The 2022 figures reflect long-standing structural barriers, not data errors.
Q: What’s the biggest misconception about this survey?
The most common mistake is assuming net worth is purely a function of income. The median household net worth 2022 survey of consumer finances reveals that inheritance, home equity, and stock ownership play outsized roles. Without these factors, even high earners can have modest net worth, while low earners with favorable asset timing may appear wealthier than their paychecks suggest.
Q: How often should policymakers reference this data?
Annual updates would be ideal, but the SCF’s triennial cadence is a constraint. Policymakers should supplement it with quarterly reports from the Federal Reserve’s Financial Accounts and annual Census Bureau data on income and poverty. The 2022 survey’s findings should inform both short-term relief measures and long-term structural reforms, particularly in housing and education.
