
The Short Answers
- The 04 of Us net worth percentiles refer to the top 4% of households by net worth, which collectively hold disproportionate wealth compared to the rest.
- These percentiles are calculated using Federal Reserve data, adjusted for inflation and household size, but debt levels skew the picture significantly.
- Breaking into the top 4% often requires a mix of high income, low debt, and asset ownership—real estate or investments—rather than just salary alone.
- Policy changes, like tax reforms or student debt relief, can temporarily shift these percentiles, but structural trends (homeownership rates, inheritance) dominate long-term shifts.
Deep Dive: The Full Picture
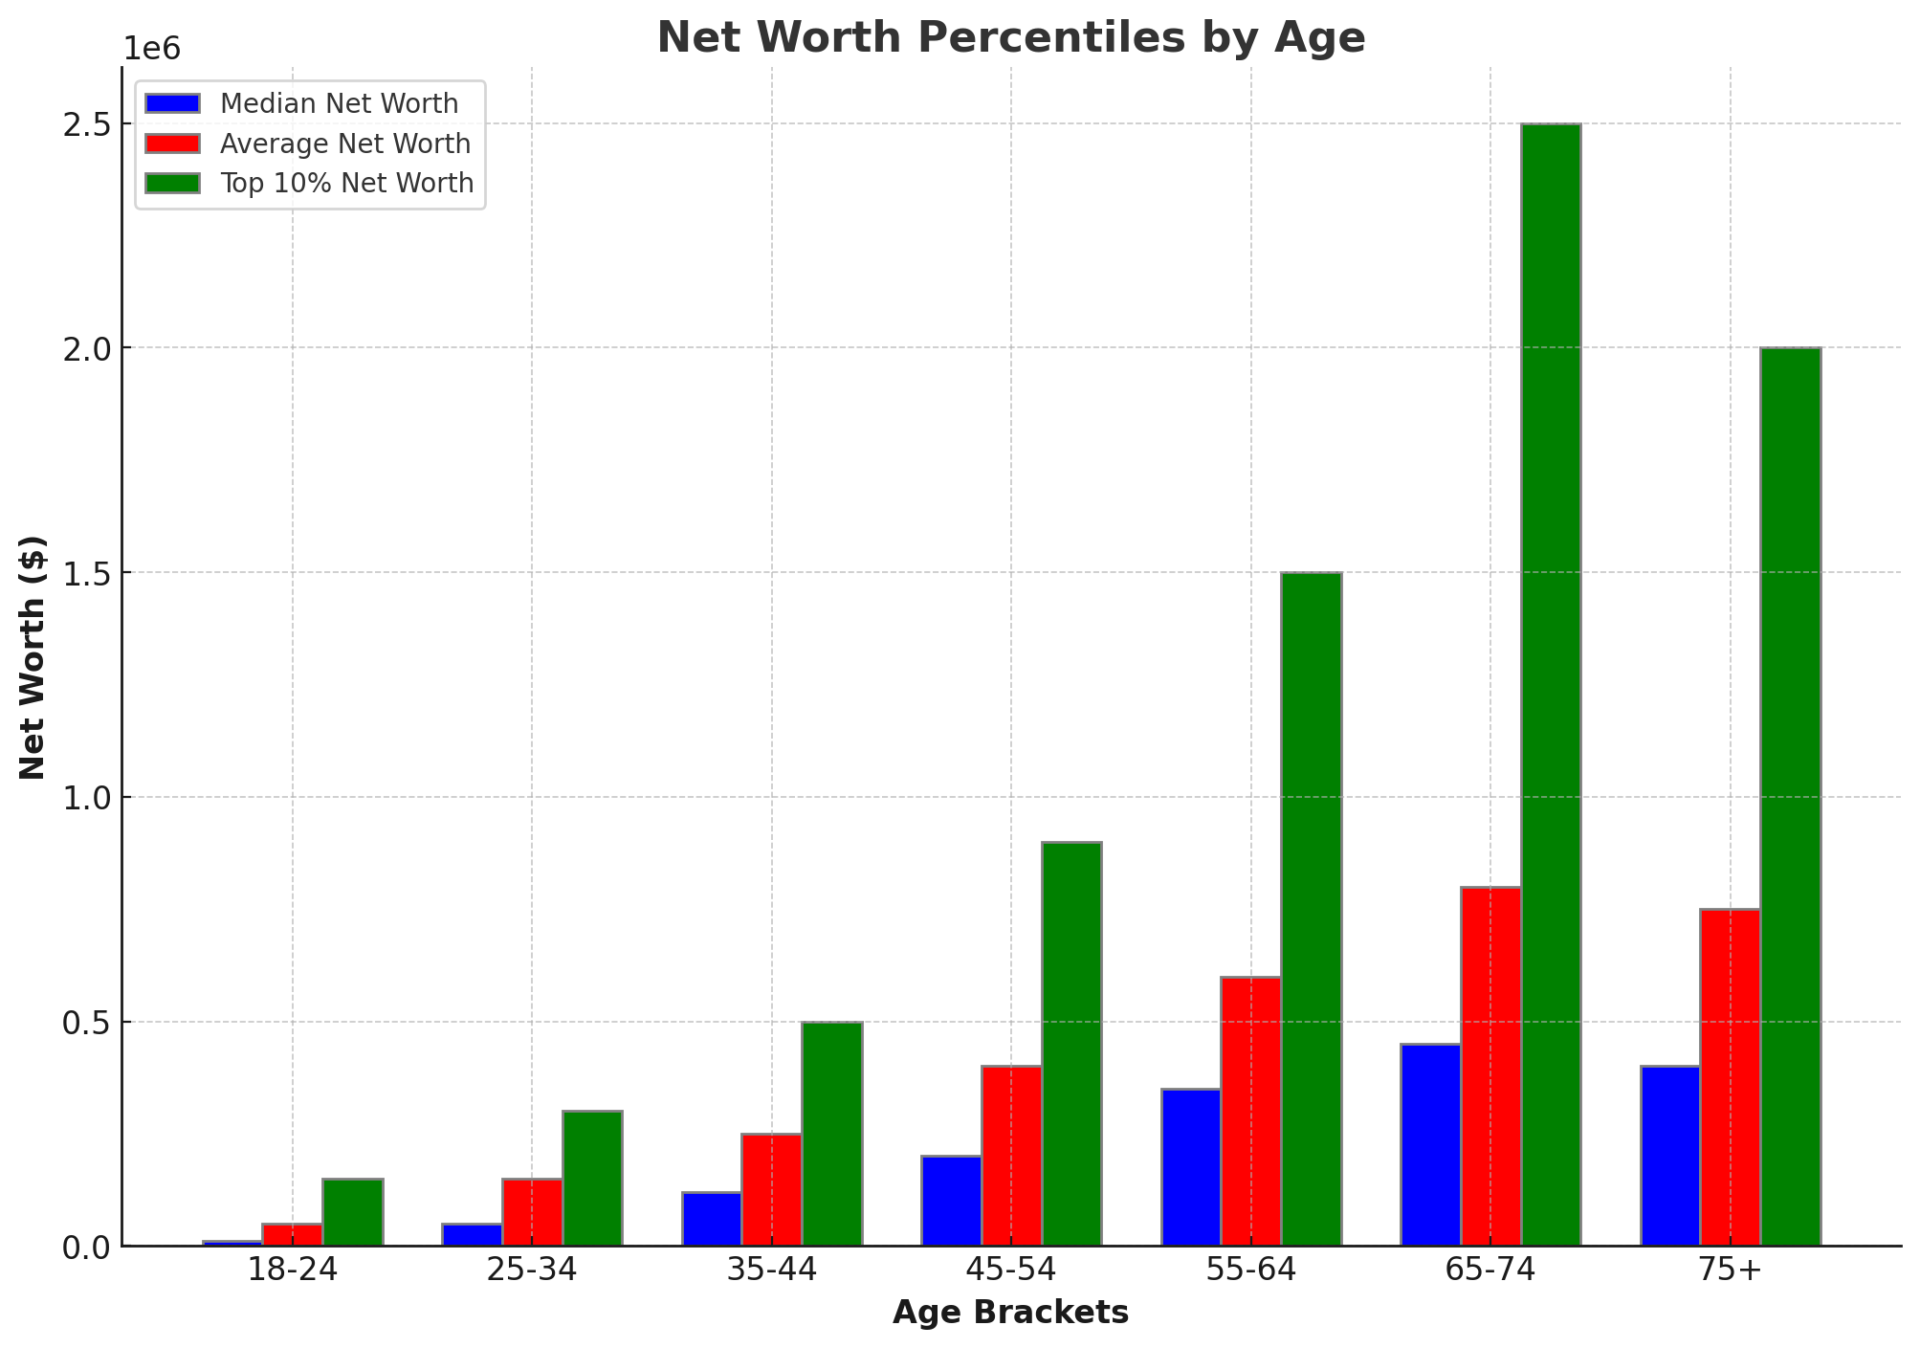
The 04 of Us net worth percentiles aren’t just about numbers—they’re a report card on economic mobility. In 2023, the median net worth for a household in the top 4% was estimated at $3.2 million, while the median for the bottom 50% hovered around $120,000. That gap isn’t just about money; it’s about generational wealth traps. A family in the bottom half needs roughly 26 years of median income to reach the median net worth of the top 4%. For renters or those with high debt, that timeline stretches to 40 years or more. The mechanics of these percentiles are less about raw income and more about asset accumulation. The top 4% aren’t just high earners—they’re asset-owners. Home equity, retirement accounts, and business stakes make up the bulk of their wealth. Meanwhile, the bottom 96% rely on liquidity (cash, checking accounts) and depreciating assets (cars, furniture). This divide explains why wealth inequality persists even as income inequality fluctuates. A nurse earning $90,000 might save aggressively but still never crack the top 4% if they lack access to homeownership or investment opportunities.The Context You Need
Understanding the 04 of Us net worth percentiles requires unpacking two myths: 1) that wealth is just a function of income, and 2) that the top 1% are the only ones who matter. The reality is that the 4%-to-10% bracket—often called the "new elite"—wields outsized influence. These households don’t just have money; they control intergenerational transfer vehicles like trusts, family LLCs, and private equity stakes. Their decisions ripple through local economies, from real estate bubbles to small-business lending. The percentiles also reflect policy lag. Programs like the Earned Income Tax Credit (EITC) or first-time homebuyer incentives can nudge households toward the top 4%, but their effects are temporary. Without structural changes—like reducing student debt or expanding inheritance tax exemptions—the percentiles will keep widening. The 2008 financial crisis, for example, wiped out $16 trillion in household wealth, but the top 4% recovered within six years. The bottom 90%? Not until 2019.The Mechanics
The Federal Reserve’s Survey of Consumer Finances is the gold standard for tracking these percentiles, but the data has limitations. For one, it undercounts illiquid assets like family farms or closely held businesses. For another, it doesn’t account for offshore wealth or trusts, which can hide assets from public view. That’s why estimates for the top 4% often vary—some studies place the threshold at $2.5 million, others at $4 million, depending on methodology. Debt is the wild card. A household with $5 million in assets but $4 million in mortgage debt might still sit in the 75th percentile, while a couple with $1 million in cash and no liabilities could leap into the top 4%. This explains why homeownership rates are the single biggest predictor of net worth percentiles. Owners in the top 4% have median home values 10x higher than renters in the same bracket. The math is brutal: Renting keeps you in the bottom 96%.Details That Change the Picture
The 04 of Us net worth percentiles aren’t static—they contract and expand with economic cycles. During the dot-com boom, tech workers in their 30s could crack the top 4% on stock options alone. Today, that same feat requires multiple income streams (salary, dividends, rental income) due to higher valuations. The percentiles also vary by region. In San Francisco or New York, the threshold to enter the top 4% is $5 million+ because housing costs inflate asset bases. In Midwest cities, $2 million might suffice. What’s often missed is how inheritance and marriage distort these numbers. A 30-year-old inheriting $1 million from a trust could instantly join the top 4%, while a 50-year-old earning $200,000 might never qualify. Similarly, couples who combine assets see a compounding effect—two mid-tier earners can become high-net-worth individuals overnight. This explains why divorce rates spike among households near the 4% threshold: the math of splitting assets can drop them into the 80th percentile."Wealth isn’t just about what you earn; it’s about what you own and what you pass down. The 04 of Us percentiles are less about income and more about the rules of the game—who gets to play and who gets left at the gate." — Edward N. Wolff, Professor of Economics at NYU
| Percentile Bracket | Median Net Worth (2023 Estimates) |
|---|---|
| Top 1% | $17.1 million+ |
| 4%-10% | $2.5M–$10M |
| Bottom 50% | $120,000 or less |
Conclusion
The 04 of Us net worth percentiles are a fracture line in modern economics. They separate those who can afford generational wealth from those who must scramble for financial stability. The data shows that breaking into this bracket isn’t just about earning more—it’s about owning assets, minimizing debt, and leveraging systemic advantages (like homeownership or inheritance). For policymakers, this means grappling with uncomfortable truths: taxing capital gains won’t close the gap if homeownership remains out of reach for millions. The real story, though, isn’t in the numbers but in the behavior they reveal. The top 4% don’t just have more—they think differently about risk, leverage, and legacy. They’re more likely to invest in private markets, use trusts to shield assets, and pass wealth to heirs before taxes hit. For the rest, the percentiles serve as a warning: wealth isn’t just a destination; it’s a system. And that system is rigged.Comprehensive FAQs
Q: How often are the 04 of Us net worth percentiles updated?
The Federal Reserve’s Survey of Consumer Finances, the primary source for these percentiles, is conducted every three years. Private estimates (like those from the Urban Institute) update annually but rely on modeling rather than direct surveys. For real-time tracking, analysts often use quarterly data on asset prices (stocks, real estate) and adjust for inflation.
Q: Can a single person realistically join the top 4% without inheriting wealth?
Yes, but it requires aggressive asset accumulation. A single earner would need to save $1.2 million+ in liquid assets (excluding home equity) while minimizing debt. Historically, this has been achievable through real estate flipping, high-growth equity stakes, or entrepreneurship—but the barriers are rising. Most who crack the top 4% do so by age 50+, after decades of compounding.
Q: Do the 04 of Us percentiles vary by country?
Absolutely. In Canada, the top 4% threshold is around $2.3 million CAD, while in Germany, it’s roughly €1.8 million. The U.S. has the widest gap between income and net worth percentiles due to its real estate-driven wealth system. Countries with stronger social safety nets (like Nordic nations) see lower concentration in the top 4%, but their median net worth percentiles are also far lower overall.
Q: How does student debt affect these percentiles?
Student debt is a net worth killer, especially for younger households. A graduate with $100,000 in loans may earn a six-figure salary but still sit in the 60th percentile by net worth. The top 4% rarely carry student debt—either because they inherited wealth to pay it off or avoided it entirely (e.g., attending public universities or skipping college). This is why student debt relief proposals often focus on the bottom 40%, not the top 4%.
Q: Are there industries where breaking into the top 4% is easier?
Yes. Tech, finance, and healthcare are the fastest tracks due to stock options, bonuses, and asset appreciation. A mid-level software engineer in Silicon Valley can hit the top 4% in 10 years if they hold equity. Conversely, blue-collar jobs (even high-paying ones like trucking or skilled trades) rarely crack the bracket without side assets (real estate, investments). The biggest outlier? Professional athletes and entertainers, who can leap into the top 4% on single-year earnings—only to drop out if they don’t diversify.
Q: How do divorce and remarriage impact these percentiles?
Divorce is a net worth reset button. Couples near the 4% threshold often see their combined assets halved after splits, dropping them into the 70th-80th percentiles. Remarriage can help recover, but asset division laws vary by state—some (like California) split community property, while others (like Texas) treat assets individually. The top 4% are far less likely to divorce than middle-class couples, partly because splitting $5M is less appealing than splitting $200K.
Q: What’s the most underrated strategy to move into the top 4%?
Homeownership + rental income. The top 4% aren’t just homeowners—they’re landlords. Owning a primary residence and generating rental cash flow (even from a single property) can double a household’s net worth trajectory. The math is simple: A $500K home with $200K equity + $10K/year in rental income compounds faster than most 401(k) plans. This is why real estate crowdfunding and BRRRR strategies (Buy, Rehab, Rent, Refinance, Repeat) are so popular among aspirational high-net-worth households.
Q: Will AI or automation change these percentiles?
Potentially—but not in the way most assume. AI won’t create wealth for the bottom 96%; it will concentrate it further. The top 4% already benefit from algorithm-driven investing, automated real estate flipping, and AI-powered business scaling. Meanwhile, gig workers and freelancers (who make up a growing share of the middle class) will see their liquid assets stagnate unless they find ways to monetize AI skills (e.g., consulting, content creation). The percentiles may widen if AI jobs pay well but don’t translate to asset ownership.
