7 Things Worth Knowing About Taxes Net Worth Percentages of Pie
Taxes don’t just reduce net worth—they recalibrate the entire financial ecosystem. The percentages shift based on income brackets, asset types, and geographic location, but the underlying principle remains: wealth retention is a game of subtraction before addition. Here’s what the numbers reveal.1. The Wealthy Pay in Proportion—but Not as You’d Expect
The top 1% might pay the highest dollar amounts in taxes, but their effective tax rates often hover around 20–30% of income—far below the marginal rates that scare headlines. The real cost comes from taxes net worth percentages of pie, where capital gains, dividends, and estate taxes eat into accumulated wealth rather than annual earnings. A tech founder with a $500 million net worth might see 30% of that pie vanish over a lifetime—not in one tax bill, but in incremental slices: 15% on long-term gains, 40% on carried interest, and another 40% on estate transfers (if unplanned). The pie shrinks silently, and the cuts are often invisible until it’s too late. The middle class, meanwhile, faces a different kind of pie shrinkage. Payroll taxes (Social Security, Medicare) take a flat 15.3% of earned income, while state and local taxes add another layer. For a family earning $150,000 annually, taxes net worth percentages of pie can exceed 30% of disposable income when factoring in property taxes, school levies, and sales taxes on necessities. The difference? The wealthy can shelter assets; the middle class often can’t.2. Capital Gains Taxes Are the Silent Wealth Killer
Most people focus on income taxes, but for investors, capital gains taxes are the stealthy eroder of net worth. The taxes net worth percentages of pie equation changes dramatically here: a 20% long-term capital gains rate on a $1 million portfolio means $200,000 disappears—not from a paycheck, but from the value of assets. Over decades, this compounds. An investor who consistently earns 7% annual returns but pays 20% in taxes effectively nets just 5.6%—a 20% reduction in the pie’s growth rate. Worse, unrealized gains (stocks that haven’t been sold) still face taxes at death, creating a "death tax" on paper wealth. The strategy to mitigate this? Tax-loss harvesting, holding investments long-term, or shifting assets into tax-advantaged accounts. But even then, the percentages of pie that taxes claim are non-negotiable. The IRS doesn’t care if your portfolio is up 50%—it takes its cut before you see the gain.3. Estate Taxes Redefine the Pie for Heirs
Estate taxes don’t just apply to the ultra-rich. With the federal exemption at $13.61 million per individual (as of 2024), many high-net-worth families still face state-level estate taxes, which can kick in at lower thresholds (e.g., $1 million in Massachusetts). The taxes net worth percentages of pie here are brutal: a 40% federal rate on amounts over the exemption means a $20 million estate could lose $2.8 million to taxes—before probate fees, legal costs, or appraisals. For family businesses or real estate, the pie isn’t just sliced; it’s often halved. What’s less discussed is the step-up in basis—a tax break that resets the cost basis of inherited assets to their market value at the time of death. Without proper planning, heirs can still face capital gains taxes on gains that accrued before the original owner’s death. The percentages of pie that disappear here aren’t always in the headlines, but they’re just as real.4. State Taxes Turn Location Into a Wealth Multiplier
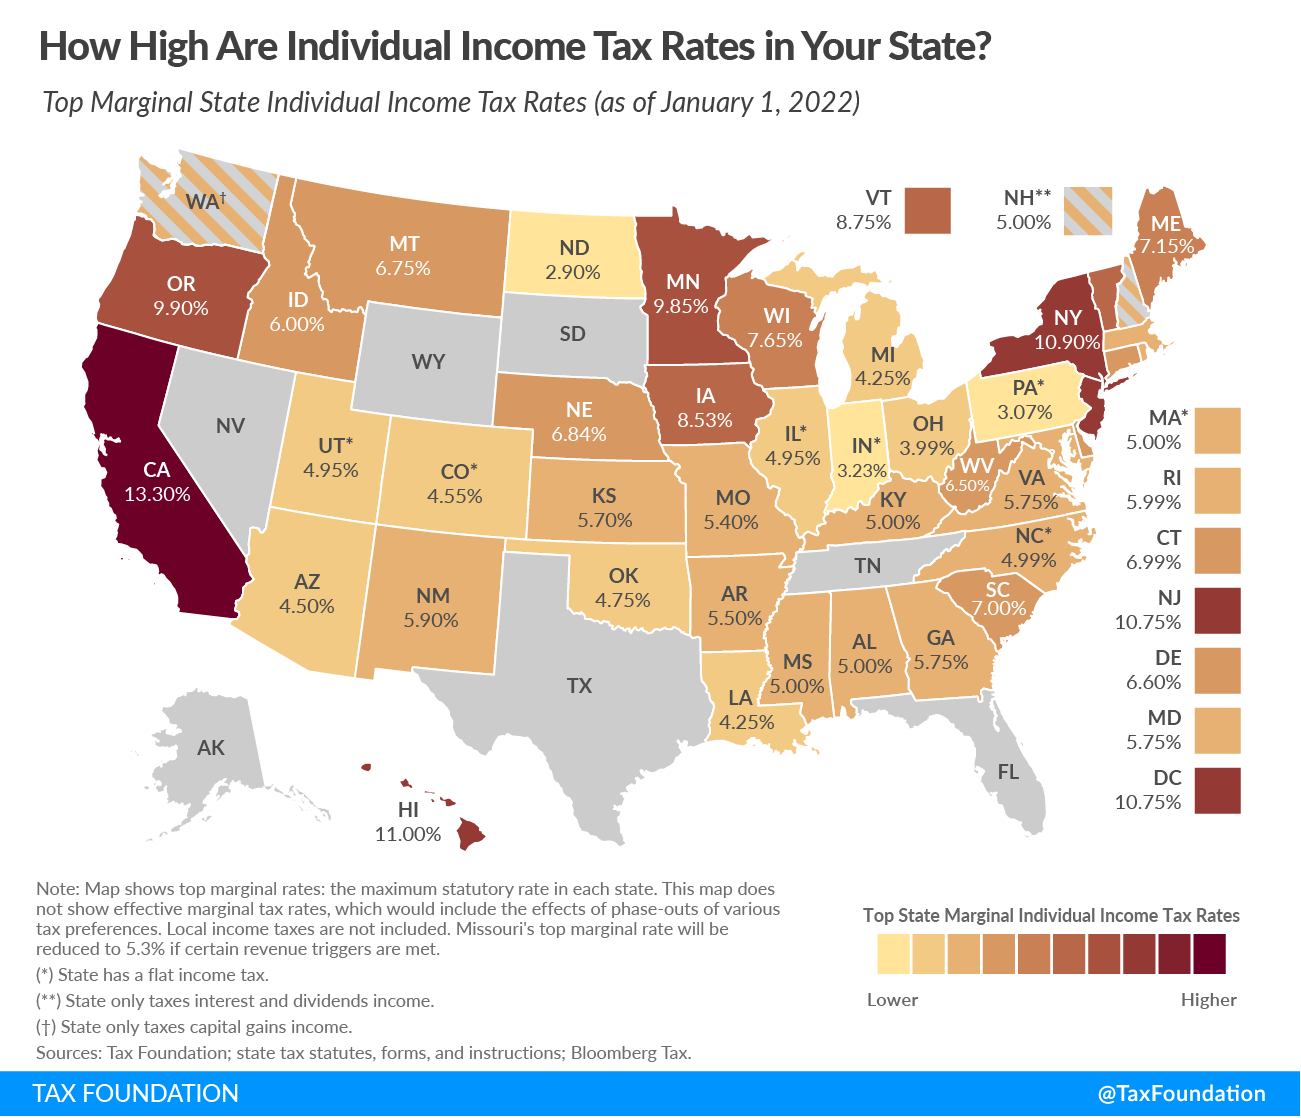
A $1 million net worth in Texas might feel like a $1.5 million pie in New York—after taxes. State income taxes, property taxes, and sales taxes vary wildly, and the taxes net worth percentages of pie can differ by 10% or more depending on where you live. Florida and Texas offer no state income tax, but their lack of services (e.g., public education funding) means higher local taxes elsewhere. California’s 13.3% top income tax rate, combined with high property taxes, can eat 20%+ of a high earner’s pie before federal taxes even touch it. The wealthy have long exploited this by structuring lives around low-tax states or offshore accounts. For everyone else, the choice is simpler: stay in a high-tax state and accept a smaller pie, or move and risk career or lifestyle trade-offs. The percentages of pie that taxes claim are a geographic lottery.5. The Middle Class Pays More in Hidden Taxes
While the rich debate capital gains, the middle class bleeds through sales taxes, payroll taxes, and regressive levies. A family spending $80,000 on groceries, housing, and healthcare might pay $10,000+ in sales and property taxes alone—taxes net worth percentages of pie that don’t appear on a W-2. Add in state income taxes (which hit middle earners harder than the wealthy due to deductions), and the total can exceed 30% of take-home pay. The wealthy can write off mortgages, business expenses, and charitable donations; the middle class often can’t. The result? The percentages of pie that remain after taxes are far thinner for a $100,000 income than for a $1 million income—even though the latter’s tax rate might be lower. It’s not about fairness; it’s about arithmetic.6. Taxes on Investments Aren’t Just About the Numbers
A 15% long-term capital gains rate sounds manageable, but the taxes net worth percentages of pie become clearer when you consider opportunity cost. Every dollar paid in taxes is a dollar not reinvested, compounded, or deployed. Over 30 years, a $100,000 investment at 7% annual returns would grow to $761,000—before taxes. After a 20% capital gains rate on withdrawals, the pie shrinks to $608,000. The difference isn’t just $153,000; it’s the percentage of pie that taxes prevent from being passed to heirs, used for education, or spent on legacy projects. The wealthy mitigate this with trusts, private equity, and tax-advantaged structures. The rest? They’re left with the raw numbers."Taxes are the price of civilization," said John F. Kennedy, "but they’re also the silent partner in your net worth statement." The problem isn’t the taxes themselves—it’s that most people don’t see them as part of the pie until it’s already been sliced."
7. The Pie Isn’t Static—It’s a Moving Target
Tax laws change. Brackets shift. New deductions appear and vanish. The taxes net worth percentages of pie you face today might not apply tomorrow. The 2017 Tax Cuts and Jobs Act, for example, doubled the estate tax exemption—but only temporarily. In 2025, the exemption is set to revert to pre-2018 levels, meaning estates over $6 million (per individual) could face a 40% tax again. For families with concentrated wealth in real estate or private businesses, the pie’s percentages could swing dramatically overnight. The lesson? Financial planning isn’t a one-time calculation. It’s a dynamic process of tracking how taxes net worth percentages of pie evolve with legislation, market conditions, and personal circumstances. Ignore this, and the pie shrinks faster than you realize.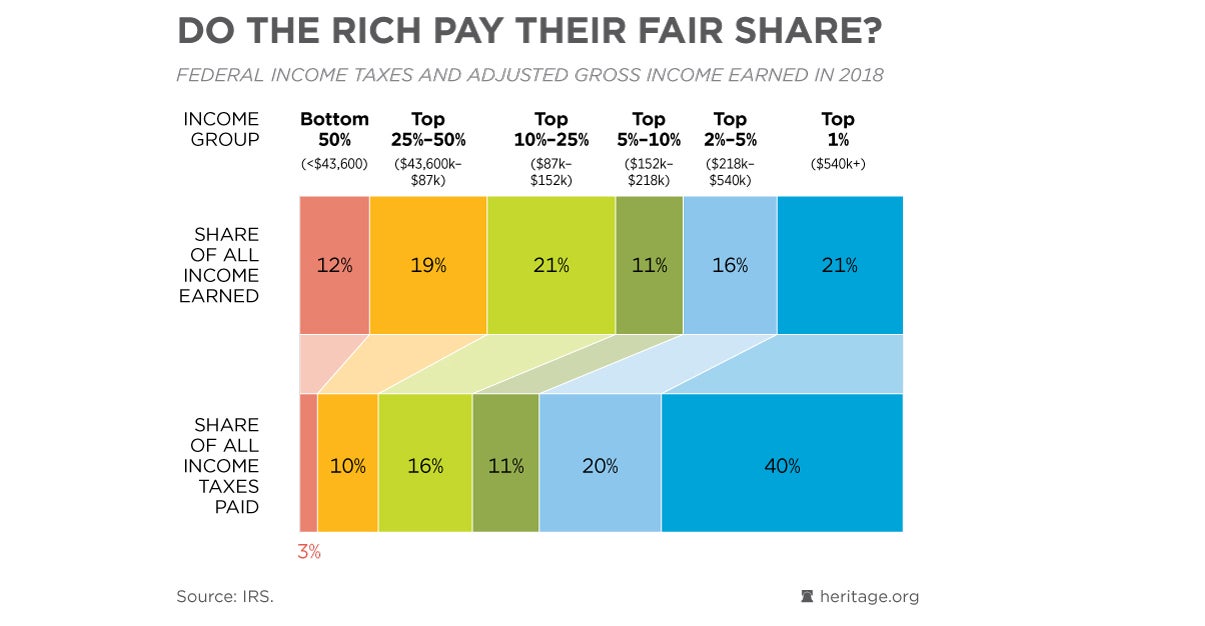
How These Facts Connect
The numbers tell a story: taxes don’t just reduce net worth—they reconfigure the entire financial landscape. The wealthy and the middle class face different battles, but both lose ground to the same structural forces. The ultra-rich can shelter assets, defer taxes, and exploit loopholes, but even they can’t escape the taxes net worth percentages of pie math. A billionaire might pay a lower effective rate than a doctor, but the absolute dollar amounts ensure the pie is still sliced. Meanwhile, the middle class is caught in a cycle where hidden taxes on consumption and housing eat into savings before they’re ever invested. The bigger picture? Wealth retention is less about how much you earn and more about how much you preserve. The percentages of pie that taxes claim aren’t just a line item—they’re the difference between generational wealth and a lifetime of financial maintenance.| Key Factor | Wealthy Impact | Middle Class Impact | Long-Term Effect |
|---|---|---|---|
| Capital Gains Taxes | 20–30% of unrealized gains | 15% on investments (if applicable) | Reduced compounding over decades |
| Estate Taxes | 40% on amounts over $13.61M | State taxes on smaller estates | Forced asset liquidation to pay taxes |
| State Taxes | 0–13% income tax + high property taxes | Sales taxes (6–10%) + payroll taxes | Location-based wealth erosion |
| Opportunity Cost | Taxes on $10M = $2M+ lost to reinvestment | Taxes on $50K income = $10K+ lost to savings | Slower wealth accumulation |
Conclusion
Understanding taxes net worth percentages of pie isn’t about avoiding taxes—it’s about recognizing that they’re an inevitable part of wealth management. The wealthy have the tools to minimize the damage; the middle class often doesn’t. But the principle remains: taxes don’t just take money—they reshape what’s left of your financial future. The key isn’t to eliminate taxes (impossible) but to see them as part of the pie from the start, not an afterthought. The numbers don’t lie. They just tell a story most people prefer to ignore—until it’s too late.Comprehensive FAQs
Q: How do capital gains taxes affect my net worth over time?
A: Capital gains taxes reduce your taxes net worth percentages of pie by effectively lowering your investment returns. For example, a 20% tax on long-term gains means you keep only 80% of your paper profits. Over 30 years, this can shrink your portfolio’s growth by 10–20% compared to a tax-free scenario. The longer you hold investments, the more compounding works in your favor—but taxes still take their cut.
Q: Can I legally reduce the percentage of my net worth eaten by taxes?
A: Yes, but the strategies depend on your income level. The wealthy use trusts, tax-loss harvesting, and asset location to minimize taxes net worth percentages of pie. Middle-class earners benefit from retirement accounts (401(k)s, IRAs), HSAs, and state-specific deductions. The key is proactive planning—not retroactive damage control.
Q: Do estate taxes apply to all assets, or just cash?
A: Estate taxes apply to the total value of your assets at death, including real estate, stocks, businesses, and even retirement accounts (unless structured properly). The taxes net worth percentages of pie here are calculated on the gross estate value, minus deductions like debts and charitable donations. If your estate exceeds the exemption ($13.61M federally in 2024), the remaining amount is taxed at up to 40%. Proper estate planning can reduce this burden significantly.
Q: Why do some states have higher taxes than others?
A: State tax rates vary based on revenue needs, political priorities, and economic models. High-tax states like California and New York fund extensive public services (education, healthcare, infrastructure), while low-tax states like Texas and Florida rely more on sales taxes and private sector growth. The taxes net worth percentages of pie you face depend on where you live—moving to a lower-tax state can sometimes increase your net worth by reducing tax liabilities.
Q: How do sales taxes impact middle-class net worth?
A: Sales taxes are regressive, meaning they take a larger percentage of income from lower earners. A family spending $60,000 annually on taxable goods (groceries, housing, cars) in a 9% sales tax state could pay $5,400+ in sales taxes alone—that’s 9% of their spending, or 3–5% of their net worth if they’re saving aggressively. Unlike income taxes, sales taxes don’t offer deductions, making them a hidden drain on the taxes net worth percentages of pie for middle-class households.
Q: What’s the difference between marginal and effective tax rates?
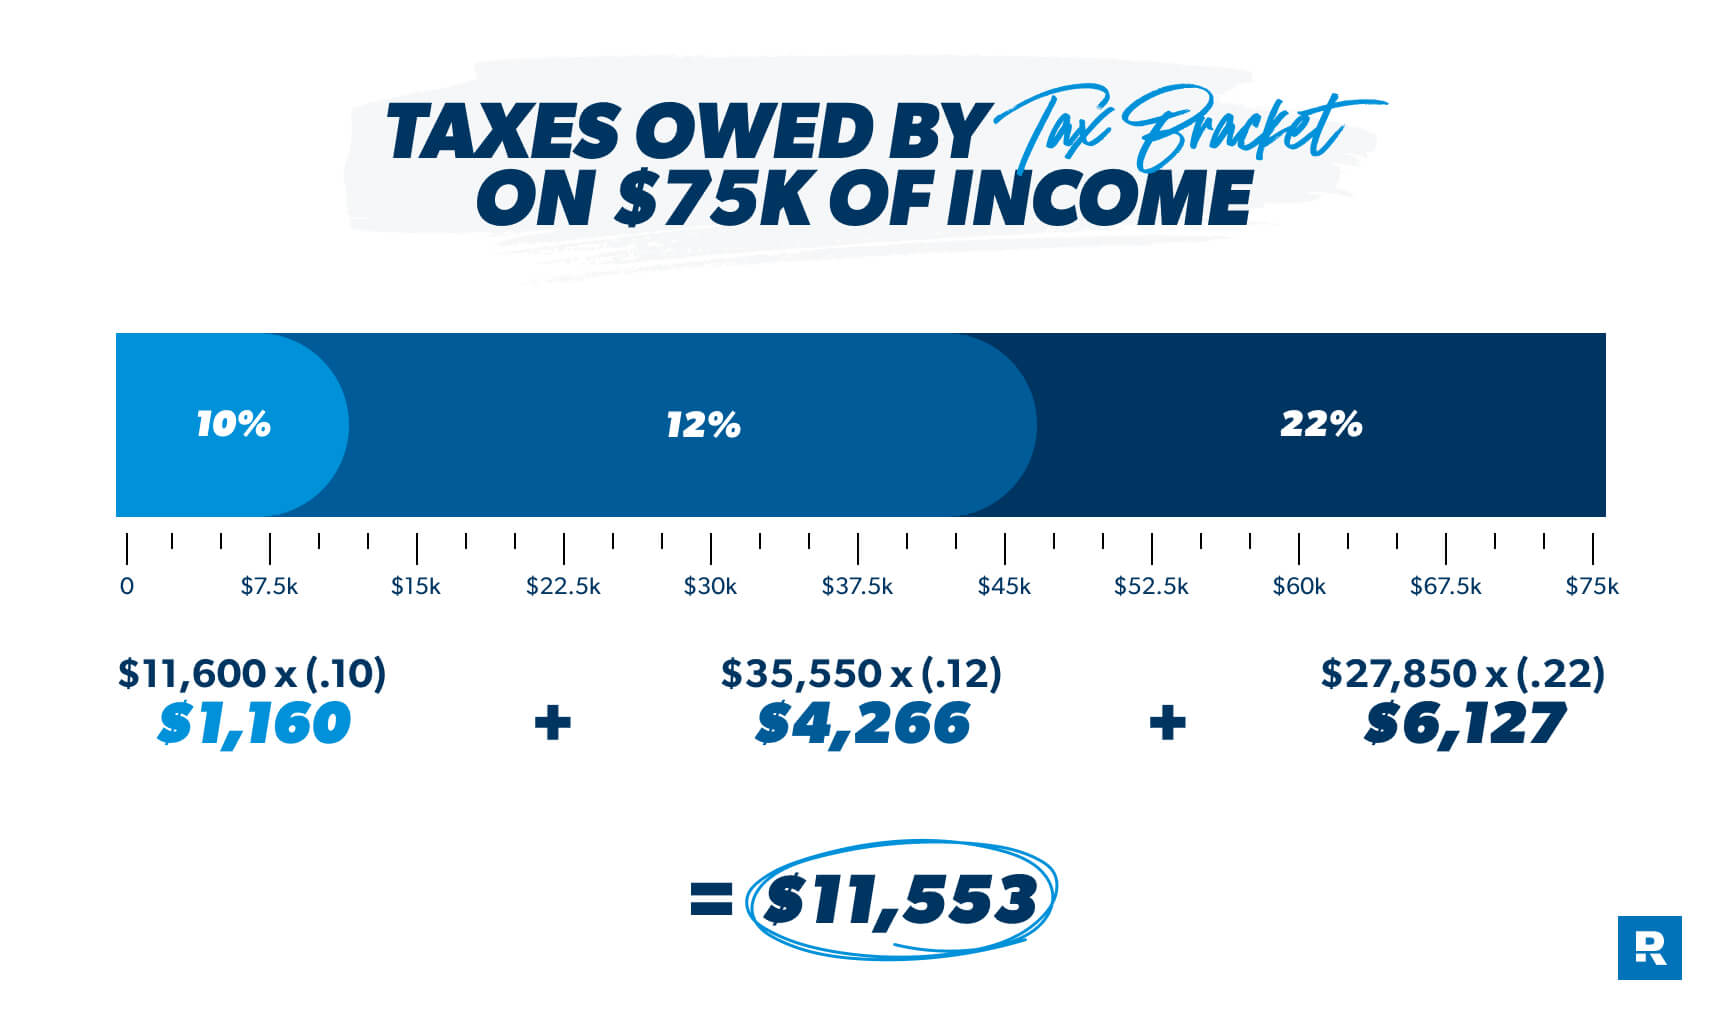
A: Marginal tax rates are the percentages applied to portions of your income (e.g., 22% on $50K–$90K). Effective tax rates are the actual percentage of your total income that goes to taxes after all deductions, credits, and exemptions. For example, someone in the 32% bracket might have an effective rate of 15% after deductions. The taxes net worth percentages of pie are determined by the effective rate—because that’s what actually reduces your wealth.
Q: Can I pass wealth to heirs without estate taxes?
A: Yes, but with planning. Strategies include:
- Trusts (bypass probate and reduce taxable estate)
- Gifting (annual exclusion of $18,000 per person in 2024)
- Charitable remainder trusts (reduce estate value while supporting causes)
- Life insurance policies (funded outside the estate)
Q: How do local property taxes affect homeowners?
A: Property taxes vary wildly—from 0.2% of home value in Louisiana to 2%+ in New Jersey. For a $500,000 home, that’s a $1,000 vs. $10,000 annual bill. Over 30 years, the taxes net worth percentages of pie can add up to $30,000–$300,000 in cumulative taxes. High property taxes also reduce home equity growth, as a larger portion of your mortgage payments goes to taxes rather than principal. Some states offer homestead exemptions, but the impact remains significant.
