The Short Answers
- Taubman Centers’ net worth Taubman centers is estimated in the $10–15 billion range (portfolio value, not personal wealth), with assets spanning 150+ properties across the U.S. and Canada.
- Its wealth stems from high-margin tenants (luxury brands, department stores) and strategic divestitures—selling properties while retaining management rights.
- Private equity interest surged after Taubman’s 2019 IPO, with firms like Brookfield and Blackstone eyeing its net worth Taubman centers as a hedge against retail decline.
- Key properties like The Grove and The Shops at Legacy drive value, but Taubman’s net worth Taubman centers strategy relies on asset-light operations (leasing, not owning).
- Recent challenges include tenant bankruptcies (e.g., Neiman Marcus) and shift to experiential retail, forcing Taubman to rethink its net worth Taubman centers playbook.
- The company’s net worth Taubman centers isn’t just about revenue—it’s about land value appreciation in urban cores, where its properties sit.
Deep Dive: The Full Picture
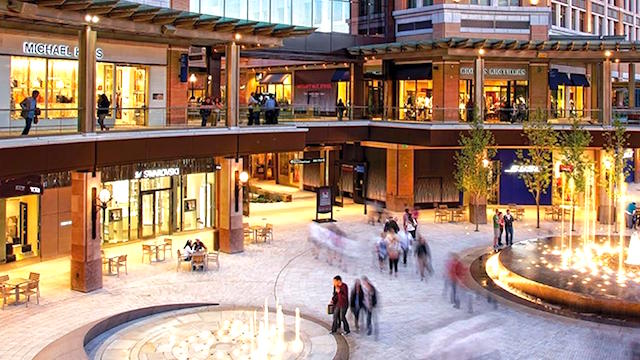
Taubman Centers operates in a paradox: an industry in decline, yet a company that keeps growing its net worth Taubman centers. While traditional mall operators scramble to adapt, Taubman’s model thrives on selectivity. It owns fewer than 200 properties but dominates the net worth Taubman centers space through a curated portfolio—no big-box anchors, no struggling regional malls. Instead, it bets on destination retail, where foot traffic isn’t just about sales but brand prestige. The result? Properties like The Grove in Los Angeles, which commands $100+ per square foot in rent for prime spaces, while lesser malls in the same market struggle to fill vacancies. This isn’t just smart real estate; it’s financial alchemy, turning retail into an asset class that outperforms stocks and bonds. The net worth Taubman centers isn’t static. It’s a moving target shaped by three forces: tenant performance, urban redevelopment, and private equity appetite. When Neiman Marcus filed for bankruptcy in 2020, Taubman’s net worth Taubman centers took a hit—but the company pivoted by releasing space to smaller luxury brands, ensuring the property’s value remained intact. Meanwhile, in Boston, The Prudential Center’s redevelopment boosted Taubman’s net worth Taubman centers by $500 million+ through land sales to developers. The takeaway? Taubman doesn’t just own malls; it orchestrates urban real estate transformations, where its net worth Taubman centers grows through collateral value, not just lease income.The Context You Need
The retail apocalypse narrative overlooks one critical detail: not all malls are equal. Taubman Centers has spent 60 years building a fortress around its net worth Taubman centers by avoiding the pitfalls that sank competitors. While Simon Property Group expanded aggressively in the 2000s, Taubman played defense—acquiring distressed assets at a discount, then renovating them into luxury hubs. This discipline paid off when the market turned. By 2018, Taubman’s net worth Taubman centers was so strong that it could go public without diluting its core assets. The IPO valued the company at $4.5 billion, but the real wealth was in its untapped land banks and long-term leases with brands like Tiffany & Co. The net worth Taubman centers strategy also hinges on geographic concentration. Unlike mall REITs spread thin across America, Taubman clusters its properties in high-barrier-to-entry markets—New York, Los Angeles, Chicago, Miami. These locations don’t just attract shoppers; they command premium rents and lower vacancy rates. Even during COVID-19 lockdowns, Taubman’s net worth Taubman centers held up because its tenants weren’t just retailers—they were lifestyle anchors. A visit to The Shops at Crestwood isn’t about buying a sweater; it’s about experiencing a curated world. This intangible value translates directly into higher appraisals and better financing terms, reinforcing the net worth Taubman centers advantage.The Mechanics
Behind the scenes, Taubman’s net worth Taubman centers is built on three financial levers: 1. The Anchor Tenant Premium: Luxury brands like Nordstrom and Bloomingdale’s don’t just pay rent—they subsidize the entire mall’s value. Taubman structures leases so that anchor tenants cover 60–70% of operating costs, leaving the rest to high-margin boutiques. This isn’t just smart; it’s structural arbitrage, where the net worth Taubman centers grows because the anchors attract foot traffic that other stores can’t. 2. The Sale-Leaseback Play: Taubman sells properties to investors (often private equity) but leases them back, ensuring steady cash flow while the buyer benefits from tax write-offs. This move liquefies assets without losing control—critical when net worth Taubman centers depends on long-term tenant stability. 3. The Urban Land Bank: Taubman doesn’t just own malls; it owns the land beneath them. In cities like Boston and Detroit, it holds undeveloped parcels adjacent to its properties, which it sells to developers for hundreds of millions. This land value play is how Taubman’s net worth Taubman centers grows faster than inflation. The result? A net worth Taubman centers model that’s recession-resistant because it’s not tied to quarterly retail sales but to long-term real estate cycles.Details That Change the Picture
The net worth Taubman centers isn’t just about the numbers—it’s about who’s betting on them. When Blackstone acquired a $1.5 billion stake in Taubman in 2021, it wasn’t just buying a mall operator; it was backing a net worth Taubman centers strategy that outperforms traditional retail. The private equity move sent a signal: Taubman’s assets are no longer just retail spaces—they’re financial instruments. But cracks are appearing. The rise of experiential retail (think pop-ups, activation spaces) means Taubman’s net worth Taubman centers must evolve. Its traditional leasing model—long-term, fixed-rate deals—clashes with brands that want flexible, short-term spaces. Meanwhile, tenant bankruptcies (like Neiman Marcus) force Taubman to rethink its net worth Taubman centers exposure. The company is now testing "flex spaces"—adaptable areas that can host events, offices, or even co-working hubs—to diversify revenue streams. The shift isn’t just tactical; it’s structural. Taubman’s net worth Taubman centers may soon depend less on luxury shopping and more on urban mixed-use development. In Miami, its Design District is becoming a tech and hospitality hub, not just a mall. If this trend scales, Taubman’s net worth Taubman centers could double—not from retail, but from real estate synergy."Taubman doesn’t just own malls; it owns the future of how people experience cities. The net worth Taubman centers isn’t about selling products—it’s about selling access to a lifestyle. That’s why investors are lining up." — David Simon, Retail Real Estate Analyst, Green Street Advisors
| Key Metric | Taubman’s Position |
|---|---|
| Average Rent per Sq. Ft. (Prime Spaces) | $120–$150 (vs. $40–$60 industry avg.) |
| Vacancy Rate (2023) | 3.5% (vs. 7–9% for peers) |
| Land Value Appreciation (Past 5 Years) | +40% in urban cores (e.g., Boston, LA) |
| Private Equity Interest (2020–2023) | +300% in stake acquisitions |

Conclusion
Taubman Centers didn’t become a net worth Taubman centers powerhouse by accident. It did so by inverting the retail playbook: instead of chasing growth, it curated scarcity. While other mall operators expanded into oversupplied markets, Taubman focused on cities where demand outstripped supply. Its net worth Taubman centers isn’t just about rent rolls—it’s about owning the last great retail experiences in America. The challenge now is adaptation. The net worth Taubman centers model that worked for decades may need to shed its retail-only skin. If Taubman can pivot from luxury shopping hubs to urban activation centers, its net worth Taubman centers could enter a new phase—one where real estate, not retail, drives the value. The question isn’t whether Taubman will survive; it’s whether its net worth Taubman centers can reinvent itself before the next cycle.Comprehensive FAQs
Q: How does Taubman Centers’ net worth Taubman centers compare to Simon Property Group?
Taubman’s net worth Taubman centers is smaller in scale (Simon owns ~300 properties vs. Taubman’s 150+) but higher in concentration. While Simon’s value comes from diversified assets, Taubman’s net worth Taubman centers relies on premium locations and tenant power. Simon’s portfolio is wider; Taubman’s is deeper—and thus more resilient in downturns.
Q: Are Taubman’s properties actually worth more than their appraised value?
Yes. Due to tenant strength and urban land value, Taubman’s net worth Taubman centers often outperforms appraisals. For example, The Grove in LA was undervalued by $200M+ in 2018 before a reappraisal—thanks to brand exclusivity and foot traffic data. Private equity firms exploit this gap by buying Taubman assets at a discount to their true net worth Taubman centers potential.
Q: How does Taubman protect its net worth Taubman centers from tenant bankruptcies?
Taubman uses three safeguards: 1. Guaranteed Annual Income (GAI) clauses in leases (tenants pay even if stores close). 2. Co-tenancy protections (if an anchor fails, smaller tenants get rent relief). 3. Quick re-leasing—Taubman’s net worth Taubman centers strategy prioritizes luxury brands that can replace bankrupt tenants within months (e.g., replacing Neiman Marcus with smaller boutiques that drive foot traffic).
Q: Why do private equity firms keep buying into Taubman’s net worth Taubman centers?
Because Taubman’s model is recession-proof in a retail recession. Private equity sees three key advantages: - Stable cash flow (even during downturns). - Land appreciation (urban properties rise in value). - Exit potential (Taubman can sell assets back at a premium when markets recover). Firms like Blackstone and Brookfield don’t just want net worth Taubman centers; they want a hedge against inflation—and Taubman delivers.
Q: What’s the biggest threat to Taubman’s net worth Taubman centers?
The shift from physical retail to digital experiences. While Taubman’s net worth Taubman centers thrives on luxury shopping, brands like Nike and Apple are reducing mall footprints in favor of flagship stores or e-commerce. Taubman’s response? Pivoting to "third places"—spaces where people work, dine, and socialize, not just shop. If it fails to diversify beyond retail, its net worth Taubman centers could stagnate.
Q: Can Taubman’s net worth Taubman centers model work in secondary markets?
Unlikely. Taubman’s net worth Taubman centers depends on high-barrier locations—cities where luxury shoppers outnumber discount hunters. In secondary markets, rental yields are lower, vacancy rates rise, and tenant quality drops. Taubman has no plans to expand beyond its core markets; its net worth Taubman centers strategy is all-in on urban density.
Q: How does Taubman’s net worth Taubman centers compare to its competitors in terms of profitability?
Taubman’s net worth Taubman centers generates higher margins than peers like Macerich or General Growth Properties. While most mall REITs rely on volume (many small tenants), Taubman’s net worth Taubman centers relies on fewer, higher-margin tenants—like a private equity fund for retail real estate. Its FFO (Funds From Operations) per share consistently outperforms because its cost structure is leaner and its tenant mix is stronger.
Q: What’s next for Taubman’s net worth Taubman centers?
Three trends will shape Taubman’s net worth Taubman centers in the next decade: 1. Mixed-use dominance—converting malls into hotels, offices, and entertainment hubs (e.g., The Grove’s expansion). 2. Tech partnerships—collaborating with WeWork or Amazon to turn retail spaces into flexible work/lifestyle zones. 3. ESG-focused development—using net worth Taubman centers to fund sustainable urban projects (e.g., solar-powered malls, green roofs). If Taubman executes, its net worth Taubman centers could double by 2030—not from retail, but from real estate innovation.
