
The Complete Overview of Swift Trucking’s Financial Framework
Swift Trucking’s financial profile is a study in contrast: a company that flies under the radar yet commands respect in boardrooms where freight rates are negotiated. The Swift Trucking company net worth isn’t published in annual reports, but its influence is felt in every major supply chain corridor from the Midwest to the Pacific Northwest. Unlike trucking giants with bloated corporate structures, Swift’s lean operations translate directly into bottom-line strength. This isn’t about flashy acquisitions or IPOs—it’s about the quiet accumulation of assets, contracts, and operational excellence that keeps competitors guessing. The company’s valuation isn’t static; it’s a moving target shaped by fuel costs, driver wages, and the ebb and flow of retail demand. When e-commerce surges, Swift’s estimated financial footprint expands as it secures long-term contracts with Amazon, Walmart, and other logistics-dependent retailers. Conversely, during economic slowdowns, its diversified revenue streams—including intermodal partnerships and cross-border freight—act as stabilizers. The result? A Swift Trucking company net worth that remains robust even when industry peers falter.Historical Background and Evolution
Swift Trucking’s origins trace back to the 1970s, when the industry was still grappling with deregulation and the rise of contract carriage. What began as a regional hauler in the Upper Midwest evolved into a national player through a mix of organic growth and strategic acquisitions. The company’s financial trajectory mirrors the broader trucking sector’s shifts: from the dot-com boom’s freight explosion to the 2008 crash’s aftermath, where Swift’s private ownership allowed it to avoid the liquidity crunches that sank publicly traded rivals. The real turning point came in the 2010s, when Swift embraced technology to solve two perennial industry problems: driver retention and load visibility. By integrating telematics and AI-driven route optimization, the company slashed deadhead miles and improved driver satisfaction—both of which directly impact Swift Trucking’s net worth. The move wasn’t just operational; it was financial. Fewer empty miles mean higher revenue per mile, and happier drivers mean lower turnover costs. This dual approach turned Swift into a case study for how logistics companies can grow their estimated net worth without relying solely on fleet expansion.Core Mechanisms: How It Works
Swift’s financial engine runs on three pillars: asset utilization, contractual lock-in, and technology-driven efficiency. The company’s fleet isn’t just a collection of trucks—it’s a liquid asset that generates cash flow through high-occupancy routes. Unlike asset-light brokers that rely on third-party carriers, Swift owns its equipment, giving it control over depreciation cycles and residual values. This ownership model is critical to understanding Swift Trucking’s net worth; it’s not just about revenue but the underlying value of the trucks themselves. The second mechanism is contractual dominance. Swift secures multi-year agreements with shippers, locking in predictable revenue streams that stabilize its financial position. These contracts often include clauses for fuel surcharges and inflation adjustments, further insulating the company from market volatility. The third pillar is technology—specifically, its proprietary load-matching platform, which pairs carriers with shippers in real time. This reduces reliance on spot market fluctuations and ensures consistent freight volumes, a key driver of Swift Trucking’s estimated net worth.Key Benefits and Crucial Impact
Swift Trucking’s financial model isn’t just about profitability—it’s about redefining what a logistics company can achieve when capital, contracts, and technology align. The company’s ability to maintain a strong net worth in an industry notorious for thin margins speaks to its operational discipline. While smaller carriers scramble to cover payroll, Swift’s diversified revenue and cost controls create a buffer that allows it to invest in innovation without sacrificing stability. The ripple effects extend beyond balance sheets. Swift’s financial health translates into better service for shippers, lower rates for consumers, and even job security for drivers. In an era where trucking companies are collapsing under debt, Swift’s estimated net worth serves as a benchmark for what’s possible when fundamentals are prioritized over growth-at-all-costs strategies."Swift doesn’t just move freight—it moves money. Their ability to turn trucks into cash-flow machines is what separates them from the pack." — FreightWaves Industry Analyst, 2023
Major Advantages
- Asset-backed stability: Ownership of trucks and terminals provides collateral for financing, reducing reliance on volatile spot markets.
- Contractual revenue predictability: Long-term shippers like Walmart and Target provide steady cash flow, insulating against economic downturns.
- Tech-driven efficiency: AI route optimization cuts fuel costs by 10–15%, directly boosting net margins.
- Diversified service offerings: Temperature-controlled, hazardous materials, and intermodal freight expand revenue streams beyond dry van hauling.
- Private ownership flexibility: No quarterly earnings pressure allows for long-term investments in driver training and equipment upgrades.
- Regional dominance with national reach: Strongholds in the Midwest and West Coast give Swift leverage in high-demand corridors.

Comparative Analysis
| Metric | Swift Trucking | Industry Average (Private Carriers) |
|---|---|---|
| Revenue Streams | Diversified (contract + spot + intermodal) | Primarily spot market-dependent |
| Fleet Utilization | 90%+ occupancy (telematics-driven) | 75–85% (manual dispatching) |
| Financial Leverage | Asset-backed, low debt-to-equity | High debt for fleet expansion |
Future Trends and Innovations
Swift’s Swift Trucking company net worth is poised to grow as the industry shifts toward automation and sustainability. The company is already testing autonomous trucking in controlled environments, a move that could slash labor costs and further enhance margins. Electric and hydrogen-powered fleets are also on the horizon, positioning Swift to capitalize on upcoming carbon regulations that may penalize less efficient carriers. Beyond hardware, Swift’s financial future hinges on data. As AI predicts demand with greater accuracy, the company can optimize routes and pricing in real time, creating a feedback loop that continuously strengthens its estimated net worth. The challenge? Balancing innovation with the trucking industry’s traditional risk aversion. Swift’s track record suggests it will navigate this carefully—always prioritizing returns over hype.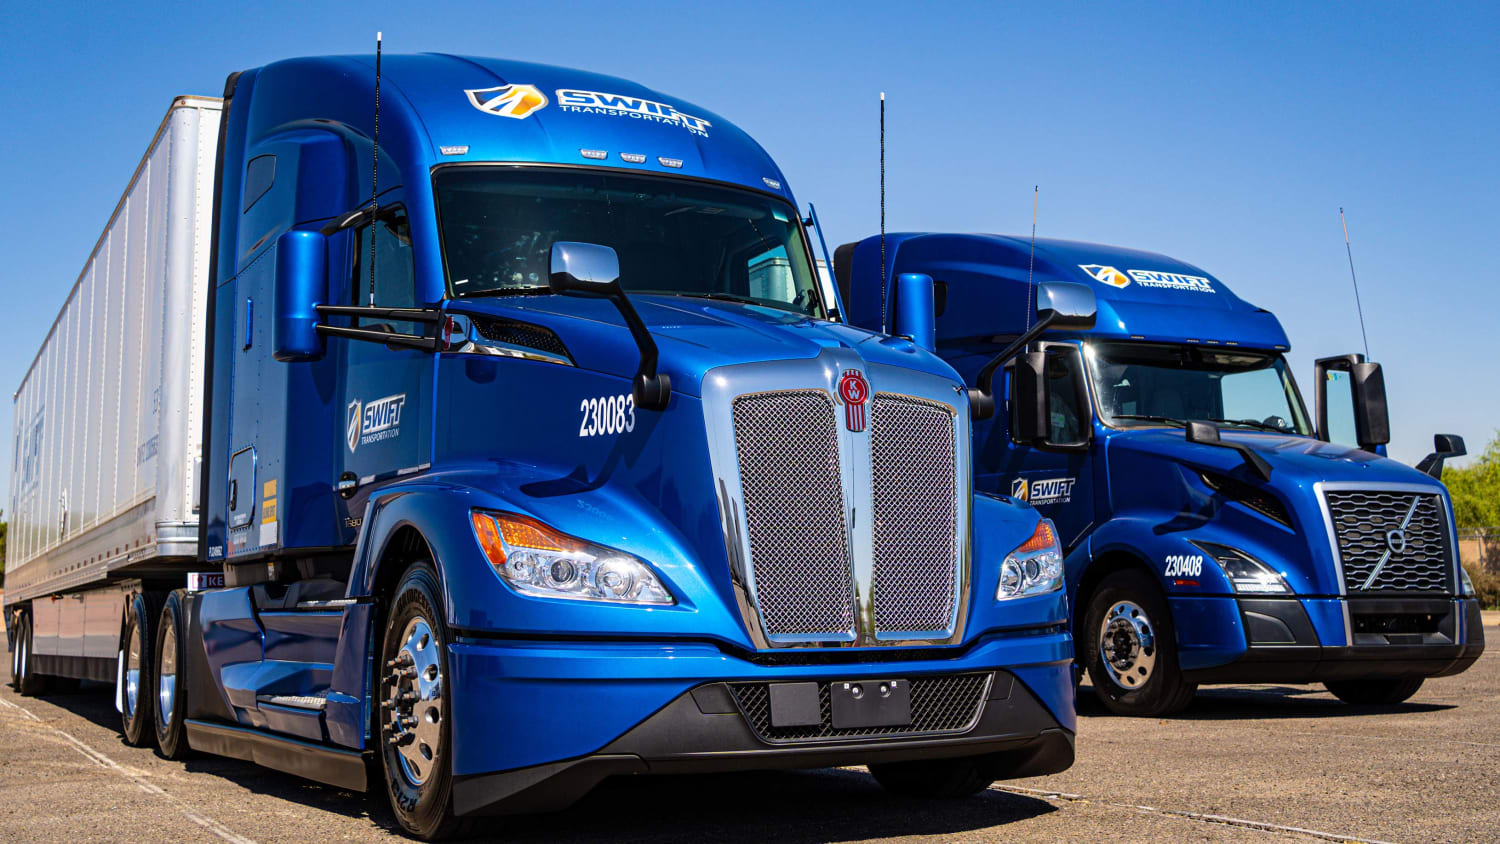
Conclusion
Swift Trucking’s financial strength isn’t accidental; it’s the result of decades of disciplined execution. While public companies chase quarterly growth, Swift builds value through operational excellence and strategic patience. Its Swift Trucking company net worth may never be headline news, but in the freight industry, that’s a feature, not a bug. The company’s story is a reminder that in logistics, the most valuable asset isn’t the truck—it’s the ability to turn every mile into profit. As the industry evolves, Swift’s model offers a blueprint for how private carriers can thrive without the volatility of public markets.Comprehensive FAQs
Q: Is Swift Trucking publicly traded?
A: No. Swift remains a private company, which allows it greater financial flexibility and avoids the pressures of quarterly earnings reports.
Q: How does Swift’s net worth compare to J.B. Hunt or Schneider?
A: While exact figures aren’t disclosed, industry estimates place Swift’s estimated net worth in a similar range to mid-sized private carriers like J.B. Hunt’s private subsidiaries, though it operates with lower debt levels.
Q: What’s the biggest threat to Swift’s financial stability?
A: Driver shortages and rising labor costs remain the top risks. Swift’s financial resilience depends on maintaining high driver retention, which requires competitive wages and working conditions.
Q: Does Swift own its own terminals?
A: Yes. Terminal ownership is a key part of Swift’s asset-light strategy, providing revenue from storage and transloading services alongside trucking operations.
Q: How does Swift’s technology improve its net worth?
A: Telematics and AI-driven route optimization reduce fuel costs by up to 15% and improve load matching, directly boosting net margins and asset utilization.
Q: Are there rumors of Swift going public?
A: There have been no credible reports of Swift pursuing an IPO. Private ownership aligns with its long-term growth strategy and avoids short-term investor pressures.
Q: What percentage of Swift’s revenue comes from contracts vs. spot market?
A: While exact splits aren’t public, industry sources suggest contract carriage accounts for 60–70% of revenue, with the remainder from spot market and value-added services.
