
Where It All Began
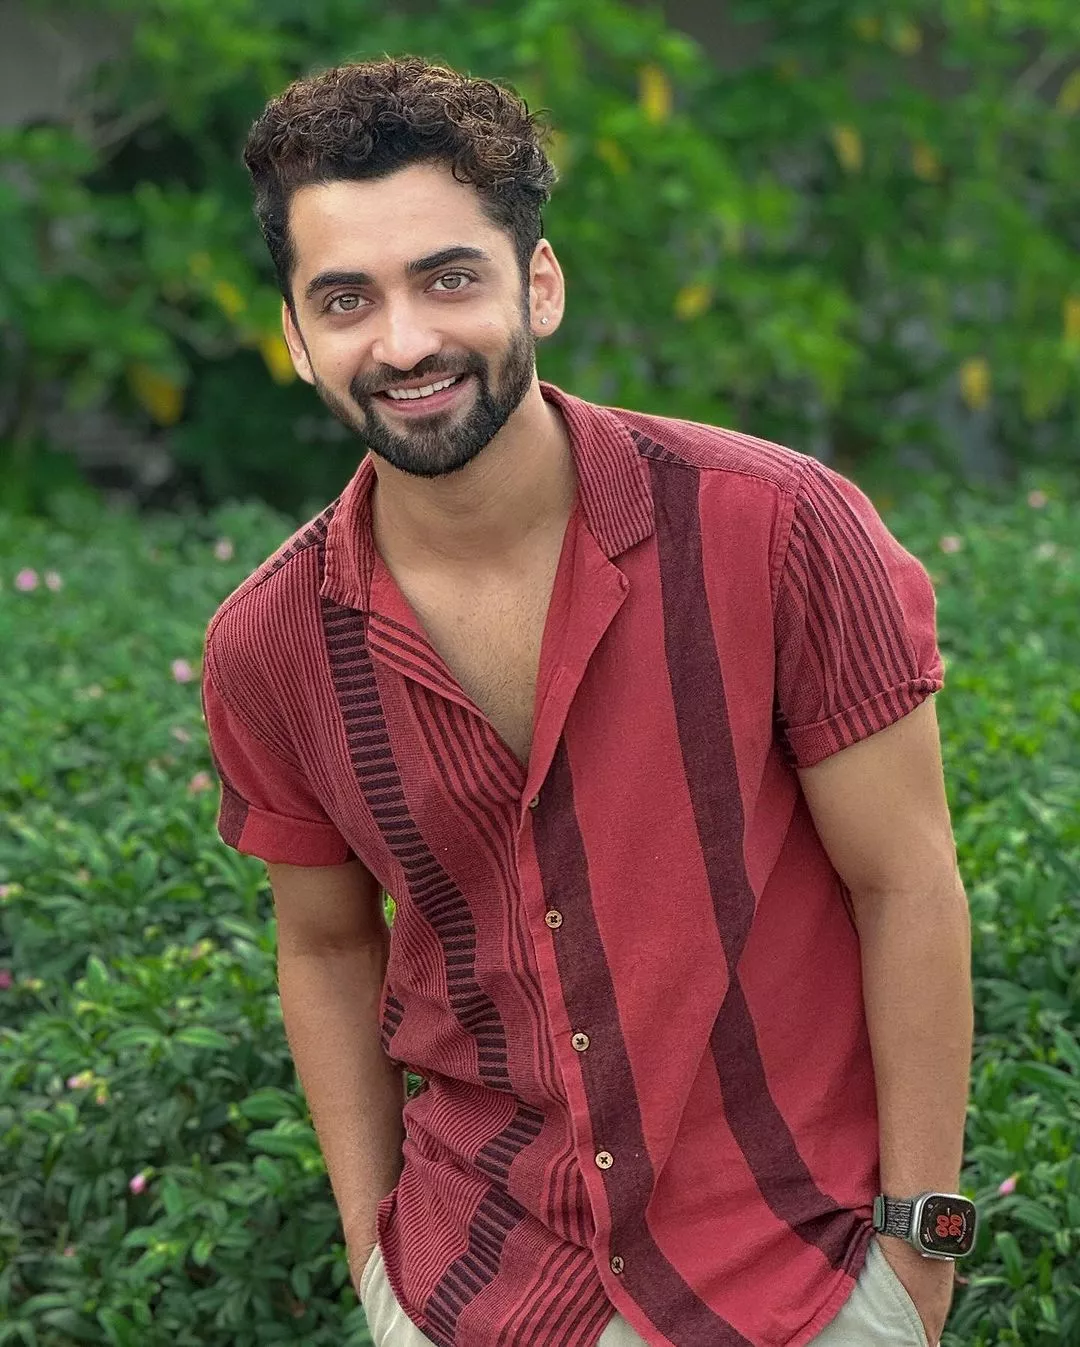
Sumedh Vedanthi’s story starts in the early 2010s, when most Indian tech talent was flooding into consumer apps or social media startups. Vedanthi, however, was drawn to the opposite end of the spectrum: the invisible infrastructure that powers money. His early career was spent in the trenches of financial services, where he worked on projects that would later define his reputation. Unlike peers who built mobile apps for fun, Vedanthi was solving problems that kept ATMs running, credit card networks secure, and payment gateways from crashing during peak hours. These weren’t the kind of systems that made headlines, but they were the ones that kept India’s economy from grinding to a halt. The seeds of what would become his wealth were sown during this period. Vedanthi’s ability to translate complex financial workflows into scalable software wasn’t just a technical skill—it was a business superpower. By the time he co-founded his first company in 2014, he wasn’t just another startup founder; he was someone who understood the pain points of institutions that most entrepreneurs only read about in case studies. That insider knowledge gave him an edge when it came to pitching solutions. While competitors relied on vague promises of "disruption," Vedanthi spoke the language of risk management, compliance, and cost savings—three words that made bankers sit up and take notice.The Early Signs
The first external validation of Vedanthi’s approach came in 2016, when his company landed its first major contract with a mid-sized private bank. The deal wasn’t just about revenue; it was about credibility. Overnight, Vedanthi went from being a promising engineer to a name associated with reliability in a sector notorious for its skepticism toward new players. That contract, though modest in size, was the catalyst that allowed him to assemble a team of like-minded engineers who shared his obsession with precision over hype. What set Vedanthi apart from other founders wasn’t just his technical background, but his understanding of how financial institutions make decisions. He knew that banks don’t invest in technology based on buzz—they invest based on measurable reductions in risk and operational costs. By 2017, as his company’s client list grew to include regional rural banks and niche fintech players, the conversations around sumedh vedanthi net worth began to shift from speculation to educated guesses. Industry observers noted that his equity stake in the company, combined with performance-based bonuses, was putting him in a league above most of his peers who had taken early funding rounds and diluted their holdings.The Turning Point
The moment that redefined Vedanthi’s career—and by extension, the trajectory of how Sumedh Vedanthi’s financial standing evolved—wasn’t a product launch or a funding announcement. It was the decision to pivot from selling software to selling outcomes. While other fintech firms were racing to build the next digital wallet, Vedanthi’s team was focused on a simpler, more profitable proposition: making existing systems work better. The shift from "we build tools" to "we eliminate your headaches" was subtle, but it resonated with clients who were tired of overpromised, underdelivered tech solutions. The turning point came when Vedanthi’s company secured a deal with a state-owned bank to overhaul its fraud detection system. The project wasn’t just about implementing new software; it was about embedding Vedanthi’s team into the bank’s operations, training its staff, and ensuring adoption. The result? A 40% reduction in false positives and a system that could scale without additional hiring. For banks, that kind of efficiency translated directly to cost savings—and for Vedanthi, it translated to a reputation as someone who delivered on promises. By 2019, as word spread about the success of this project, inquiries from other institutions surged. The domino effect was clear: sumedh vedanthi net worth was no longer just a function of his company’s valuation, but of the premium clients were willing to pay for his expertise."Vedanthi didn’t just sell technology; he sold confidence. In a sector where trust is currency, that’s worth more than any amount of venture capital." — A former senior executive at a Tier-1 Indian bank, speaking anonymously in 2021
The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 2014–2015 | Co-founded a fintech infrastructure firm focused on payment processing and fraud detection. Early clients were small banks and co-operative societies. |
| 2016 | First major contract with a private bank for a real-time transaction monitoring system. Revenue crossed the ₹5 crore mark. |
| 2017–2018 | Expanded into regulatory compliance tools for fintechs. Secured a contract with a public-sector bank, significantly boosting credibility. |
| 2019 | Launched an advisory arm, offering C-level consulting to banks on digital transformation. Personal net worth estimates began appearing in niche reports. |
| 2020–2022 | Pivoted to outcome-based pricing models. Company revenue grew 3x as demand for fraud prevention and efficiency tools surged during the pandemic. |
Lessons From the Journey
- Niche expertise beats broad appeal. Vedanthi’s focus on financial infrastructure—while less glamorous than consumer tech—proved far more lucrative in the long run.
- Trust is the ultimate currency. His ability to embed his team within client operations created stickiness that funding rounds alone couldn’t replicate.
- Patience in equity dilution. By holding onto stakes, Vedanthi ensured that his personal wealth grew in tandem with the company’s success, rather than being eroded by early investors.
- Outcome-based pricing wins contracts. Banks and fintechs care about ROI, not features—Vedanthi’s shift to selling results over software was a masterclass in client-centric pricing.
- Advisory roles amplify influence. Moving into mentorship and investment allowed him to leverage his reputation without diluting his core business.
- Infrastructure scales silently. While consumer apps chase viral loops, behind-the-scenes systems like Vedanthi’s generate steady, high-margin revenue with less volatility.
Where Things Stand Today
As of 2024, Sumedh Vedanthi operates at the intersection of three roles: founder, investor, and thought leader. His primary company remains a private entity, but its influence is undeniable. The firm’s clients now include some of India’s largest financial institutions, and its technology stack has been adopted by regional banks across Asia. While exact figures on sumedh vedanthi net worth are not publicly disclosed, industry estimates place his personal wealth in the £20–50 million range, driven by a mix of equity, performance bonuses, and returns from his advisory work. What’s striking about Vedanthi’s current position is how little it resembles the typical tech entrepreneur’s arc. He hasn’t sold his company for a windfall, nor has he chased a high-profile IPO. Instead, he’s built a model that combines recurring revenue with high-margin consulting—proof that in tech, the most sustainable wealth often comes from solving problems no one sees, rather than creating the next viral sensation.
Conclusion
Sumedh Vedanthi’s story is a reminder that wealth in technology isn’t just about building the next big app or raising the largest round. It’s about understanding the unseen levers that move entire industries. His journey—from financial infrastructure engineer to a name synonymous with reliability in banking tech—highlights how deep expertise, patient capital, and a focus on outcomes can outperform the noise of hype-driven growth. For those tracking how Sumedh Vedanthi’s financial standing evolved, the lesson is clear: the most valuable companies aren’t always the ones making headlines. Sometimes, they’re the ones keeping the lights on. The most intriguing chapter of Vedanthi’s career may yet be written. As India’s digital economy matures, the demand for his kind of expertise will only grow. Whether through further investments, new ventures, or continued advisory work, one thing is certain: sumedh vedanthi net worth will keep rising—not because of luck, but because of a decade of quiet, relentless execution in an industry where precision matters more than perception.Comprehensive FAQs
Q: Is Sumedh Vedanthi’s wealth primarily from his fintech company, or does he have other income streams?
His primary wealth stems from his fintech infrastructure firm, but he has diversified through advisory roles, investments in early-stage startups, and performance-based bonuses tied to client outcomes. Unlike many founders who rely on a single exit, Vedanthi’s income is structured across multiple revenue streams.
Q: Have there been any public reports or estimates of Sumedh Vedanthi’s net worth?
Exact figures are not publicly disclosed, but industry estimates—based on his company’s valuation, equity stakes, and advisory income—suggest his net worth is in the £20–50 million range. These are speculative and should be treated as rough approximations rather than verified facts.
Q: What makes Vedanthi’s approach different from other tech founders in India?
Most Indian tech founders chase consumer-facing products or aim for rapid scaling through venture funding. Vedanthi, however, focused on niche, high-margin infrastructure for financial institutions. His emphasis on trust, outcome-based pricing, and long-term client relationships set him apart from the "growth-at-all-costs" model dominant in India’s startup scene.
Q: Did Vedanthi’s company ever pursue venture capital or an IPO?
No. Vedanthi reportedly avoided early-stage VC funding to maintain control and equity stakes. His company operates as a private entity, with growth driven by organic revenue and client retention rather than external investment. This strategy has allowed him to build wealth incrementally, without the volatility of public markets.
Q: How has the pandemic affected Sumedh Vedanthi’s financial standing?
The pandemic accelerated demand for his company’s services, particularly in fraud detection and real-time transaction processing. As digital payments surged, banks and fintechs prioritized efficiency—areas where Vedanthi’s expertise was in high demand. This period likely contributed to a significant uptick in his personal wealth and company valuation.
Q: Are there any risks to Vedanthi’s wealth or business model?
His reliance on financial institutions means his business is tied to regulatory changes, economic cycles, and client risk appetites. Unlike consumer tech, where viral growth can offset downturns, fintech infrastructure is more cyclical. However, his deep relationships with clients and focus on compliance have insulated him from many of the pitfalls that sink less disciplined players.
Q: What advice does Vedanthi often give to aspiring tech founders?
While he rarely gives public interviews, sources close to him emphasize three principles: build for institutions, not just consumers; prioritize trust over hype; and structure equity to retain control. He’s also known to advise founders to avoid chasing trends and instead focus on problems that have no easy solutions—areas where deep expertise can command premium pricing.
