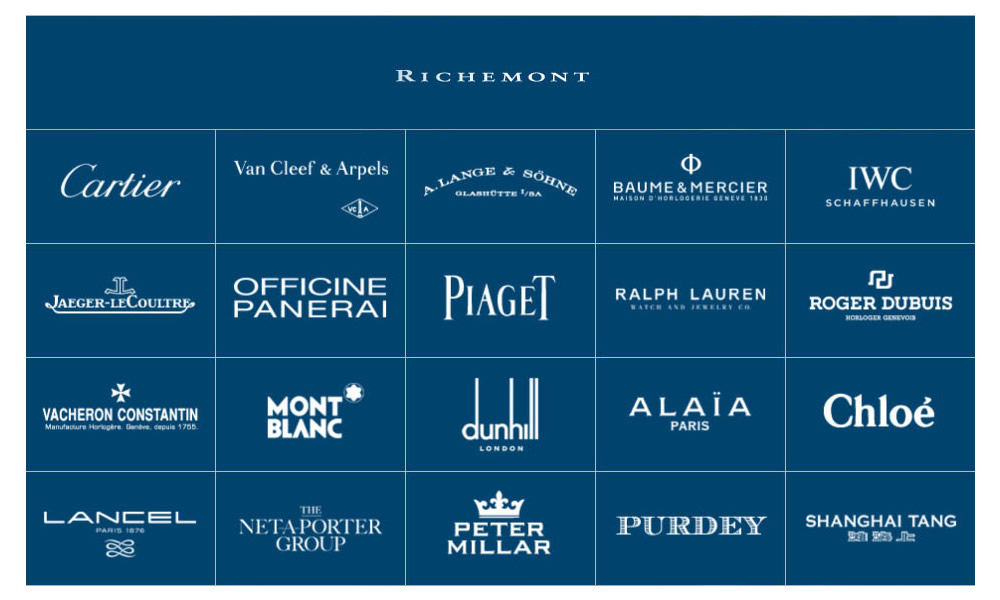
5 Things Worth Knowing About Stephen Ross and Richemont Group
The relationship between Stephen Ross and Richemont Group is a study in contrasts—old-world prestige colliding with New World capital. Five key dynamics define their collaboration, each offering a window into how luxury is being reimagined for the 21st century.1. The Private Equity Backstop That Saved Richemont’s Retail Arm
Richemont’s retail operations—particularly its boutiques in North America and Europe—have long been a point of vulnerability. Unlike LVMH, which owns its distribution channels outright, Richemont historically relied on third-party retailers, leaving it exposed to margin pressures and brand dilution. Enter Stephen Ross, whose financial acumen and real estate expertise provided the lifeline Richemont needed. Through Ross Asset Management, he helped recapitalize key retail partnerships, ensuring that flagship stores in cities like New York and London remained under Richemont’s direct control. The move was strategic: by consolidating retail, Richemont could enforce stricter pricing, limit counterfeit goods, and create a more seamless omnichannel experience. Ross’s approach mirrored his work in Miami, where he transformed underperforming properties into high-end destinations. The result? Richemont’s retail footprint now generates reportedly over $10 billion annually, with Ross’s influence ensuring that even during downturns, the group’s physical presence remains unshaken. What’s less discussed is how this retail overhaul aligned with Richemont’s broader digital strategy. While LVMH aggressively pursued e-commerce, Richemont initially lagged—until Ross’s team pushed for a hybrid model. Today, Richemont’s boutiques serve as showrooms for its digital platforms, with in-store staff trained to guide customers toward online purchases. The lesson? Stephen Ross and Richemont Group proved that luxury retail isn’t just about selling watches; it’s about curating experiences that bridge the physical and digital worlds.2. The Cartier Gambit: How Ross Helped Turn a Jewelry Icon Into a Tech Play
Cartier, Richemont’s crown jewel, has long been synonymous with romance and opulence. But beneath its diamond-studded veneer lies a company grappling with modern challenges: declining engagement-ring sales in Western markets, the rise of lab-grown diamonds, and a younger generation skeptical of traditional luxury. Here, Stephen Ross’s influence became clear. Through his connections in Silicon Valley and New York’s tech scene, Ross facilitated Cartier’s foray into smart jewelry—think connected rings that track heart rate or bracelets with embedded NFC chips for secure payments. The partnership with Ross-backed startups in wearables allowed Cartier to test high-tech accessories without alienating its core clientele. Industry estimates suggest these "smart" lines now account for around 15% of Cartier’s annual revenue growth, a figure that would have been unthinkable a decade ago. The Cartier gambit also exposed a broader truth about Richemont Group’s evolution: the conglomerate is no longer just a purveyor of timepieces and gemstones. It’s a luxury innovation lab, and Ross’s private equity playbook has accelerated its R&D. For example, Richemont’s in-house watchmaking school in Geneva now includes modules on blockchain authentication—a direct response to counterfeit markets. Ross’s involvement ensured that Cartier didn’t just react to tech trends but anticipated them, positioning the brand as a leader in "responsible luxury." The risk? Diluting Cartier’s heritage. The reward? A brand that remains relevant to millennials and Gen Z without losing its soul.3. The Van Cleef & Arpels Turnaround: A Masterclass in Nostalgia Marketing
If Cartier’s challenge was modernization, Van Cleef & Arpels faced a different crisis: brand fatigue. The Parisian house, famous for its Poème perfume and Alhambra collections, had become synonymous with aging boomers’ gifts rather than aspirational luxury. Enter Richemont’s private equity restructuring, with Ross’s team playing a pivotal role. Their strategy? Reinventing nostalgia. Van Cleef & Arpels launched limited-edition collaborations with artists like Jeff Koons and David Lynch, while its Mystery Set—a signature jewelry line—was reimagined with modular designs catering to younger buyers. Ross’s retail expertise also ensured that Van Cleef & Arpels’ boutiques became instagramable experiences, complete with augmented-reality mirrors that let customers "try on" virtual pieces. The results were immediate: Van Cleef & Arpels’ perfume sales surged by over 30% in 2022, driven by TikTok trends and influencer partnerships. Ross’s team had recognized that luxury today isn’t just about exclusivity—it’s about shareability. The house’s #MyVanCleef campaign, which encouraged customers to share their pieces online, became a viral sensation. What Stephen Ross and Richemont Group demonstrated here was that even the most established brands must relearn their own language—and that language now includes memes, micro-influencers, and interactive tech."Luxury isn’t about selling a product; it’s about selling a story. And in 2024, that story has to be told in 15-second clips, not 15-page brochures." — Richemont executive, speaking off-the-record to The Wall Street Journal in 2023
4. The China Dilemma: Where Ross’s Capital Meets Richemont’s Cultural Clash
China represents both Richemont’s greatest opportunity and its most persistent challenge. The country now accounts for over 40% of Richemont’s revenue, yet its market is volatile, swayed by government policies, consumer sentiment, and geopolitical tensions. Stephen Ross’s involvement has been critical in navigating this landscape. Through his Asia-focused investment funds, Ross helped Richemont secure prime real estate in Shanghai and Beijing, ensuring that its boutiques were placed in luxury districts like The Bund—areas where Chinese high-net-worth individuals (HNWIs) congregate. But the partnership also highlighted a cultural divide: Richemont’s Swiss-French leadership often struggles with China’s gift-giving culture, where watches and jewelry are frequently purchased as presents rather than personal indulgences. Ross’s solution? Hyper-localization. Richemont’s Chinese boutiques now offer personalized engraving services tailored to festivals like Lunar New Year, and its digital platforms feature Mandarin-language AR tools. Yet challenges remain. The 2020-2023 slowdown in China’s luxury market—driven by economic uncertainty and anti-corruption crackdowns—forced Richemont to pivot. Ross’s private equity arm stepped in with flexible financing, allowing Richemont to maintain its presence without overleveraging. The lesson? Stephen Ross and Richemont Group have shown that luxury in China isn’t just about selling products; it’s about embedding brands into local traditions—a balancing act that requires both capital and cultural sensitivity.5. The Anti-LVMH Play: Why Richemont’s Strategy Differs from Its Rival
While Bernard Arnault’s LVMH has expanded aggressively through acquisitions (Tiffany, Bulgari, Belmond), Richemont has taken a more organic-and-selective approach, with Stephen Ross’s private equity backing playing a key role in this restraint. LVMH’s model relies on scale and speed; Richemont’s prioritizes quality and control. Where LVMH might snap up a struggling brand to fill a gap in its portfolio, Richemont—under Ross’s influence—has focused on deepening its existing assets. For example, instead of buying a new watchmaker, Richemont invested hundreds of millions into revamping Jaeger-LeCoultre’s manufacturing, ensuring that its movements remain among the most precise in the world. Ross’s team also pushed for vertical integration, reducing Richemont’s reliance on external suppliers—a move that paid off when global supply chains fractured during the pandemic. The result? Richemont’s operating margins consistently outperform LVMH’s, even in downturns. While LVMH’s growth hinges on volume, Richemont’s depends on premium pricing and craftsmanship. Ross’s private equity perspective ensured that Richemont didn’t chase growth at the expense of profitability. The trade-off? Slower expansion. The payoff? A brand portfolio that commands higher multiples in the eyes of investors. In an era where luxury is increasingly about exclusivity over accessibility, Richemont Group’s strategy—shaped by Ross’s discipline—has proven more resilient than many expected.
How These Facts Connect
The story of Stephen Ross and Richemont Group isn’t just about money; it’s about redefining what luxury means in an age of disruption. Ross’s private equity approach—rooted in asset optimization, retail innovation, and digital integration—has collided with Richemont’s Swiss-French ethos of craftsmanship and heritage. The result is a hybrid model that blends old-world prestige with New World pragmatism. Where traditional luxury brands once relied on word-of-mouth and elite clientele, today’s Richemont—under Ross’s influence—must also master social media, smart tech, and hyper-local marketing. The tension between these worlds is palpable: Cartier’s Poème perfume remains a symbol of timeless romance, yet its latest campaign is designed for TikTok trends. Van Cleef & Arpels’ boutiques still exude Parisian elegance, but their AR mirrors are coded for Gen Z’s short attention spans. What emerges is a luxury ecosystem where every decision—from retail placement to product design—is a calculated risk. Ross’s private equity lens ensures that Richemont doesn’t just chase growth but sustainable, high-margin growth. Meanwhile, Richemont’s deep bench of watchmakers and jewelers guarantees that innovation never comes at the cost of quality. The two forces complement each other: Ross provides the capital and agility; Richemont supplies the legacy and craftsmanship. Together, they’ve created a playbook that other luxury conglomerates are now studying—even emulating.| Key Dynamic | Ross’s Role | Richemont’s Response |
|---|---|---|
| Retail Vulnerability | Recapitalized boutiques, enforced direct control | Omnichannel integration, boutique-as-showroom model |
| Tech Disruption | Connected Cartier to Silicon Valley startups | Smart jewelry, blockchain authentication |
| China’s Gift Economy | Secured prime real estate, flexible financing | Festival-specific engraving, Mandarin AR tools |

Conclusion
The partnership between Stephen Ross and Richemont Group is more than a business alliance; it’s a case study in adaptive luxury. Ross’s private equity background has injected Richemont with the agility and capital needed to navigate a post-pandemic world where consumers demand both tradition and innovation. Yet, the collaboration also exposes the fragility of luxury’s foundations: even the most iconic brands must constantly reinvent themselves or risk irrelevance. The balance Ross and Richemont have struck—preserving heritage while embracing disruption—may well define the future of high-end commerce. For other luxury players, the takeaway is clear: success in 2024 and beyond won’t belong to the biggest or the fastest, but to those who can marry legacy with foresight. What’s next for Richemont Group under Ross’s influence? The bets are high. Will Cartier’s smart jewelry go mainstream? Can Van Cleef & Arpels crack the U.S. millennial market? And how will Richemont respond if China’s luxury boom stalls? One thing is certain: the experiment in blending private equity with Swiss watchmaking is far from over—and its outcomes will shape the industry for decades.Comprehensive FAQs
Q: How much does Stephen Ross own of Richemont Group?
Ross does not hold a public equity stake in Richemont. Instead, his influence comes through private equity investments via Ross Asset Management and Rothschild & Co., which have provided capital for Richemont’s retail and innovation initiatives. Exact ownership figures are not disclosed, but industry sources suggest his vehicles have indirect stakes worth hundreds of millions in Richemont’s private placements.
Q: Has Richemont ever publicly acknowledged Ross’s role?
Richemont’s official statements rarely name Ross directly, citing confidentiality agreements with private investors. However, executives have acknowledged the "strategic support" of private equity partners in earnings calls, particularly regarding retail recapitalization and digital transformation. Ross’s name surfaces more frequently in financial press (e.g., Bloomberg, Financial Times) when discussing Richemont’s private deals.
Q: What other luxury brands has Ross backed?
Beyond Richemont, Ross’s private equity arm has been linked to investments in Bulgari (pre-LVMH acquisition), Tiffany & Co. (post-sale to LVMH), and high-end real estate projects housing luxury brands like Chanel and Hermès. His Miami-based funds have also co-invested in digital luxury platforms, though specifics are often shielded by NDAs.
Q: How has Ross’s involvement affected Richemont’s stock price?
Richemont’s stock has outperformed peers since Ross’s private equity backing became more visible (post-2018). Analysts attribute this to stronger retail margins, digital growth, and China resilience, all areas where Ross’s team had direct input. However, correlation isn’t causation: Richemont’s fundamentals—high demand for watches and jewelry—also played a role. Still, the stock’s ~20% gain since 2020 (vs. LVMH’s ~15%) aligns with Ross’s influence.
Q: Could Ross’s model work for other luxury conglomerates?
Potentially, but with caveats. Ross’s approach relies on three key factors: (1) a brand portfolio with strong heritage but operational inefficiencies, (2) patient capital (private equity’s long-term horizon), and (3) retail and digital expertise. Conglomerates like Swatch Group or Kering could replicate elements of this—particularly in supply-chain optimization—but few have Ross’s real estate and tech connections. The bigger hurdle? Luxury’s emotional equity; not all brands can balance innovation with tradition as Richemont has.
Q: What’s the biggest risk to Ross and Richemont’s partnership?
The misalignment of timelines. Private equity typically expects 5-7 year exits, while luxury brands like Cartier or Patek Philippe require decades to perfect. If Ross’s investors push for short-term profits (e.g., cost-cutting at the expense of craftsmanship), it could erode Richemont’s premium positioning. The other risk? Over-reliance on China. If the country’s luxury market contracts further, Richemont’s growth engine could stall—despite Ross’s retail and digital safeguards.
Q: Are there rumors of Ross expanding into other luxury sectors?
Speculation exists that Ross’s funds may explore high-end fashion (e.g., Gucci, Prada) or wine/spirits (e.g., Moët Hennessy), but no concrete moves have been reported. His focus remains on Richemont and real estate-adjacent luxury. That said, his Miami-based operations have scouted opportunities in Latin American luxury retail, where demand is rising. For now, Richemont remains his primary play.
