Where It All Began
Robert Kiyosaki’s rise to prominence wasn’t the result of a single stroke of genius. It was the product of a carefully crafted narrative, one that blended personal myth with financial philosophy. Born in 1947 on the island of Hawaii, Kiyosaki grew up in a middle-class family where his biological father—a strict educator—represented the "poor dad" of his later teachings. The contrast with his mother’s side of the family, where an uncle embodied the "rich dad" ethos, became the foundation of his bestselling book. But the story, as he told it, was more than just a parable. It was a blueprint. By the late 1980s, Kiyosaki had already dabbled in real estate, though his early ventures were modest compared to what would come. His real breakthrough came in the 1990s, when he leveraged his growing fame as a financial educator to launch seminars and multimedia courses. The timing was perfect: the dot-com boom had created a class of aspirational entrepreneurs, hungry for shortcuts to wealth. Kiyosaki’s message—"wealth is a game, and the rules are simple"—resonated. His books, particularly Rich Dad Poor Dad (1997), became cultural touchstones, selling millions of copies and cementing his status as a self-help icon. The early signs of trouble were subtle at first. Kiyosaki’s business model relied heavily on real estate, a sector where leverage could amplify both gains and losses. By the early 2000s, he had expanded aggressively, acquiring properties not just in Hawaii but across the U.S. His company, RICH Global LLC, was a sprawling operation, with ventures in education, media, and even a failed attempt at a financial news network. The problem? Many of these deals were funded with debt, a strategy that worked as long as property values kept rising. When they didn’t, the cracks began to show.The Early Signs
Kiyosaki’s first major stumble came in 2005, when his company, RICH Global, faced a lawsuit from a former business partner over unpaid debts. The case dragged on for years, draining resources and damaging his reputation. Meanwhile, his real estate portfolio was becoming a liability. In Hawaii alone, he reportedly owed millions in back taxes and unpaid mortgages. The situation worsened when the financial crisis of 2008 hit. Property values collapsed, and Kiyosaki’s heavily leveraged assets became albatrosses around his neck. What made the situation even more ironic was Kiyosaki’s public stance on debt. For years, he had argued that the wealthy used other people’s money to build wealth, while the middle class was trapped by debt. Yet his own financial house was built on the very debt he criticized. The contradiction wasn’t lost on his critics, who accused him of hypocrisy. But Kiyosaki had always been a master of narrative control. Even as his empire teetered, he framed his struggles as part of a larger lesson—one that would ultimately make him more credible.The Turning Point
The breaking point came in 2009, when Kiyosaki’s financial troubles became undeniable. Reports surfaced that he had filed for personal bankruptcy, though the exact details remained murky. Unlike corporate bankruptcy, which can be managed behind closed doors, personal bankruptcy is a public record. For Kiyosaki, this was a PR nightmare. Overnight, the man who had built a career on teaching others how to avoid financial ruin was now a bankrupt entrepreneur. The turning point wasn’t just financial—it was psychological. Kiyosaki had spent decades positioning himself as an infallible guru, the man who had cracked the code on wealth. But bankruptcy forced him to confront a harsh truth: no one is immune to failure. His response was telling. Instead of disappearing into obscurity, he doubled down. He admitted his mistakes in interviews, but he also doubled down on his core message. If anything, he argued, his bankruptcy made him more relatable. The man who had once been untouchable was now just another student of the game—one who had learned the hard way."Bankruptcy is not the end. It’s a lesson. The difference between the rich and the poor is that the rich fail upward, while the poor fail downward." — Robert Kiyosaki, 2010The quote became a mantra for his followers, a way to reframe his collapse as a necessary step toward greater success. But the reality was more complicated. While Kiyosaki’s personal finances may have stabilized, his business empire was far from secure. Lawsuits continued, and his real estate holdings were still a burden. Yet, in the world of self-help, failure can be just as powerful as success—if you know how to spin it.

The Build-Up, Year by Year
| Period | What Happened / What Changed | |------------------|------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------| | 2005–2007 | Lawsuits against RICH Global LLC escalate. Kiyosaki’s real estate portfolio begins to underperform as market conditions shift. Early signs of financial strain emerge, though publicly, he remains optimistic. | | 2008–2009 | The financial crisis hits. Property values plummet, and Kiyosaki’s heavily leveraged assets become liabilities. Reports surface of unpaid debts and tax issues in Hawaii. He files for personal bankruptcy, a rare public admission of failure. | | 2010–2012 | Kiyosaki pivots to digital media, launching online courses and a financial news network. While his personal finances stabilize, his business model remains vulnerable to market fluctuations. Critics question his authenticity. | | 2013–Present| Kiyosaki’s brand rebounds, fueled by social media and a renewed focus on cryptocurrency and real estate investing. His net worth recovers, though exact figures remain speculative. His bankruptcy is now framed as a "lesson" in resilience. |Lessons From the Journey
- Leverage is a double-edged sword. Kiyosaki’s reliance on debt worked as long as markets rose—but when they fell, his empire collapsed. The lesson? Even the most disciplined investors must plan for downturns.
- Public perception is everything. His bankruptcy could have destroyed his career, but by reframing it as a "necessary reset," he turned a liability into a teaching moment.
- Authenticity matters more than perfection. Admitting failure didn’t kill his brand; it made it more human. Many followers now see him as a "real" teacher, not just a guru.
- Real estate is cyclical. His Hawaii properties were his greatest asset—and his biggest vulnerability. Diversification, he now argues, is key to long-term survival.
- Bankruptcy isn’t the end—if you survive it. Kiyosaki’s ability to reinvent himself post-collapse is a masterclass in resilience, though not everyone has the resources to do the same.
Where Things Stand Today
A decade after his bankruptcy, Robert Kiyosaki’s financial standing is a study in contradiction. On paper, he appears to have recovered. His net worth, while never officially disclosed, is estimated to be in the tens of millions—far from the hundreds of millions he claimed in his peak years. His books continue to sell, his seminars draw crowds, and his social media following remains strong. Yet the scars of his collapse are still visible. The real estate market has rebounded, but Kiyosaki’s empire is no longer the monolithic machine it once was. His Hawaii properties, once a source of pride, are now a fraction of their former value. His media ventures have come and gone, leaving behind a mixed legacy. And while he still preaches the gospel of financial independence, his own journey is a reminder that even the most disciplined minds can stumble. The question now isn’t whether Kiyosaki will recover—it’s whether his lessons still hold water in a world where debt, leverage, and risk are more complex than ever.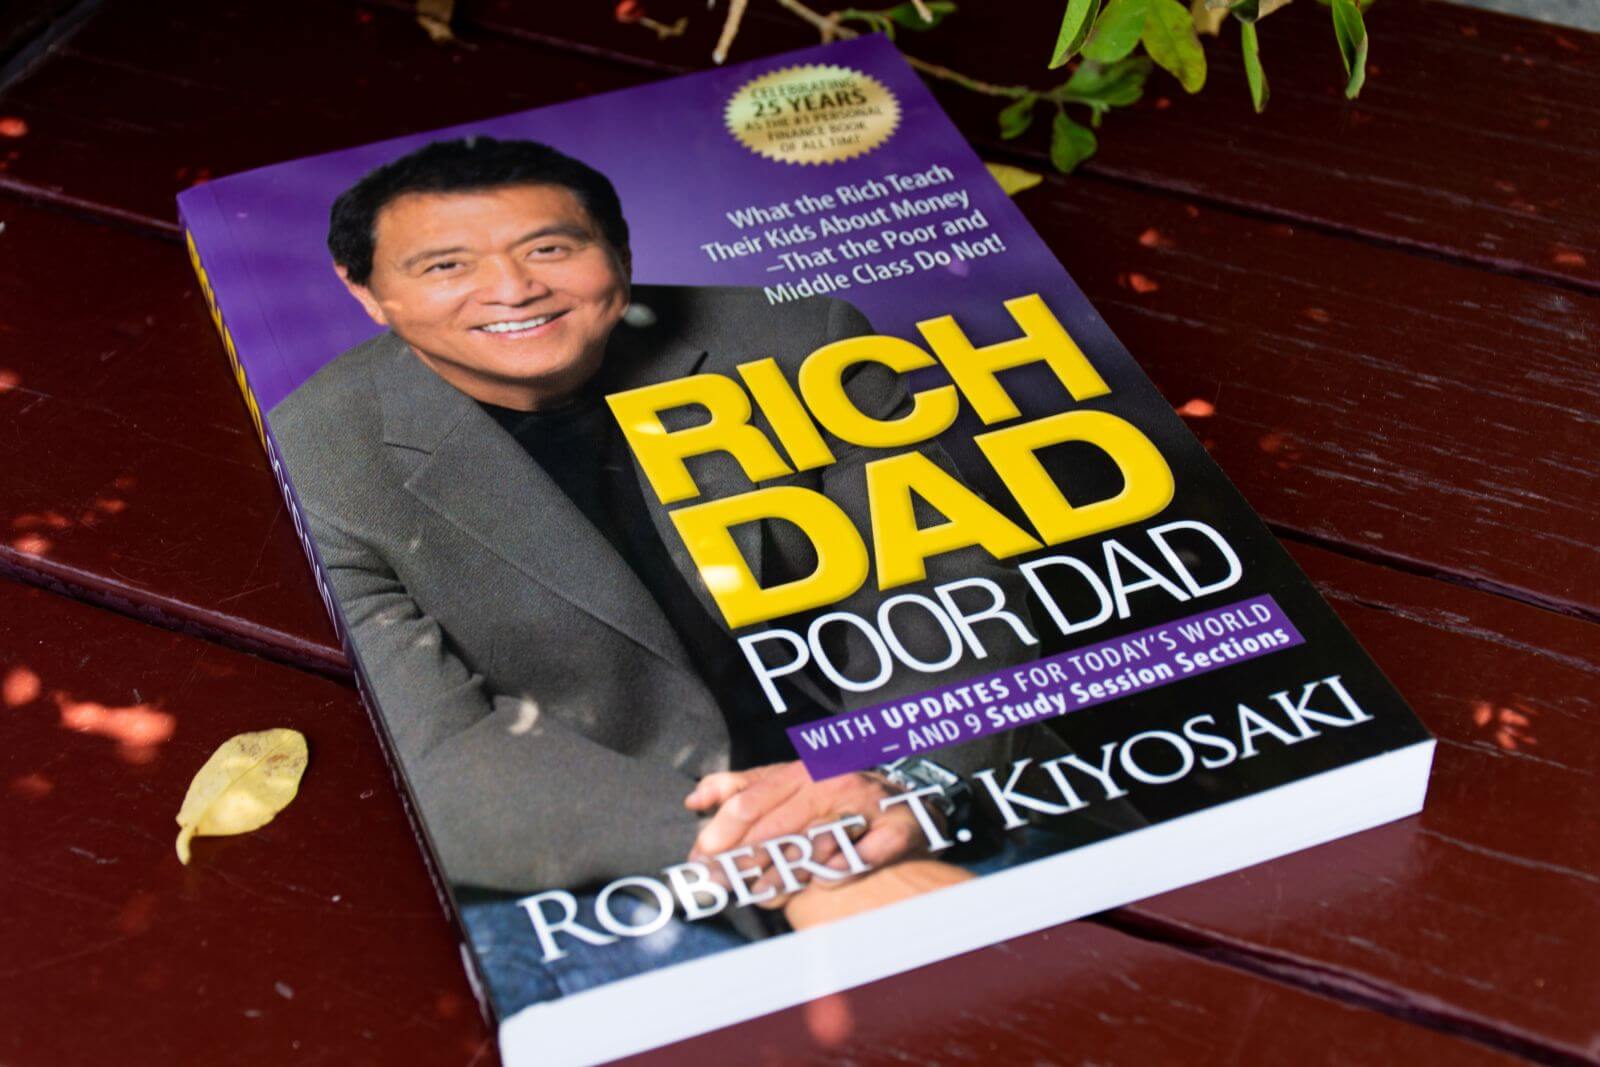
Conclusion
Robert Kiyosaki’s bankruptcy is more than just a footnote in the story of a self-help guru. It’s a case study in the fragility of empire, the power of narrative, and the fine line between genius and hubris. His collapse didn’t destroy him—it reshaped him. And in doing so, it forced his followers to confront an uncomfortable truth: wealth isn’t just about strategy; it’s about survival. The irony of Kiyosaki’s story is that his greatest lesson may be the one he learned the hardest. Bankruptcy, he now argues, isn’t a failure—it’s a rite of passage for those who dare to play the game. But for every success story that emerges from the ashes, there are others who never recover. Kiyosaki’s ability to reinvent himself post-collapse is a testament to his resilience—but it’s also a reminder that luck, timing, and public perception play just as big a role as skill.Comprehensive FAQs
Q: Did Robert Kiyosaki really go bankrupt?
Yes. In 2009, Kiyosaki filed for personal bankruptcy, a rare public admission of financial distress for someone who had spent decades teaching others how to avoid it. While the exact details remain private, court records confirm the filing, and his own statements have acknowledged the struggles of his real estate empire at the time.
Q: How much money did he lose in the bankruptcy?
Exact figures are unclear, but industry estimates suggest his net worth dropped from hundreds of millions to a fraction of that. His Hawaii properties, once valued in the tens of millions, became liabilities. While he has since rebuilt his wealth, the collapse was severe enough to force a reset in his business model.
Q: Did his bankruptcy hurt his career?
Initially, yes. Critics accused him of hypocrisy, and some followers distanced themselves. However, Kiyosaki pivoted by framing the bankruptcy as a "lesson," which actually strengthened his brand. Many saw it as proof that he was "real"—a teacher who had faced failure and survived.
Q: What did he do differently after the bankruptcy?
He shifted focus from real estate to digital media, launching online courses and a financial news network. He also doubled down on his core message, arguing that bankruptcy was a necessary step for true wealth builders. His social media presence grew, helping him rebuild his audience.
Q: Is he still teaching the same things today?
Mostly, but with more emphasis on risk management. While he still advocates for leverage and entrepreneurship, his post-bankruptcy teachings include stronger warnings about market cycles and the importance of diversification. His recent focus on cryptocurrency also reflects a shift toward higher-risk, higher-reward assets.
Q: Could someone replicate his comeback?
In theory, yes—but the conditions are rare. Kiyosaki had an established brand, a loyal following, and the ability to reframe failure as a teaching moment. Most entrepreneurs don’t have those advantages. His story is more about resilience than replicability.
Q: What’s the biggest misconception about his bankruptcy?
The idea that it was a one-time mistake. In reality, his financial struggles were the result of years of overleveraging and aggressive expansion. His bankruptcy wasn’t just a setback—it was the culmination of a business model that had outpaced his risk management.
