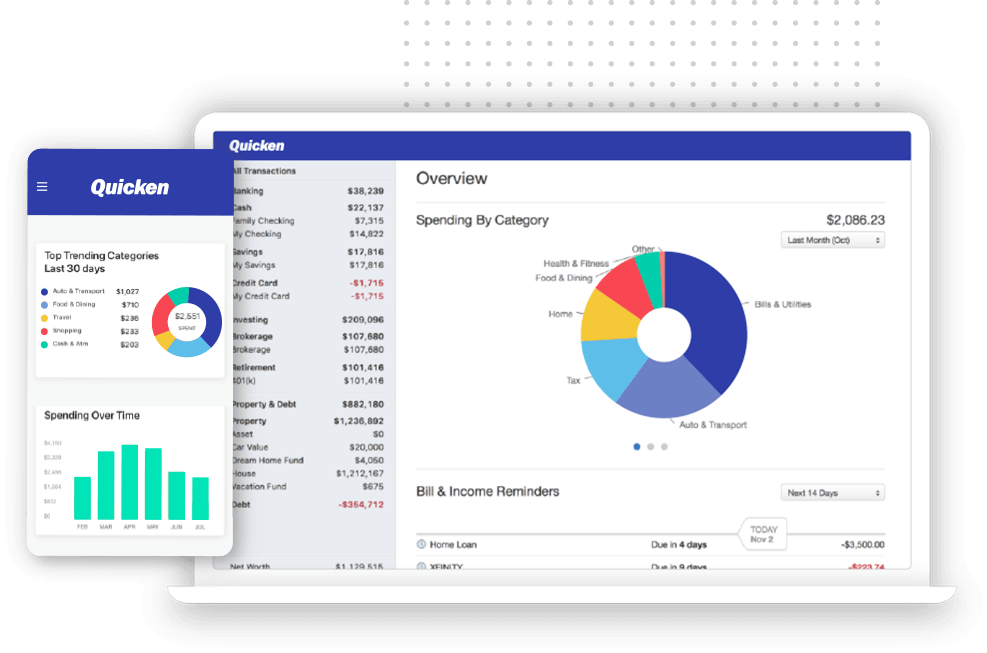
Common Myths About Quicken + Net Worth + Filter
The first misconception is that Quicken’s net worth calculations are generic. In truth, the platform allows for custom weightings—users can assign different importance to assets (e.g., a primary residence might carry more weight than a side hustle’s savings). This flexibility is critical for those with complex portfolios, where standard net worth formulas (assets minus liabilities) oversimplify reality. Another persistent myth is that filters are limited to basic categories. Advanced users leverage conditional filters to exclude short-term debt from net worth calculations or to track only assets generating passive income. The platform’s scripting capabilities (via Quicken’s "Rules" feature) let users automate these filters, ensuring net worth updates reflect their specific priorities—not just Quicken’s defaults.Myth 1: Net worth tracking in Quicken is one-size-fits-all
The reality is that Quicken’s net worth engine is modular. Users can redefine what constitutes an "asset" or "liability." For example, a freelancer might classify their equipment as an asset, while a homeowner could treat a rental property’s mortgage as a semi-liability (since it generates income). The filter system then adapts to these classifications, ensuring the net worth figure aligns with the user’s financial strategy. This customization extends to time-based filters. A user might set a filter to show net worth growth only during quarters when they contributed to retirement accounts. Without this granularity, the net worth metric risks becoming a vanity number—useless for decision-making.Myth 2: Filters only work for simple debt/asset splits
Quicken’s filters are far more sophisticated. They can parse transactions by account type, date range, or even custom tags. A user tracking their net worth might filter out all credit card transactions older than six months, focusing solely on recent cash flow. Alternatively, they could isolate investments in a specific ETF to see how that segment contributes to overall growth. The platform’s "Where’s My Money Going?" report, when combined with net worth filters, reveals hidden patterns. For instance, a filter might show that 60% of net worth growth comes from a single asset class—prompting a rebalancing decision. This level of detail is why Quicken is favored by those who treat net worth as a dynamic tool, not a static snapshot.Myth 3: Automated net worth updates are unreliable
Automation in Quicken is only as good as the data it ingests. The platform’s net worth calculations are reliable when paired with accurate transaction categorization. Users who manually review and adjust categories (e.g., reclassifying a bonus as an asset) ensure filters reflect true financial health. The alternative—ignoring discrepancies—leads to skewed net worth figures, undermining the tool’s utility. That said, Quicken’s error-checking tools (like duplicate transaction alerts) mitigate risks. When used correctly, automated net worth updates become a force multiplier for financial clarity. The key is balancing automation with periodic manual audits, especially for assets like real estate or private equity that don’t sync seamlessly with bank feeds.
What Holds Up to Scrutiny
At its core, Quicken’s net worth + filter system excels in three areas: 1. Precision in asset/liability segmentation—users can exclude non-core liabilities (e.g., a medical bill) from net worth calculations. 2. Trend analysis—filters enable year-over-year comparisons, isolating factors like inflation or market volatility. 3. Integration with third-party data—users can pull in external valuations (e.g., for a side business) to refine net worth accuracy. The platform’s strength lies in its ability to turn net worth from a passive metric into an active one. A user might set a filter to trigger alerts when net worth dips below a threshold, or when a specific asset class grows beyond a target percentage. This proactive approach is rare in personal finance tools."Quicken’s net worth filters aren’t just about numbers—they’re about financial storytelling. A filter can reveal whether your net worth growth is driven by income, asset appreciation, or debt reduction. That context changes everything." — Sarah Johnson, Certified Financial Planner (CFP)
| Common Belief | What the Evidence Says |
|---|---|
| Net worth filters are only for advanced users. | Basic filters (e.g., excluding a car loan) are accessible to beginners, while advanced users leverage scripting for custom rules. |
| Quicken’s net worth is less accurate than manual calculations. | When properly configured, Quicken’s automated syncs and user-adjustable categories often match or exceed manual precision. |
| Filters slow down performance. | Quicken’s cloud-based processing handles filters efficiently, even for large portfolios. |
| Net worth tracking is only useful for retirement planning. | Filters enable use cases like tracking liquidity for emergencies, monitoring generational wealth transfers, or assessing business valuation. |
Why the Confusion Persists
Part of the issue is Quicken’s dual identity—it’s both a consumer tool and a professional-grade platform. Beginners see basic budgeting features and assume net worth tracking is equally simplistic. Meanwhile, power users dive into filters without documenting how to set them up for others. The lack of standardized tutorials exacerbates the problem. Another factor is the psychology of financial data. Users often focus on the net worth number itself rather than the filters that shape it. A $500,000 net worth might look impressive until a filter reveals that $300,000 of it is tied up in an illiquid asset. Quicken’s strength is in exposing these nuances—but only if users engage with the tool’s full capabilities.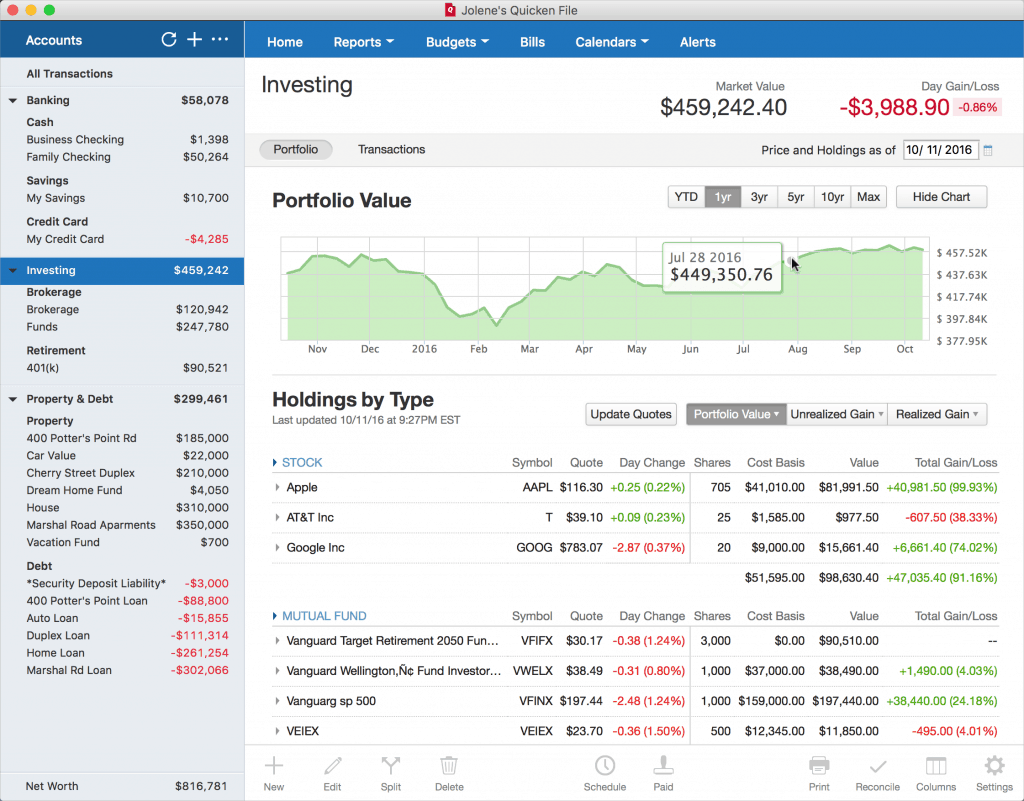
Conclusion
Quicken’s net worth + filter combination is a testament to how software can reflect individual financial strategies. The platform’s power isn’t in replacing human judgment but in amplifying it—whether by isolating assets for tax planning or flagging debt that’s dragging down net worth. The key is treating filters as tools for discovery, not just crunching numbers. For those who master this synergy, Quicken becomes more than a ledger. It’s a financial operating system—one that adapts to goals, not the other way around.Comprehensive FAQs
Q: Can Quicken’s net worth filters be used for business accounting?
A: Yes, but with limitations. Quicken is designed for personal finance, so business-specific filters (e.g., separating capital expenditures from operating costs) require manual categorization. For full business accounting, tools like QuickBooks or Xero are better suited.
Q: How often should I update my net worth filters?
A: At least quarterly, or whenever your financial situation changes (e.g., new investments, loans, or asset sales). Automated syncs handle daily updates, but filters should be reviewed to ensure they align with your current priorities.
Q: Do Quicken’s net worth filters work with cryptocurrency?
A: Indirectly. Quicken doesn’t natively support crypto wallets, but users can manually log transactions and apply filters to track holdings as a separate asset class. Third-party plugins (like CoinTracker) can streamline this process.
Q: Can I share filtered net worth reports with a financial advisor?
A: Yes, via Quicken’s export features (PDF, CSV). Advisors often prefer reports that exclude short-term liabilities or highlight specific asset classes—filters make this easy. Just ensure the data is anonymized if sharing sensitive details.
Q: What’s the best way to set up a "liquidity-focused" net worth filter?
A: Start by categorizing assets as liquid (cash, investments) or illiquid (real estate, collectibles). Then create a filter to show only liquid assets minus high-priority liabilities (e.g., credit cards). Adjust the timeframe to match your liquidity needs (e.g., 6 months vs. 2 years).
Q: How does Quicken handle net worth calculations for married couples?
A: Quicken treats net worth as an individual metric by default, but users can merge accounts (e.g., joint savings) and apply shared filters. For separate tracking, create two profiles and use Quicken’s "Family View" to compare combined net worth trends.
Q: Are there any hidden costs to using advanced filters?
A: No direct costs, but complex filters may require Quicken’s premium subscription ($10–$15/month) for full functionality. The trade-off is access to advanced reporting and scripting tools that simplify management.
