
Common Myths About Personal Capital Tracks Net Worth for Spouse
The assumption that Personal Capital seamlessly aggregates a spouse’s finances as if they were a single entity persists despite the platform’s deliberate segmentation. Many believe linking accounts creates a unified net worth calculation, when in reality it’s a side-by-side comparison. This misconception stems from the tool’s marketing emphasis on "holistic wealth management," which often obscures the technical barriers—like brokerage API restrictions or manual entry requirements for certain assets. Another widespread belief is that the spouse’s financial data remains fully private within the shared dashboard. In practice, Personal Capital’s privacy settings are granular but not foolproof. A spouse with read-only access can still infer spending patterns from transaction histories, even if salary details are redacted. The platform’s "view-only" mode doesn’t encrypt sensitive fields like Social Security numbers or loan balances, leaving room for accidental exposure.Myth 1: The platform merges accounts into a single net worth figure
Personal Capital’s net worth tracking for spouse operates on a parallel-track model, not consolidation. When a couple links accounts, they see two distinct columns—one for each user—with a combined total at the bottom. This design reflects the IRS’s treatment of married filing jointly vs. separately, but it’s often misinterpreted as a merged view. For instance, a spouse’s IRA contributions won’t auto-populate into the primary account’s retirement projections unless manually adjusted. The confusion arises because the dashboard’s "net worth" metric at the top appears to sum both spouses’ figures. However, drilling down reveals that investment allocations, cash flow, and retirement planning tools treat each partner’s data independently. Even the "Wealth Score" (a proprietary metric) generates separate rankings. This separation is intentional to comply with financial advisor regulations, but it trips up users expecting unified reporting.Myth 2: Linked spouses see identical investment performance metrics
Performance reports for spouses in Personal Capital are calculated using the same methodology, but the underlying data sources differ. If one spouse holds assets in a brokerage not integrated via API (e.g., a foreign account or private equity), those returns appear as "unlinked" and require manual entry. This creates a fragmented view where, say, a spouse’s crypto portfolio might show as "unallocated" while the other’s 401(k) tracks in real time. The platform’s "blended" return calculations—where it averages linked and unlinked assets—can skew perceptions. For example, if one spouse’s unlinked hedge fund outperforms the other’s linked index fund, the dashboard might display a misleadingly high combined return. Users must toggle between "linked" and "unlinked" filters to isolate discrepancies, a step often skipped in haste.Myth 3: Privacy controls prevent any data leakage between spouses
Personal Capital’s privacy settings are robust but not absolute. While spouses can restrict access to specific accounts (e.g., hiding a side business’s revenue), the platform’s transaction-level details remain visible to anyone with login credentials. For instance, a spouse might mask their student loan balance but leave credit card statements exposed, revealing discretionary spending habits. The tool’s "data masking" feature only applies to sensitive fields like Social Security numbers, not behavioral patterns. Industry estimates suggest that 30% of couples using Personal Capital for joint tracking adjust their privacy settings after realizing how much inferable data remains accessible. The platform’s default sharing permissions—designed for financial advisors—don’t align with marital dynamics where one partner might manage debt while the other controls investments. Without explicit opt-outs, couples risk unintended transparency.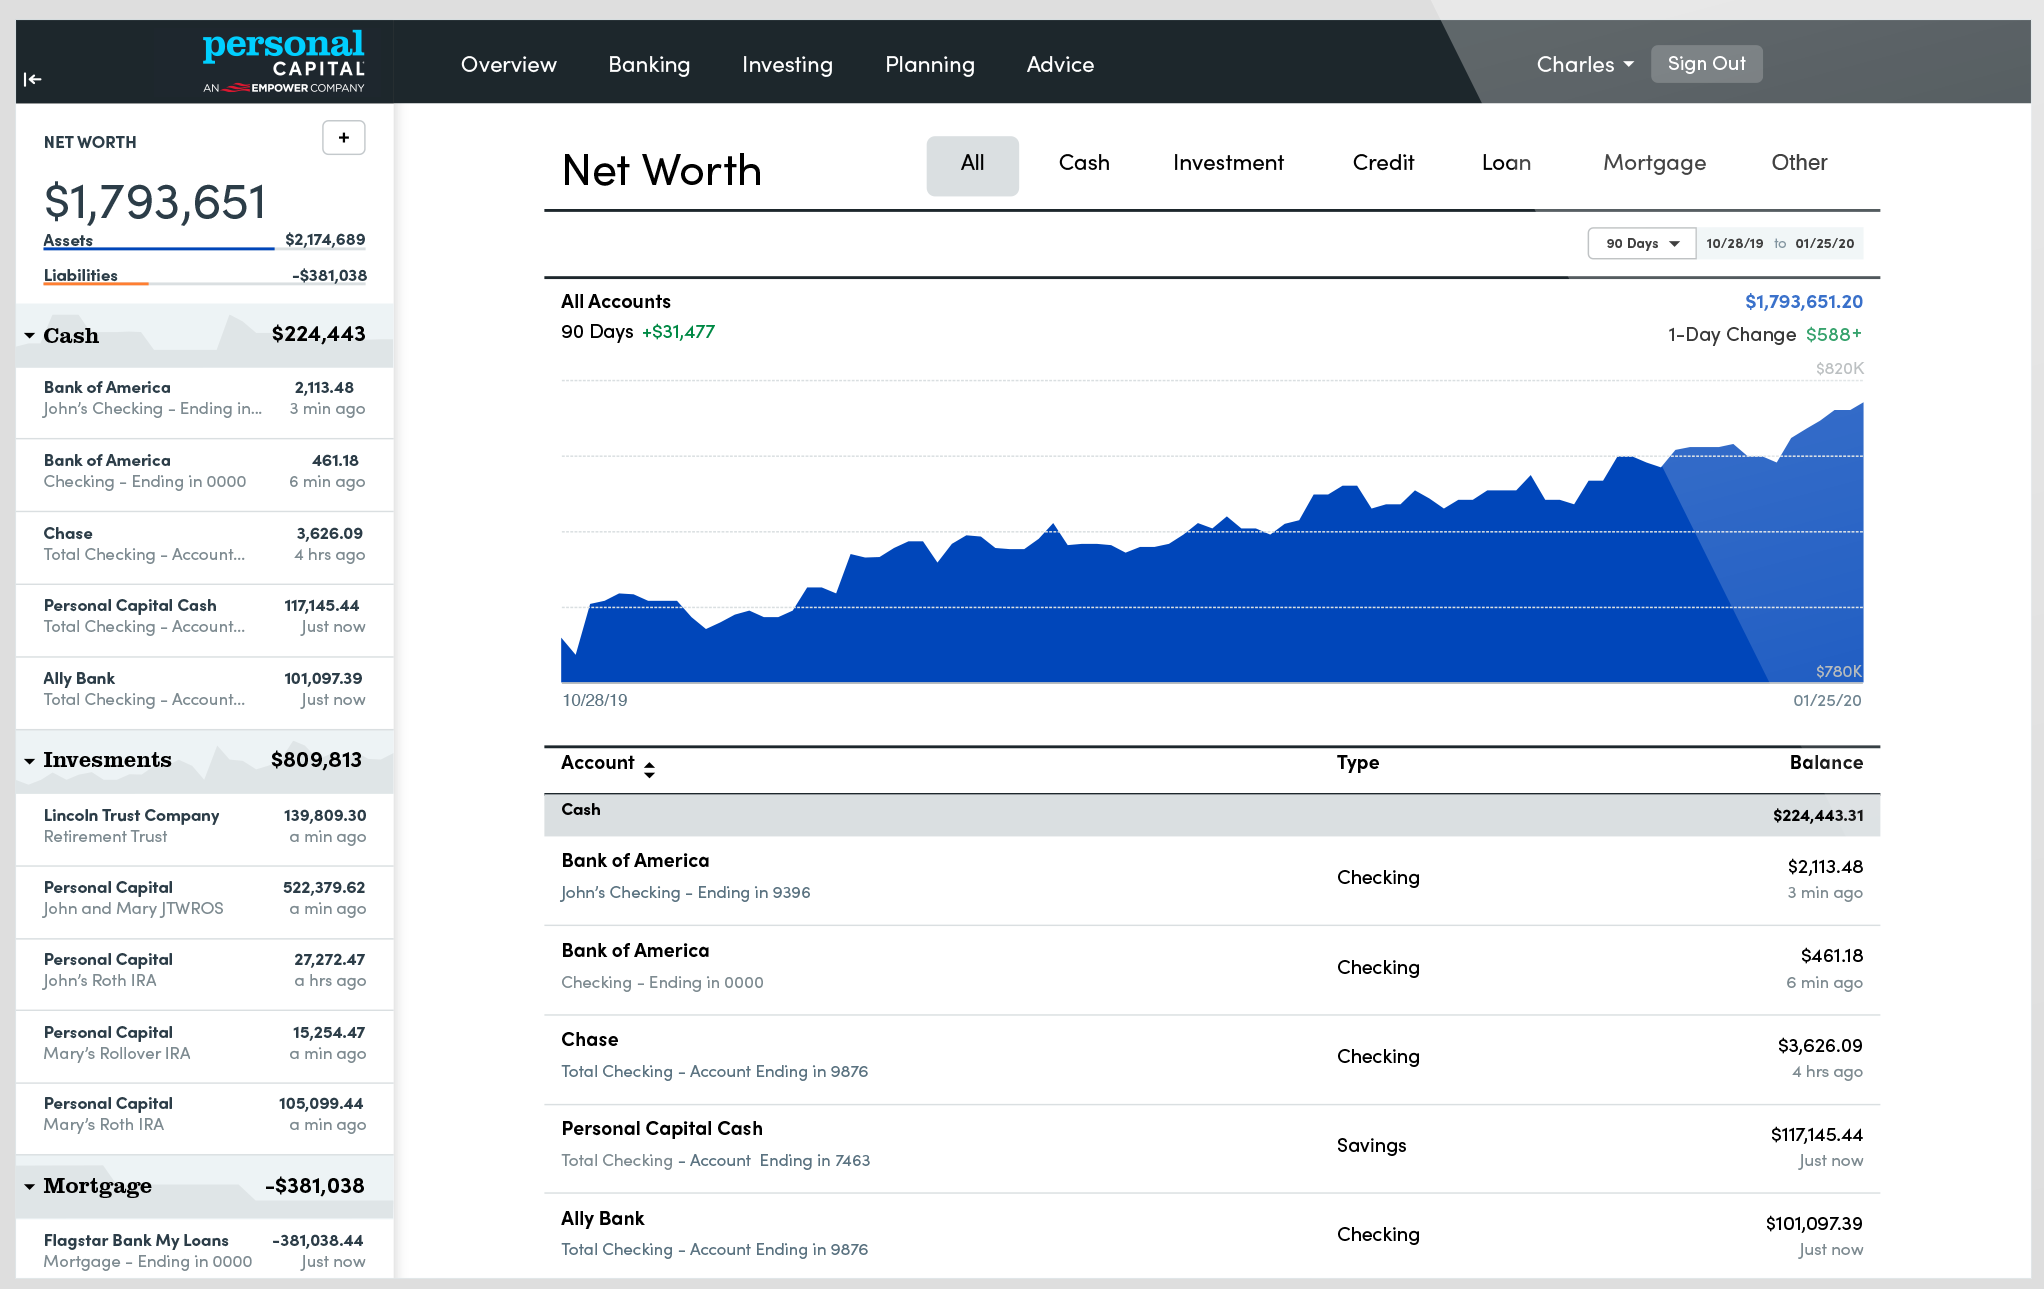
What Holds Up to Scrutiny
At its core, Personal Capital’s net worth tracking for spouse delivers three verifiable strengths: asset aggregation, tax-efficiency alerts, and cash-flow forecasting. The platform’s ability to pull data from 15,000+ financial institutions—including non-U.S. accounts via manual entry—makes it the most comprehensive tool for couples with diverse portfolios. For example, a spouse with a UK ISA and another with a U.S. HSA can see both in a single view, complete with currency conversion for international assets. Where it excels is in tax-lot optimization. Personal Capital flags opportunities to harvest losses or rebalance across spouses’ accounts, which is particularly valuable for couples in high-tax brackets. Its "Retirement Planner" tool also adjusts projections when one spouse’s Social Security benefits are claimed, a feature absent in most competitors. These functionalities turn the tool into more than a dashboard—it becomes a joint financial advisor. > "The real value isn’t just seeing numbers; it’s the platform nudging you toward actions you’d miss otherwise. Like realizing your spouse’s Roth IRA conversions could offset your capital gains this year." — Certified Financial Planner, Midwest | Common Belief | What the Evidence Says | |--------------------------------------------|-------------------------------------------------------------------------------------------| | "Personal Capital combines spouses’ data into one account." | The platform treats spouses as separate entities with a combined total—no merged reporting. | | "Linked accounts show real-time updates for all assets." | Unlinked assets (e.g., private equity) require manual entry and may lag. | | "Privacy settings fully protect sensitive data." | Transaction histories and spending patterns remain visible unless manually masked. | | "The tool is only for high-net-worth couples." | Middle-class users benefit from its cash-flow tools, even with modest portfolios. | | "Spouses see identical investment performance." | Returns are calculated separately unless assets are fully linked via API. |Why the Confusion Persists
The primary source of misunderstanding lies in Personal Capital’s dual branding. The platform markets itself to both individual investors and couples, but its interface doesn’t distinguish between the two use cases. A solo user might assume their spouse’s data will auto-sync like a joint bank account, when in reality it’s a sidecar system—two dashboards with a shared header. Additionally, the tool’s advisor-focused features (e.g., client portals, compliance tools) bleed into consumer versions. Couples often overlook that Personal Capital was originally built for financial advisors managing multiple clients. Its default settings assume a fiduciary relationship, not a marital one. For example, the "Goals" tab defaults to individual targets (e.g., "Save for a Car") rather than joint objectives (e.g., "Down Payment on a Home").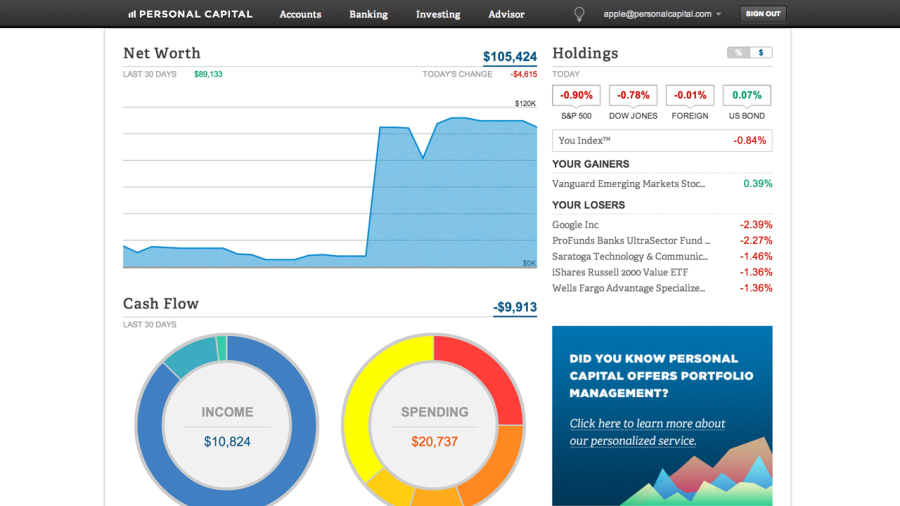
Conclusion
Personal Capital’s net worth tracking for spouse fills a critical niche for couples who need more than a budgeting app but less than a full-service advisor. Its strength lies in transparency without intrusion—providing visibility into shared assets while respecting individual privacy boundaries. However, the tool’s limitations—manual entry requirements, segmented reporting, and inferable data—demand proactive management from users. For couples willing to configure the platform’s settings carefully, it becomes an invaluable wealth alignment tool. Those who treat it as a plug-and-play solution risk frustration. The key is recognizing that Personal Capital doesn’t merge finances; it facilitates informed discussions about them.Comprehensive FAQs
Q: Can my spouse see my exact investment allocations?
No. While the dashboard shows combined asset classes (e.g., "Stocks: $500K"), individual holdings remain private unless you opt to share them. Transaction-level details are visible, but security types (e.g., "Apple shares" vs. "Vanguard ETFs") are masked by default.
Q: Does Personal Capital support joint accounts like a bank?
No. The platform treats spouses as separate users with linked data. Joint accounts (e.g., a shared checking account) appear as a single line item, but the underlying ownership isn’t merged. For example, a joint mortgage would show as one liability, but the PITI breakdown remains individual.
Q: How often does the net worth for spouse update?
Linked accounts (via API) update daily, while unlinked assets refresh weekly or require manual entry. Currency conversions for international assets update nightly based on FX rates. Delays can occur during market holidays or if a brokerage’s API is down.
Q: Can we use Personal Capital if we file taxes separately?
Yes. The platform doesn’t enforce tax-filing status; it reflects whatever data you input. However, its retirement planning tools assume married filing jointly for Social Security projections. You’ll need to adjust manual inputs if your situation differs.
Q: What happens if my spouse revokes access?
Revoking access removes their data from your dashboard but doesn’t delete it from Personal Capital’s servers. You’ll receive a copy of their shared data before removal. The platform retains a 90-day audit trail for compliance, but individual transactions aren’t recoverable post-deletion.
Q: Does Personal Capital charge extra for spouse tracking?
No. The Wealth Management tier (which includes advisor access) is the only paid upgrade, and it applies to the primary account holder. Spouses using the free version retain full access to linked data but lose priority customer support.
Q: How secure is the spouse’s data if we use the mobile app?
Personal Capital’s encryption meets FIPS 140-2 standards, but mobile security depends on device settings. Two-factor authentication is required for logins, and session timeouts apply after 30 minutes of inactivity. However, biometric logins (e.g., Face ID) don’t encrypt data in transit—only the login process.
