
Breaking Down the Numbers
The percent household net worth isn’t a single figure but a spectrum, measured against national or regional benchmarks. For instance, the U.S. Census Bureau’s data shows that in 2022, the median net worth for white households was $188,200, compared to $48,500 for Black households—a disparity that persists even when controlling for income. This isn’t just a racial divide; it’s a generational one. Millennials, despite higher student debt burdens, report a median net worth of $92,300, while Gen Xers sit at $188,200. The percent household net worth metric reveals how these cohorts stack up against historical averages, offering a clearer picture than raw dollar figures. The metric also highlights the role of asset types. A household with $1 million in home equity but $800,000 in mortgage debt may have a net worth of $200,000—placing them in the bottom 30% of wealth distribution. Conversely, a family with $500,000 in liquid assets (stocks, bonds, cash) and no mortgage debt could rank in the top 10%. This distinction matters because liquidity determines resilience during crises. The percent household net worth thus becomes a proxy for financial flexibility, not just accumulation.The Verified Baseline
Public data confirms that percent household net worth is tightly linked to education and geography. According to the Federal Reserve’s 2022 report, households headed by someone with a graduate degree have a median net worth of $1.1 million, versus $361,000 for those with only a high school diploma. Urban households, particularly in high-cost cities like San Francisco or New York, often see their percent household net worth depressed by housing costs, even if nominal incomes are high. Rural households, meanwhile, may appear wealthier on paper due to lower property values—but this can mask liquidity shortages. Tax filings and credit bureau data further validate the trend. The IRS’s Statistics of Income division reveals that the top 1% of taxpayers by net worth hold 35% of all assets, a concentration that has grown since the 2008 financial crisis. Meanwhile, the bottom 50% of households collectively own just 0.5% of national wealth. These figures aren’t speculative; they’re derived from audited returns and regulatory filings. The percent household net worth metric, when benchmarked against these datasets, exposes the structural inequalities that persist even in economies with low unemployment.What the Estimates Suggest
Industry estimates suggest that percent household net worth could decline by 15–20% for middle-class families over the next decade if current trends continue. The Urban Institute projects that student loan debt—now exceeding $1.7 trillion—will suppress net worth growth for younger cohorts, pushing their percent household net worth into the bottom quartile even if incomes rise. For retirees, estimates vary widely: some models predict a 30% drop in median net worth due to inflation, while others argue that Social Security adjustments and part-time work will mitigate losses. Wealth managers often cite percent household net worth as a key risk factor in financial planning. A 2023 study by the National Bureau of Economic Research found that households in the 60th to 80th percentile of net worth are most vulnerable to sequence-of-returns risk—where a poor market performance early in retirement can permanently reduce their percent household net worth. The estimates aren’t just academic; they’re used by institutions to stress-test portfolios and advise clients on debt management.
Case Study: A Closer Look
Consider the Smith family, a dual-income couple in Atlanta with two children. In 2018, their net worth was $450,000—placing them in the 75th percentile nationally. By 2022, after a $200,000 home renovation (financed via a home equity loan) and a 12% stock market correction, their net worth dropped to $380,000. Their percent household net worth slid from the 70th to the 60th percentile, eliminating their eligibility for certain private school tuition programs and forcing them to delay a college savings plan. The renovation wasn’t the sole cause; rising property taxes and a refinance with higher interest rates compounded the impact. Their story reflects a broader trend: percent household net worth isn’t just about absolute numbers but about relative standing. The Smiths’ decline wasn’t catastrophic in dollar terms, but it altered their financial psychology. They began prioritizing debt paydown over discretionary spending, a shift that cascaded into other decisions—like postponing a third child or skipping a dream vacation. > "We weren’t poor, but we weren’t in the top tier anymore. That mental shift changed everything—even our willingness to take risks, like starting a side business." — Jane Smith, Atlanta resident | Factor | Estimated Impact on Percent Household Net Worth | |--------------------------|----------------------------------------------------------------------------------------------------------------------| | Home equity loan | Reduced liquidity by ~15%, pushing percentile down by 10–15 points | | Stock market correction | 12% portfolio loss, but hedged by diversified holdings (net impact: ~8% drop in percentile) | | Rising property taxes | Increased annual expenses by 5%, eroding net worth growth by ~3% annually | | Delayed college savings | Opportunity cost of ~$10,000/year, further suppressing percentile by 5 points over 3 years |What This Means Going Forward
The percent household net worth metric will likely become more prominent as policymakers and financial institutions grapple with stagnant wage growth and asset bubbles. The Biden administration’s proposed wealth tax, for example, targets households with net worth exceeding $100 million—but the debate hinges on how percent household net worth is distributed. Critics argue that such thresholds ignore the middle class’s struggles, while proponents note that the top 0.1% hold 20% of national wealth. The metric forces a conversation about whether wealth accumulation should be incentivized equally or redistributed. For individuals, tracking percent household net worth over time may become as routine as monitoring credit scores. Financial apps like Mint or Personal Capital already provide net worth snapshots, but integrating percentile benchmarks could democratize wealth awareness. The challenge lies in making the data actionable—without triggering paralysis. A household in the 50th percentile might feel secure, but a 10% drop could push them into the bottom quartile, where access to capital dries up.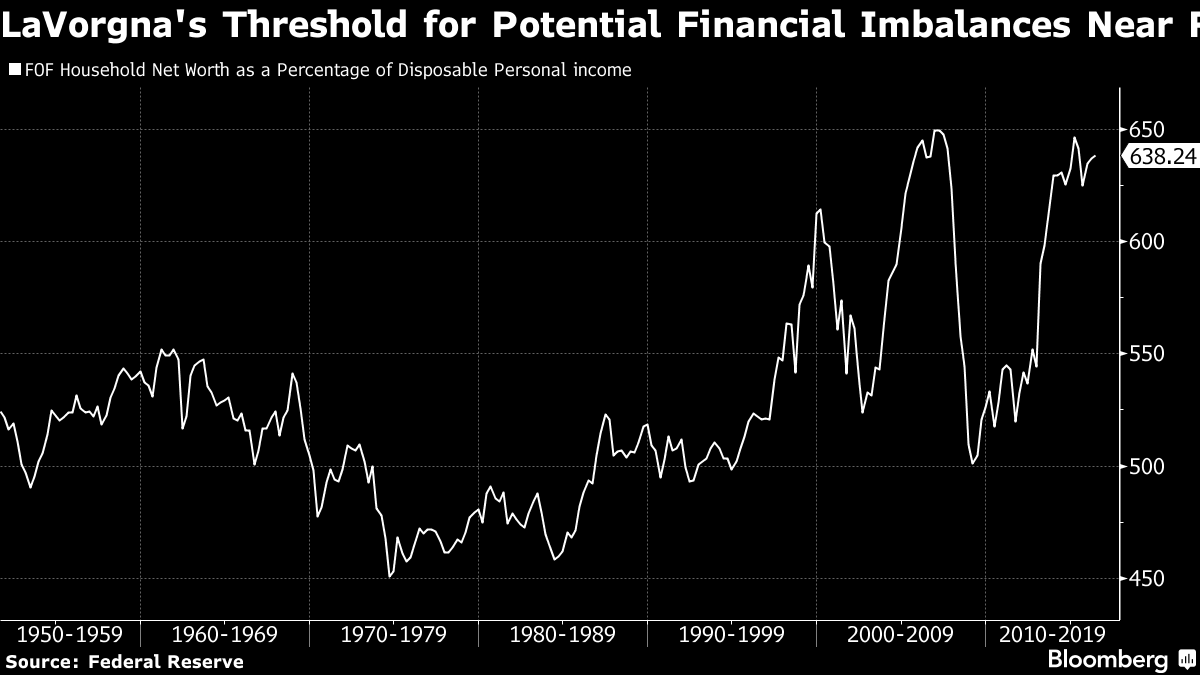
Conclusion
The percent household net worth isn’t a static label—it’s a living indicator of economic health. It reveals how much of the American Dream is within reach, and for whom. The data is clear: without targeted interventions, the wealth gap will widen, and the percent household net worth of future generations will depend less on effort and more on inheritance or luck. The metric also underscores the limits of traditional financial advice. A $500,000 net worth in San Francisco carries different implications than the same figure in rural Mississippi, yet most planning tools treat wealth in isolation. Moving forward, households will need to adopt a percent household net worth-aware mindset. This means diversifying assets beyond traditional retirement accounts, advocating for policies that address wealth inequality, and recognizing that financial security isn’t just about income—it’s about where you stand in the grand scheme. The numbers don’t lie, but the actions they inspire will determine whether the next decade brings convergence or further division.Comprehensive FAQs
Q: How often should I check my percent household net worth?
A: Quarterly is ideal, especially if you have significant debt or volatile assets like stocks. Annual reviews suffice for stable households, but life events (marriage, inheritance, job changes) warrant immediate recalculations. Most financial planners recommend aligning checks with tax season or major portfolio rebalances.
Q: Can my percent household net worth improve even if my income stagnates?
A: Absolutely. Strategies include paying down high-interest debt, refinancing mortgages, or investing in assets that appreciate faster than inflation (e.g., real estate in high-growth areas). The key is leveraging existing assets—like home equity—to generate liquidity without increasing liabilities.
Q: Does percent household net worth matter more than gross income?
A: For long-term planning, yes. Gross income shows earning power, but percent household net worth reflects purchasing power, credit access, and generational wealth potential. A high earner with $1 million in debt may struggle to build equity, while a moderate earner with $500,000 in liquid assets could retire earlier.
Q: How does inflation affect percent household net worth?
A: Inflation erodes the real value of assets like cash or bonds, but it can benefit debtors (since mortgages or loans shrink in real terms). However, if wage growth lags inflation, percent household net worth may decline even if nominal assets rise. Historically, households in the top 20% have weathered inflation better due to diversified portfolios.
Q: Are there tools to estimate my percent household net worth percentile?
A: Yes. The Federal Reserve’s SCF Calculator provides benchmarks, while platforms like Wealthfront or Betterment offer percentile rankings based on user data. For DIY analysis, compare your net worth to IRS or Census Bureau median figures adjusted for your state and household size.
