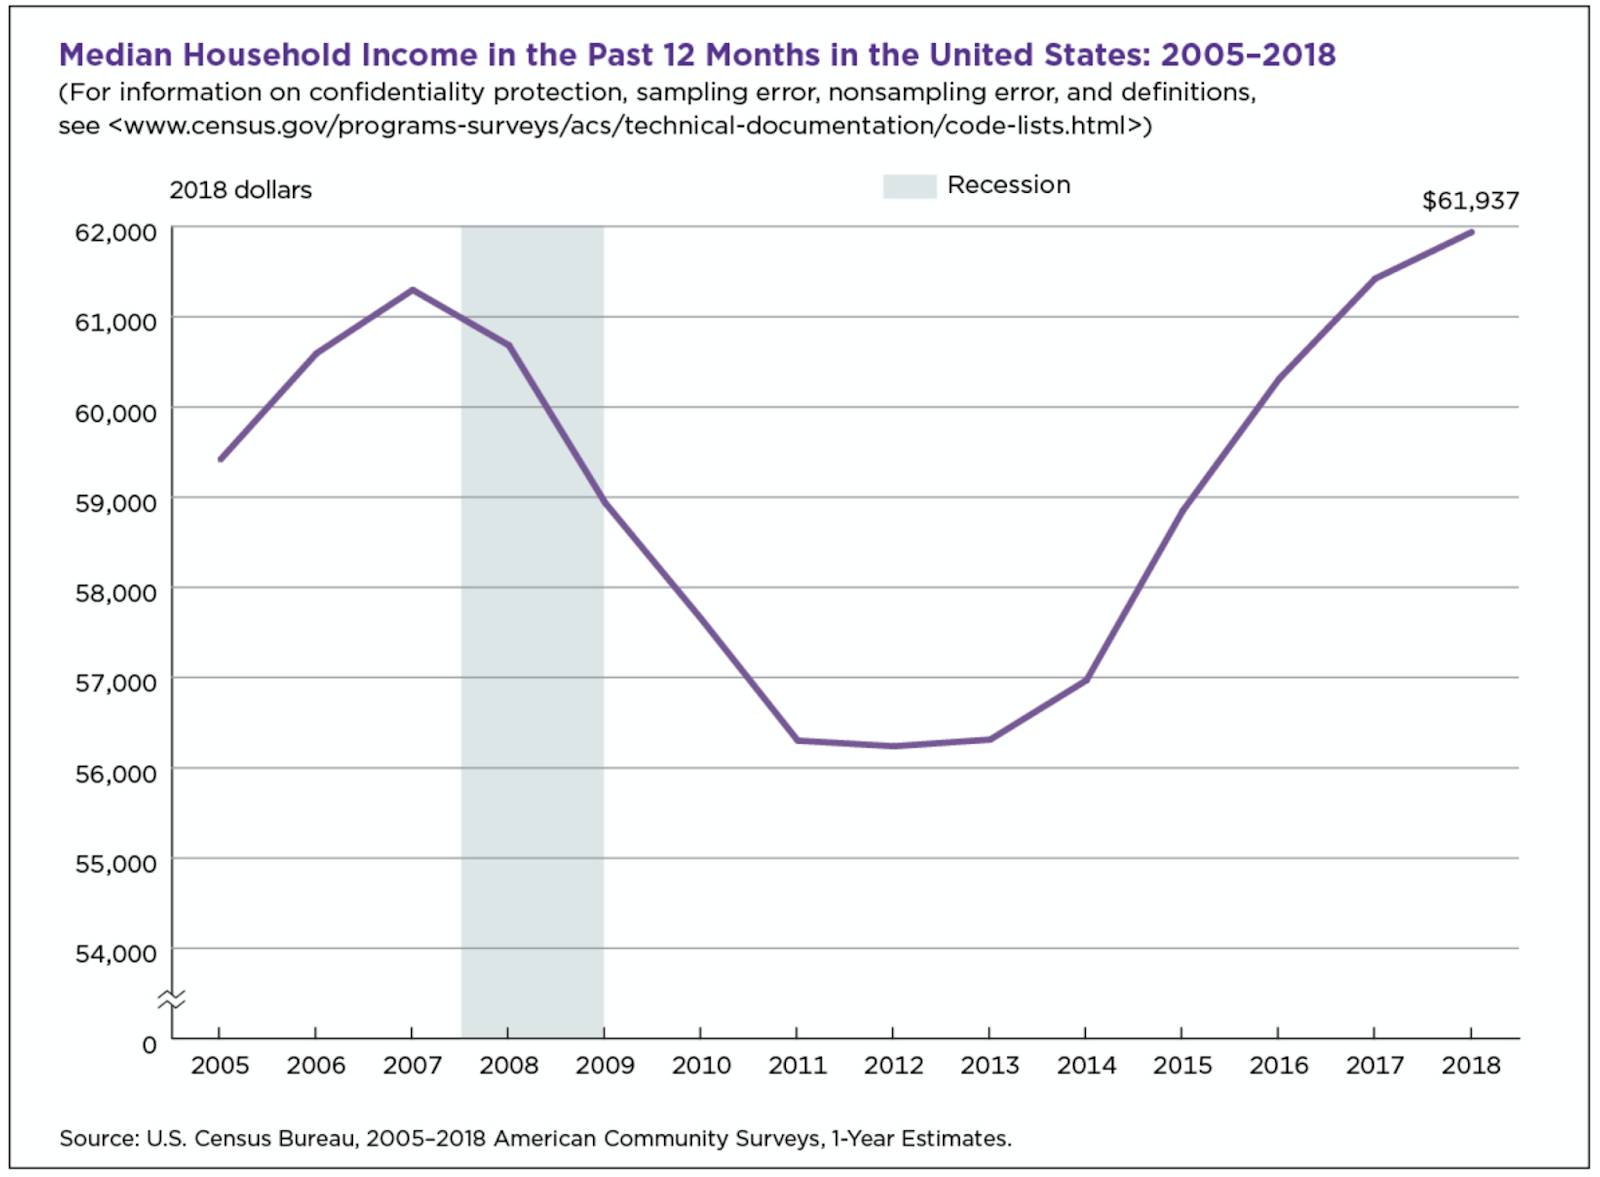
Where It All Began
The roots of northern wealth stretch back to the 19th century, when manufacturing hubs in Pennsylvania and Ohio built the first American middle class. Factories paid wages that allowed workers to save, and by the early 1900s, cities like Detroit and Buffalo had homeownership rates that would later become the envy of the nation. The median net worth in northern states during this era was tied to industrial stability—until the 1970s, when deindustrialization hit. Rust Belt cities hemorrhaged jobs, and wealth disparities emerged even within regions. The federal government’s response—tax credits for homebuyers, student loan subsidies, and the creation of the 401(k) in 1978—benefited northern states disproportionately. States with strong unions and progressive labor laws saw higher wage growth, while southern states, still recovering from agricultural dependence, lagged. By the 1990s, the united states median net worth northern states gap had stabilized, with the Northeast leading by about 30%.The Early Signs
The first clear warning came in 1989, when the Federal Reserve’s wealth data showed that the top 10% of households in Massachusetts held nearly 60% of the state’s total wealth. Meanwhile, in Mississippi, the figure was closer to 40%. The disparity wasn’t just about income—it was about generational wealth. Northern states had older populations with more time to accumulate assets, while southern states saw younger, less affluent demographics. The 2008 financial crisis exposed another layer: homeownership rates. Northern states had higher rates of equity-rich homeowners, thanks to decades of stable property values. When the housing market collapsed, northern households weathered the storm better, preserving their median net worth in northern regions—a resilience that would define the recovery.The Turning Point
The late 1990s marked the shift. The dot-com boom created a new class of millionaires in Boston and Seattle, but the real change came from policy. States like New Hampshire eliminated inheritance taxes, while New York expanded its earned income tax credit. These moves didn’t just attract wealthy individuals—they incentivized asset growth. By 2005, the united states median net worth northern states gap had widened to nearly 50% over the national average. The turning point wasn’t just economic; it was cultural. Northern states embraced financial literacy programs, while southern states grappled with predatory lending practices. The result? A self-reinforcing cycle where higher education levels led to better-paying jobs, which in turn led to higher savings rates."Wealth isn’t just about what you earn—it’s about what you keep. Northern states have mastered that equation." — Robert Shapiro, economist and former Clinton administration official

The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 1980s | Deindustrialization hits the Rust Belt, but northern states invest in higher education, preserving middle-class wealth. |
| 1990s | Tech boom in Boston and Seattle; venture capital flows north, boosting high-net-worth households. |
| 2000s | State-level tax reforms (e.g., New Hampshire’s inheritance tax repeal) accelerate wealth accumulation. |
| 2010s | Stock market recovery post-2008 benefits northern retirees; homeownership rates stabilize. |
| 2020s | Remote work reduces geographic barriers, but northern states retain wealth advantages through policy and education. |
Lessons From the Journey
- Policy matters. States that incentivized savings—through 529 plans, pension reforms, or tax breaks—saw higher median wealth.
- Education pays off. Northern states with top universities (e.g., Michigan, Wisconsin) had higher graduate earnings and asset accumulation.
- Homeownership is a wealth multiplier. States with strong housing markets (e.g., Minnesota, Vermont) saw slower wealth erosion during crises.
- Demographics shape outcomes. Older populations in northern states had more time to build equity, while younger southern populations faced student debt burdens.
Where Things Stand Today
As of 2023, the median net worth in northern states remains robust, with Maryland leading at over $150,000 per household—nearly double the U.S. median. The gap isn’t closing, thanks to remote work trends that allow high earners to stay in expensive northern hubs. Yet challenges remain: rising housing costs in cities like Boston and New York threaten to price out the next generation. The data tells two stories. First, northern states have optimized wealth-building through policy and education. Second, the system isn’t static—remote work and migration patterns could reshape the map in unexpected ways. One thing is certain: the united states median net worth northern states divide isn’t accidental. It’s the result of deliberate choices.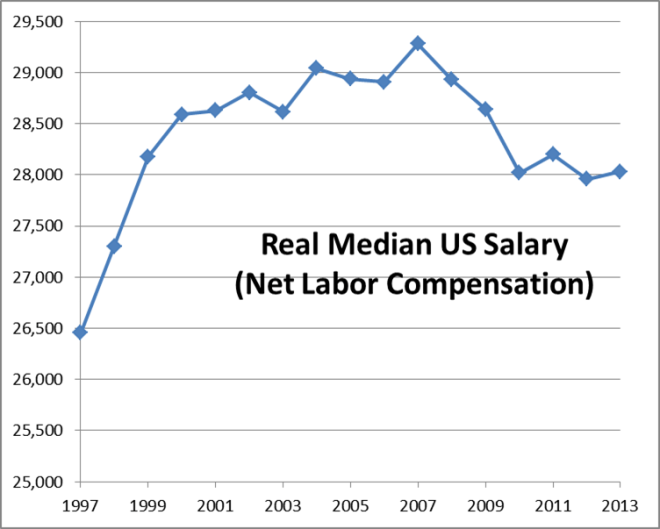
Conclusion
The united states median net worth northern states dynamic isn’t just about geography—it’s about history, policy, and culture. Northern states didn’t achieve their wealth position by chance; they invested in education, taxed assets strategically, and preserved industrial legacies when others abandoned them. The lesson for the rest of the country? Wealth accumulation is a function of systemic support, not just individual effort. The question now is whether the South and West can narrow the gap—or if the North will continue to pull ahead, even as the economy evolves. One thing is clear: the data isn’t just a snapshot. It’s a roadmap.Comprehensive FAQs
Q: Why do northern states have higher median net worth than southern states?
The primary factors are historical industrial strength, higher education levels, stronger public-sector employment, and decades of wealth-preserving policies like pension reforms and tax incentives. Northern states also benefited from earlier access to financial tools like 401(k)s and homeownership subsidies.
Q: Which northern state has the highest median net worth?
As of recent data, Maryland consistently ranks at the top among northern states, with a median net worth estimated at over $150,000 per household—partly due to strong federal employment in Washington, D.C., and high homeownership rates.
Q: Do rural northern states perform as well as urban ones?
No. While urban centers like Boston and Minneapolis lead, rural areas in upstate New York and the Upper Midwest often lag due to lower wages and limited economic diversification. However, states like Minnesota and Wisconsin have mitigated this through strong agricultural and manufacturing policies.
Q: How does remote work affect the northern states’ wealth advantage?
Remote work has reduced some geographic barriers—high earners can now live in lower-cost southern states—but it hasn’t erased the advantage. Northern states still offer better education, healthcare, and tax structures, which remain key wealth drivers.
Q: Are there southern states closing the gap?
Some southern states, like Virginia and Texas, have seen rapid wealth growth due to tech migration and business-friendly policies. However, they still trail northern states in median net worth by about 20-30%, largely due to lower education levels and weaker public-sector employment.
Q: What role do inheritance taxes play in northern wealth?
States like New Hampshire and Delaware have eliminated inheritance taxes, allowing wealth to compound across generations. In contrast, states with high estate taxes (e.g., Oregon) see more wealth transferred to trusts or other structures, which can still preserve family assets.
Q: How does student debt impact northern vs. southern wealth?
Northern states have higher student debt burdens due to elite universities, but their graduates also earn significantly more, offsetting the debt. Southern states, with lower average incomes, struggle more with repayment, which suppresses wealth accumulation.
