
Common Myths About Net Worth With Housing
The idea that "net worth with housing" provides a clearer picture of financial standing is rooted in two persistent misconceptions: first, that property values are stable; second, that debt tied to a home doesn’t matter as much as other liabilities. Neither holds up under scrutiny. The first myth assumes housing markets move in lockstep with broader economic growth, ignoring regional bubbles, zoning laws, or natural disasters that can erase equity overnight. The second myth treats mortgages as benign because they’re secured by "an asset," ignoring the fact that underwater homes force sales at a loss or trap owners in negative equity for decades.
Another false assumption is that "net worth with housing" makes sense for comparative purposes. A family with a $500,000 home and $400,000 mortgage isn’t meaningfully wealthier than one with $300,000 in liquid assets and no debt—yet the first household’s net worth appears higher if housing is double-counted. This distortion is particularly dangerous in wealth tracking, where benchmarks like the median net worth often inflate perceptions of middle-class prosperity by including home equity that may not be accessible without selling.
Myth 1: "Housing is a safe investment, so it should be counted separately"
The argument that housing deserves special treatment in wealth calculations rests on the idea that real estate is inherently less risky than stocks or crypto. In stable markets, this might hold true, but historical data shows that home values can plummet just as sharply. During the 2008 financial crisis, U.S. home prices dropped by nearly 32% in some regions, wiping out decades of equity for homeowners. Even in recovery periods, the time it takes to recoup losses—often measured in years—means housing isn’t the liquid or flexible asset it’s often portrayed as.
What’s more, the "net worth with housing" framework ignores opportunity cost. A homeowner locked into a mortgage at 7% interest isn’t just forgoing potential returns from other investments; they’re also exposed to maintenance costs, property taxes, and the risk of being house-rich but cash-poor in retirement. Wealth isn’t just about balance sheet numbers—it’s about flexibility. Someone with $1 million in stocks and no mortgage can access that capital immediately; someone with a $1 million home and a $500,000 mortgage may have to sell to unlock funds, triggering capital gains taxes and transaction costs.
Myth 2: "Including housing makes wealth comparisons fairer"
The push to adjust net worth figures by adding back housing stems from a noble goal: accounting for the fact that many people’s largest asset isn’t easily tradable. But this approach fails to address the core issue—liquidity. A $2 million home doesn’t translate to $2 million in spending power unless the owner sells, which isn’t practical for most. Meanwhile, someone with $2 million in a diversified portfolio can withdraw funds, reinvest, or pass assets to heirs without triggering the same constraints.
The "net worth with housing" metric also obscures regional disparities. In San Francisco, where median home prices exceed $1.5 million, including housing in wealth calculations artificially inflates net worth figures for residents who may still struggle with student debt or childcare costs. Conversely, in rural areas where homes are affordable, excluding housing might understate true financial security. The solution isn’t double-counting an asset; it’s recognizing that wealth metrics must account for both nominal value and real-world usability.
Myth 3: "Debt against housing doesn’t count the same as other debt"
This is perhaps the most insidious myth of all. A $300,000 mortgage is still debt, regardless of whether it’s secured by a home. The psychological comfort of owning property doesn’t change the fact that monthly payments reduce disposable income just like credit card debt. Yet, the "net worth with housing" framework often treats mortgages as a neutral or even positive factor, assuming that equity will always appreciate.
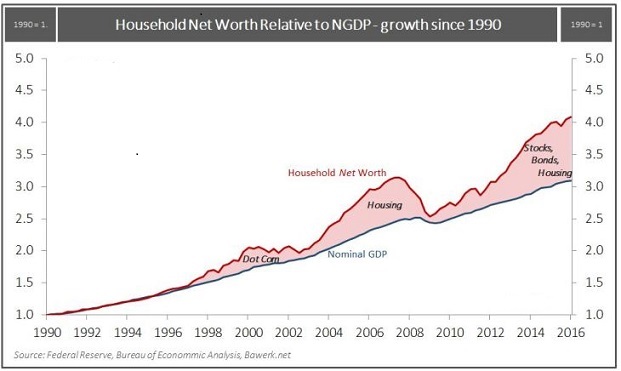
The reality is that leverage amplifies both gains and losses. During the 2000s housing bubble, homeowners who borrowed heavily against rising equity found themselves in trouble when prices stalled. Today, with mortgage rates near 20-year highs, many homeowners are "house poor"—spending a larger share of their income on housing than in previous generations. The "net worth with housing" calculation doesn’t reflect this strain because it treats the home’s value as a static number, not a volatile asset with embedded risk.
What Holds Up to Scrutiny
The only scenario where "net worth with housing" makes sense is as a supplemental metric—not a primary one. Financial planners sometimes use adjusted net worth figures to account for illiquid assets, but they pair this with liquidity ratios (e.g., cash reserves, emergency funds) to paint a fuller picture. The key distinction is that standard net worth already includes home equity; adding it back doesn’t change the underlying value but does change how that value is interpreted.
What actually matters is accessible wealth. A family with a $1 million home and $800,000 in debt has $200,000 in equity—but if they can’t sell without incurring losses or taxes, that equity is effectively locked. Meanwhile, someone with $200,000 in a high-yield savings account has immediate spending power. The "net worth with housing" figure ignores this critical difference.
> "Wealth isn’t just a number on a spreadsheet; it’s the ability to deploy assets when you need them."
> — *Carolyn Wong, Certified Financial Planner and Author of The Wealth Gap in America
| Common Belief | What the Evidence Says |
|----------------------------------|-------------------------------------------------------------------------------------------|
| "Housing is the safest asset." | Home values can drop 30%+ in crises; maintenance and taxes erode returns over time. |
| "Double-counting housing shows true wealth." | It inflates perceptions without addressing liquidity or debt serviceability. |
| "Mortgage debt is different." | It’s still debt—high rates and long terms strain budgets just like unsecured loans. |
Why the Confusion Persists
The "net worth with housing" concept endures because it aligns with cultural narratives about the American Dream—homeownership as a marker of success. Media outlets, financial advisors, and even government reports sometimes use adjusted figures to make wealth appear more attainable, especially in high-cost cities where home prices dominate net worth calculations. Politicians highlight median home values to suggest prosperity, while critics of wealth inequality point to home equity as proof that middle-class Americans are "doing okay."
But the confusion also stems from a lack of standardized definitions. Some sources use "net worth with housing" to mean gross home value (ignoring mortgages), while others adjust for debt but still treat housing as a separate category. This inconsistency makes it difficult to compare apples to apples. The real issue isn’t the term itself but the failure to contextualize it within broader financial health—debt levels, cash flow, and alternative investment opportunities.

Conclusion
"Net worth with housing" is a red herring—a figure that sounds intuitive but obscures more than it clarifies. The problem isn’t that housing should or shouldn’t be part of wealth calculations; it’s that treating it as a standalone metric ignores the fundamental principles of liquidity and risk. A home is an asset, but its value is only as useful as the owner’s ability to leverage it without penalty.
For individuals tracking their finances, the focus should be on net worth as traditionally defined—assets minus liabilities—paired with liquidity assessments. For policymakers and economists, the discussion should center on accessible wealth, not just nominal figures. The next time someone invokes "net worth with housing" in a conversation about financial health, ask: What good is that wealth if you can’t use it?
Comprehensive FAQs
#### Q: Should I calculate my net worth with housing included?
No. Standard net worth already accounts for your home’s value (minus any mortgage). Including it again doesn’t change your actual wealth—it only changes how you perceive it. If you’re curious about your home’s role in your finances, track equity separately (current value minus mortgage) and compare it to your liquid assets.
####Q: Does including housing make my net worth look better for loans or investments?
Not reliably. Lenders and investors care about liquid net worth—cash, stocks, and other easily convertible assets. While some high-net-worth programs consider home equity, most financial institutions focus on what you can access without selling your primary residence. Inflating your net worth artificially could backfire if you later need to prove liquidity.
####Q: Why do some wealth reports use "net worth with housing" for comparisons?
It’s often a way to make wealth appear more attainable, especially in regions with high home prices. For example, the median U.S. net worth jumps from ~$120,000 (excluding housing) to ~$400,000 (including primary residences) in Federal Reserve data. However, this obscures the fact that much of that "wealth" is tied up in illiquid assets and debt.
####Q: Can I adjust my net worth calculation to include rental properties differently?
Yes, but treat rental properties as business assets, not personal ones. Their value should be calculated based on market rent, expenses, and cash flow—not just purchase price. If you’re including them in net worth, subtract all liabilities (mortgages, repairs, vacancies) and consider their liquidity (can you sell quickly without penalty?).
####Q: Does "net worth with housing" matter for estate planning?
Indirectly. While your executor will account for your home’s value in your estate, they’ll also consider liquidity needs—such as paying off the mortgage or covering taxes. If your heirs rely on selling the home to access funds, its market value becomes critical. However, the term "net worth with housing" isn’t used in legal or tax contexts; instead, appraisals and probate courts focus on current value, not hypothetical adjustments.
####Q: How does "net worth with housing" affect perceptions of wealth inequality?
It can widen the perceived gap. For example, a homeowner in a high-cost city may appear wealthier on paper due to home equity, while a renter with the same liquid assets might seem poorer. This distorts discussions about economic mobility, as homeownership rates (not just values) play a larger role in actual financial security.
####Q: Are there cases where "net worth with housing" is useful?
Rarely, but some financial planners use adjusted net worth for clients nearing retirement to assess how home equity could supplement income. For instance, a reverse mortgage might convert home equity into cash flow. However, this is a specialized calculation—not a general rule—and should always be paired with liquidity stress tests.
####Q: What’s a better way to track home-related wealth?
Break it down:
- Home Equity: Current market value minus mortgage balance.
- Liquid Alternatives: Cash reserves, investments, or other assets you can access without selling.
- Debt Burden: Monthly housing costs (mortgage, taxes, insurance) as a percentage of income.
