The Complete Overview of Net Worth by Age and Percentile
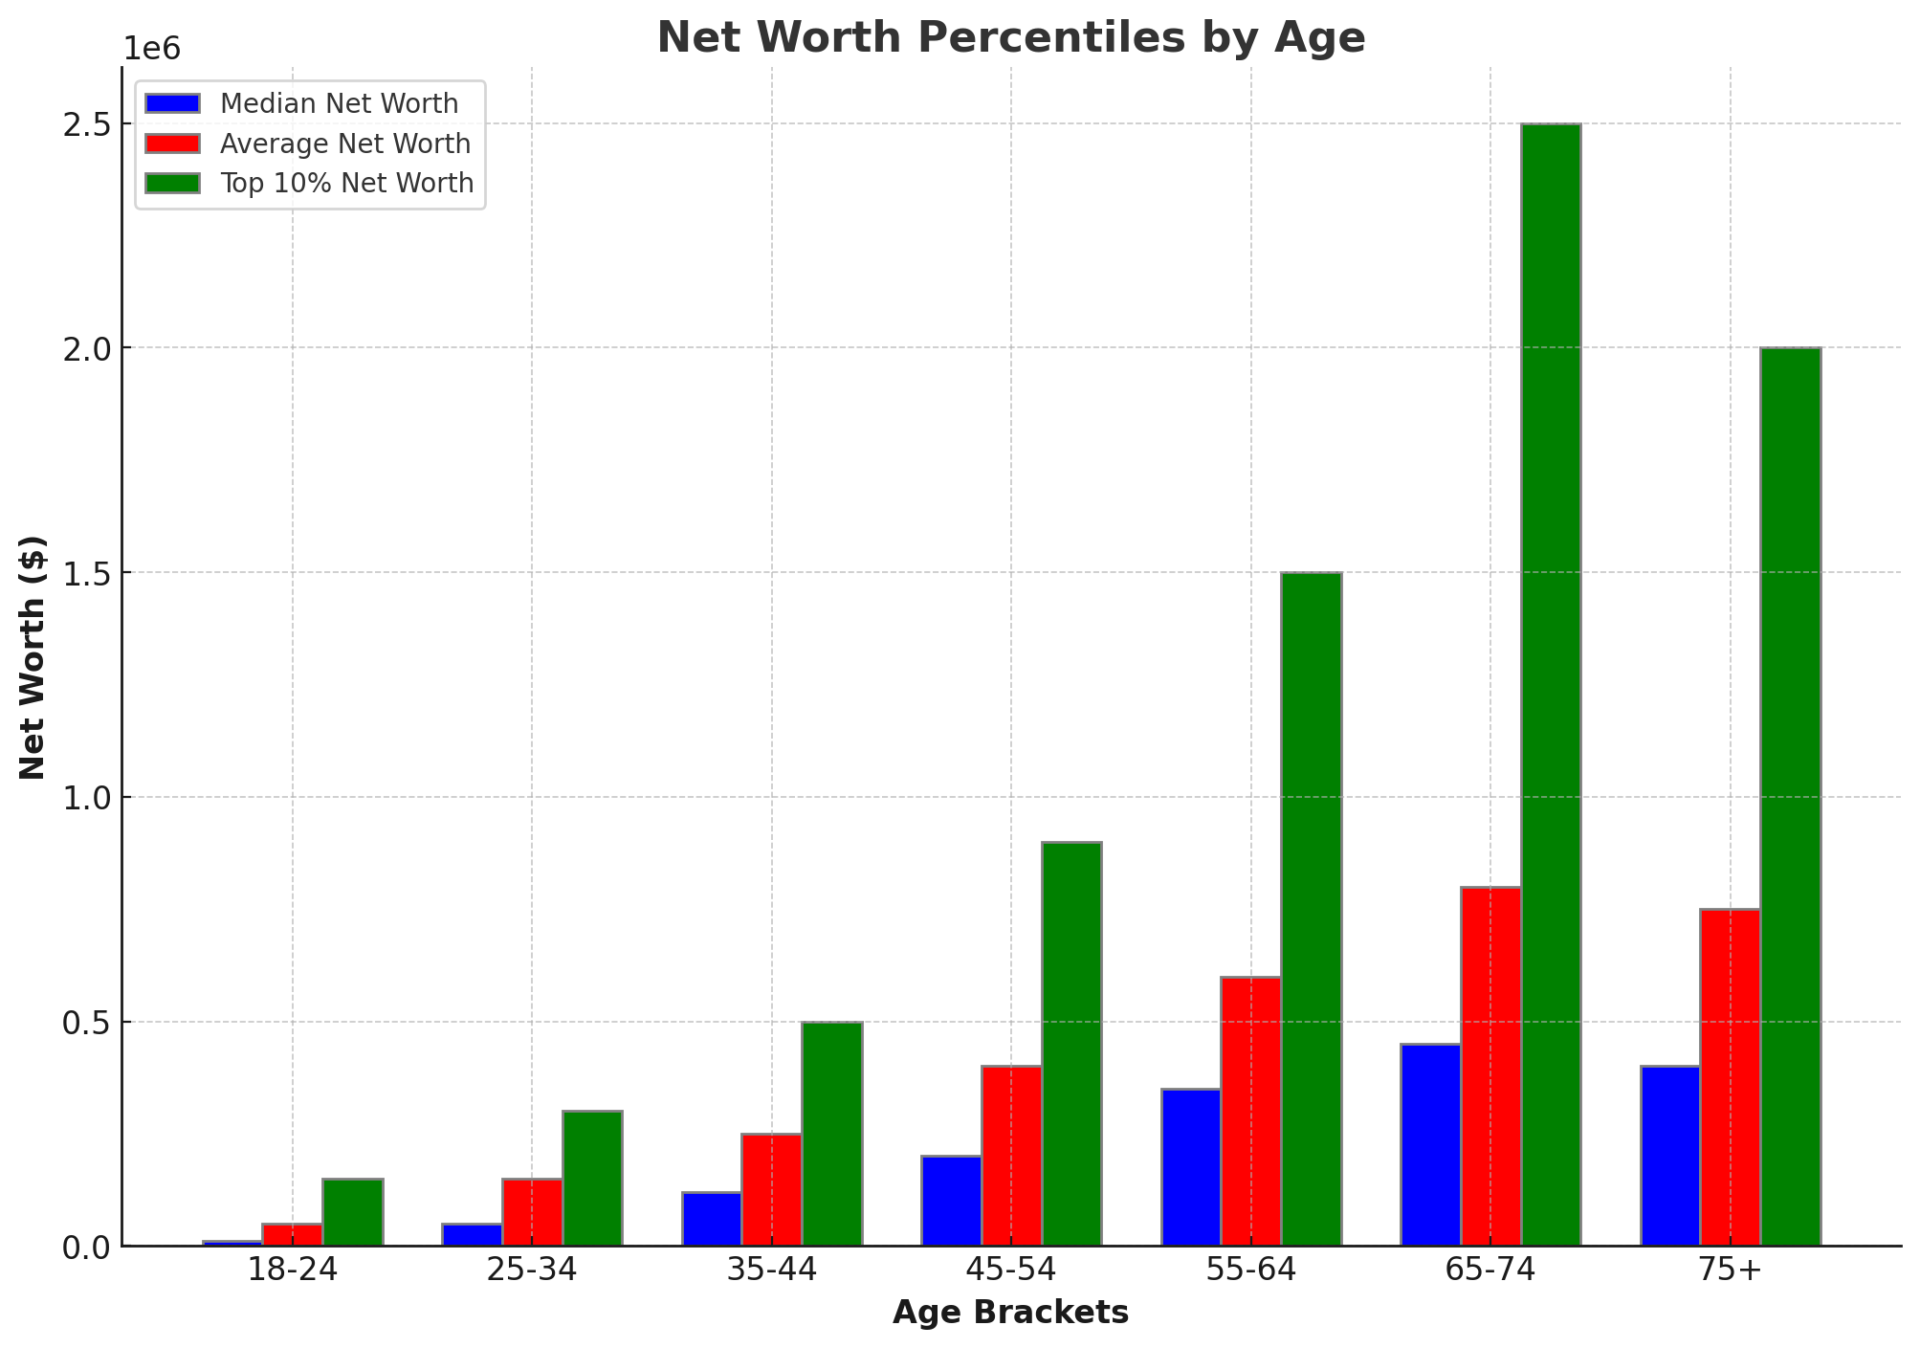
Net worth by age and percentile isn’t just a financial metric; it’s a real-time audit of economic mobility. The Federal Reserve’s data shows that by age 35, the top 10% hold 60% of all household wealth, while the bottom 50% collectively own just 2.6%. These aren’t abstract statistics—they’re the result of tax policies favoring capital gains, the persistence of inherited wealth, and the cost of living outpacing wage growth. The median net worth of a 60-year-old has stagnated for decades, while the 90th percentile’s has doubled since the 1980s. The most striking pattern? Wealth begets wealth. A 40-year-old in the 85th percentile likely has parents who were in the top quartile at their age, giving them early access to capital, co-signed loans, or professional networks. Meanwhile, a peer in the 30th percentile might still be paying off student debt while renting. The data isn’t just about numbers—it’s about who gets the chance to play the game.Historical Background and Evolution
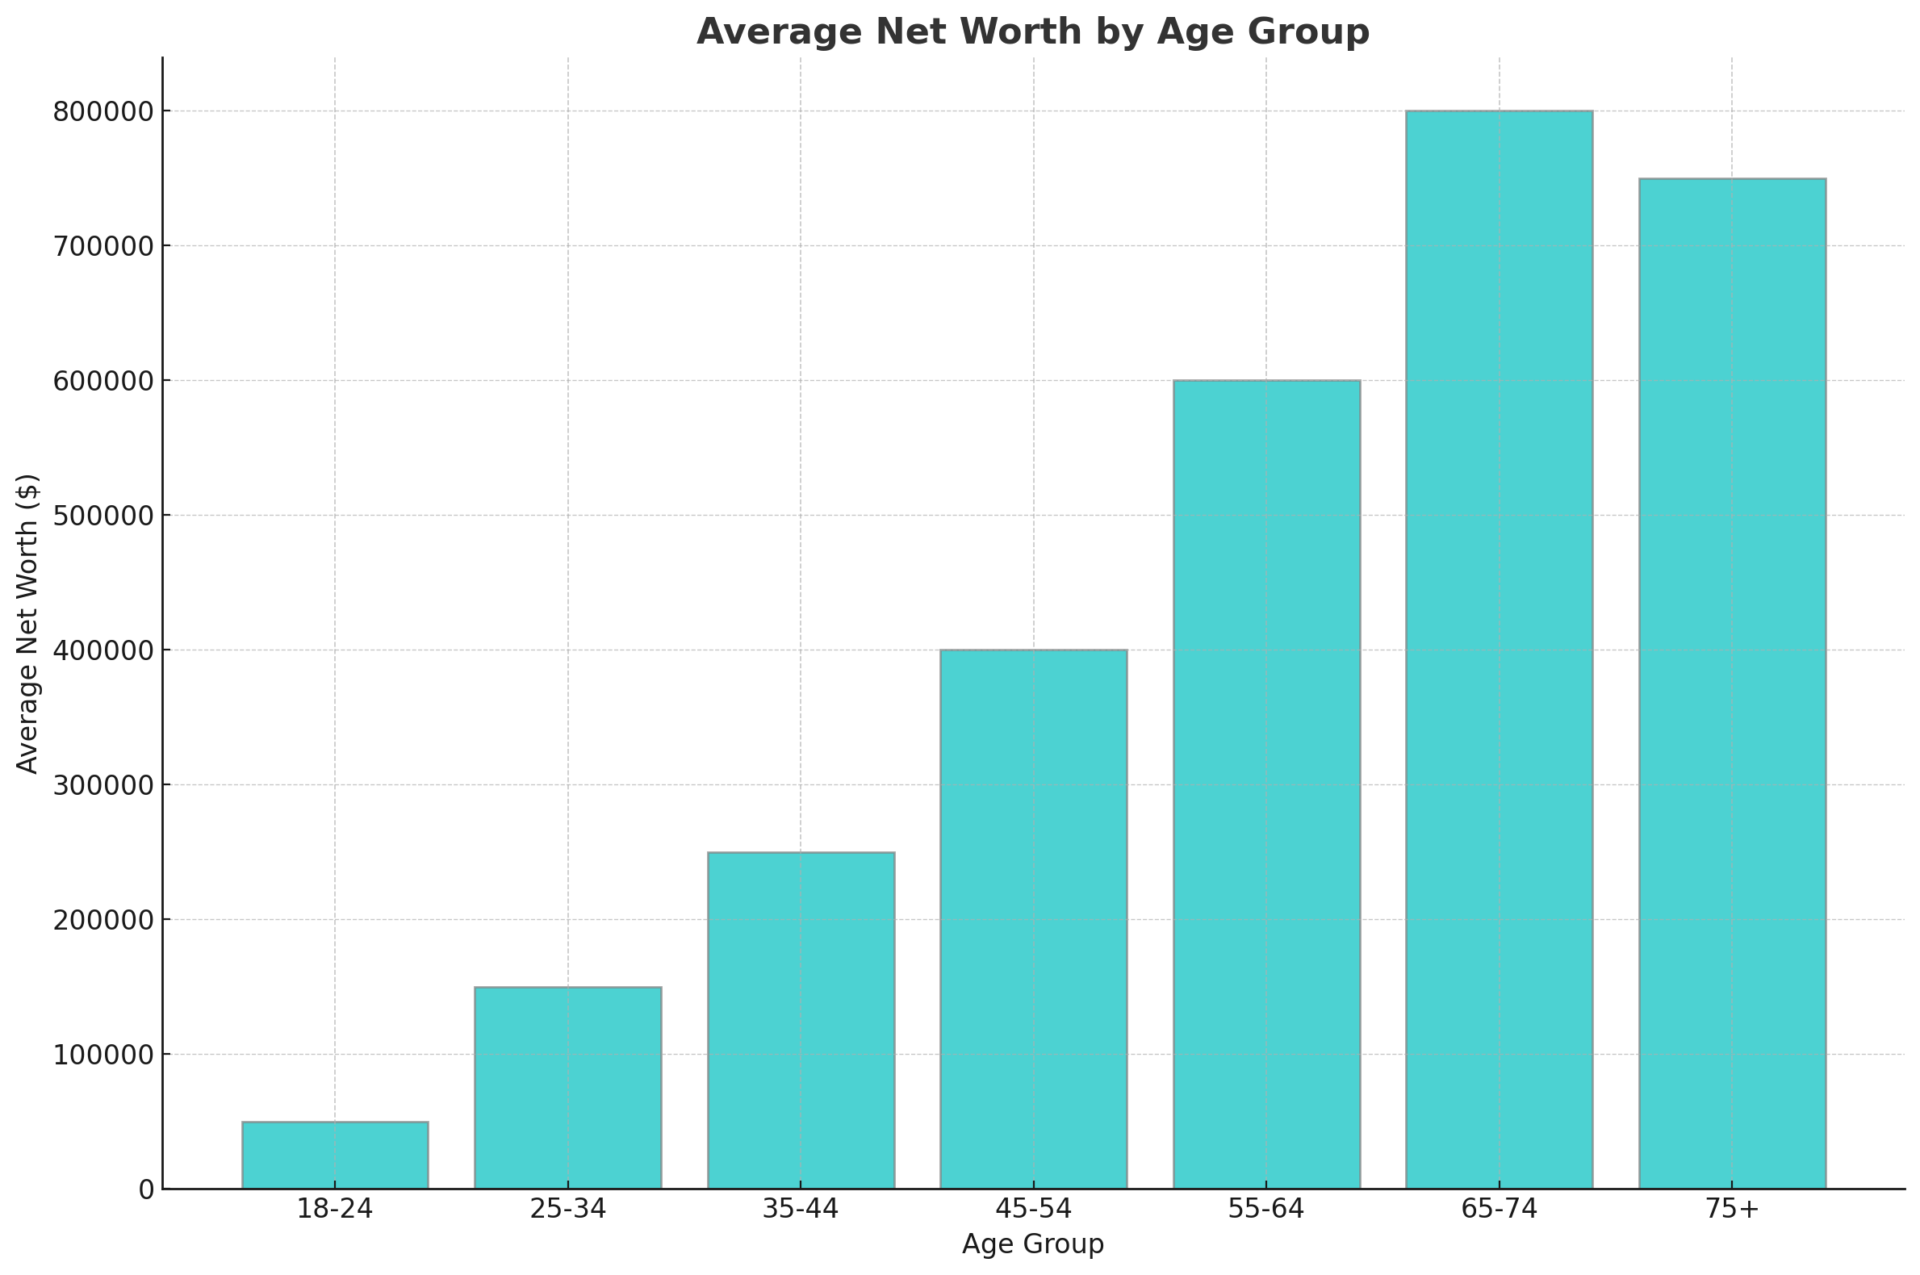
The modern tracking of net worth by age and percentile began in earnest with the 1983 Survey of Consumer Finances, but the trends it exposed were centuries in the making. Before the 20th century, wealth accumulation was tied to land ownership—a system that favored those already privileged. The Gilded Age saw the rise of industrial fortunes, but the New Deal’s policies briefly narrowed gaps by introducing Social Security and labor protections. By the 1980s, however, deregulation and tax cuts shifted wealth upward, accelerating the divergence we see today. The 2008 financial crisis temporarily compressed net worth by age and percentile as housing values collapsed, but the recovery was highly unequal. The top 1% saw their wealth grow by 22%, while the bottom 90% gained just 4%. Post-crisis policies—like the 2017 Tax Cuts and Jobs Act—further tilted the playing field. Today, the median net worth of a 65-year-old hasn’t kept pace with inflation, while the 95th percentile’s has surged due to stock market gains and real estate appreciation. The historical takeaway? Wealth inequality isn’t a bug—it’s a feature of capitalism’s current design.Core Mechanisms: How It Works
Net worth by age and percentile is calculated by ranking households by total assets (real estate, investments, business equity) minus liabilities (debt, mortgages). The Federal Reserve’s methodology groups data into five-year age brackets (e.g., 35–39) and percentiles (10th, 25th, 50th, 75th, 90th). The key variable? Time horizon. A 30-year-old in the 75th percentile might have $150,000 in assets, but their 90th-percentile peer could have $500,000—thanks to early investments, inheritance, or high-earning careers. The mechanics aren’t just about saving rates. It’s about asset classes. The top decile’s wealth is 70% in financial assets (stocks, bonds, private equity), while the median household’s is 60% in home equity. This explains why recessions hit the middle class harder: their wealth is concentrated in illiquid assets. Meanwhile, the ultra-wealthy can diversify into hedge funds or collectibles, insulating them from downturns. The system rewards those who inherit both capital and the knowledge of how to deploy it.Key Benefits and Crucial Impact
Understanding net worth by age and percentile isn’t just about benchmarking—it’s about exposing structural advantages. For policymakers, these figures highlight where interventions could level the playing field: student debt relief, inheritance taxes, or expanded retirement accounts. For individuals, it’s a mirror. A 45-year-old in the 60th percentile might realize their trajectory is off-track compared to peers, prompting a shift in savings or career strategy. The data also forces a reckoning with myths of meritocracy. A 50-year-old in the 99th percentile didn’t just “work harder”—they likely benefited from generational wealth, tax loopholes, or industry timing. The impact? Younger generations face a wealth gap so wide that homeownership is becoming a privilege, not a milestone. As economist Thomas Piketty noted, “The past decade has seen a return to nineteenth-century levels of inequality”—and the numbers prove it. > “Wealth isn’t just money; it’s the ability to convert assets into opportunity. The percentile data shows that for most Americans, the game is rigged before the first move.” > — Edward N. Wolff, Professor of Economics at NYUMajor Advantages
- Early detection of financial gaps. Net worth by age and percentile reveals where individuals fall relative to peers, allowing corrective action (e.g., aggressive savings, side hustles, or debt reduction).
- Policy leverage. Governments use these benchmarks to design targeted programs—like first-time homebuyer grants or student debt forgiveness—that address systemic inequities.
- Investment insights. High percentiles often correlate with exposure to high-growth assets (private equity, real estate), signaling where capital is flowing.
- Intergenerational planning. Parents in the 85th percentile can see how their children’s trajectories compare, prompting discussions about inheritance, trusts, or education funding.
Comparative Analysis
| Age Group | Median Net Worth (50th Percentile) vs. 90th Percentile |
|---|---|
| 35–39 | $91,300 (median) vs. $500,000 (90th) |
| 45–49 | $255,000 (median) vs. $1.2 million (90th) |
| 55–59 | $421,000 (median) vs. $2.1 million (90th) |
| 65+ | $365,000 (median) vs. $2.2 million (90th) |
Future Trends and Innovations
The next decade will likely see two competing forces shaping net worth by age and percentile. On one hand, automation and AI could boost productivity, lifting wages for skilled workers—but only if those gains trickle down. On the other, student debt and housing costs will continue to suppress the median, pushing more young adults into the gig economy, where wealth accumulation is even harder. The ultra-wealthy, meanwhile, will increasingly deploy capital into alternative assets (crypto, art, private credit), further insulating their percentiles from market volatility. One wild card? Policy shifts. If wealth taxes or inheritance reforms gain traction, the top percentiles could see their trajectories flatten. But given political resistance to redistributive measures, the more likely scenario is stagnation for the middle class and hyper-acceleration for the top 1%. The result? By 2040, the 99th percentile’s net worth could be 15x that of the median—unless structural changes intervene.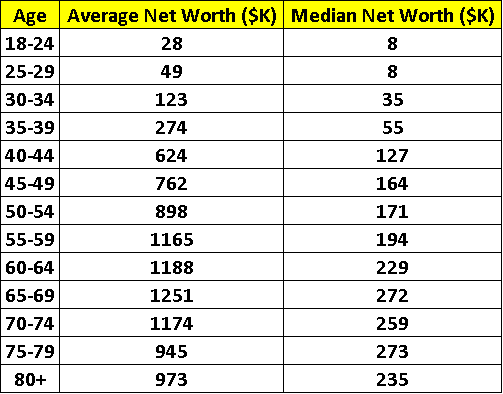
Conclusion
Net worth by age and percentile isn’t just a financial snapshot—it’s a report card on economic fairness. The data doesn’t just show who has what; it reveals who gets the chance to accumulate it. For individuals, it’s a wake-up call: if you’re in the 60th percentile at 40, you’re not just “behind”—you’re in a system designed to keep you there. For policymakers, the figures are a challenge: can democracy survive when wealth concentration reaches these levels? The answer lies in redefining the rules. Whether through expanded Social Security, student debt relief, or corporate tax reforms, the goal must be to compress the gap before it becomes permanent. The alternative? A future where net worth by age and percentile isn’t just a statistic—it’s a caste system.Comprehensive FAQs
Q: How accurate are the Federal Reserve’s net worth by age and percentile estimates?
The Survey of Consumer Finances (SCF) samples 5,000–6,000 households, providing robust benchmarks. However, it excludes ultra-high-net-worth individuals (those with $20M+), so the top 0.1% is underrepresented. For precise personal analysis, consider supplementing with credit bureau data or wealth management tools.
Q: Can I improve my percentile ranking with aggressive savings?
Partially. The top percentiles benefit from compounding, asset appreciation, and inheritance. A 30-year-old saving $1,000/month could reach the 75th percentile by 65, but breaking into the 90th requires higher income, tax-advantaged investments, or real estate leverage. The gap narrows only with structural changes—like lower student debt or higher wages.
Q: Why does homeownership matter so much in net worth by age and percentile?
Home equity accounts for ~30% of total U.S. wealth. For the median household, it’s often their only major asset. The 90th percentile, meanwhile, diversifies into stocks, businesses, or rental properties. Without homeownership, climbing percentiles becomes exponentially harder—especially in high-cost cities where rent erodes savings.
Q: How does student debt affect net worth by age and percentile?
Debt delays asset accumulation. A 35-year-old with $50K in student loans may be 10 percentile points lower than a peer with no debt, even if incomes are similar. The impact persists: by 50, the debt-burdened individual could still be in the 60th percentile while their debt-free counterpart reaches the 80th. This is why student debt forgiveness is a wealth redistribution tool.
Q: Are there regional differences in net worth by age and percentile?
Yes. Coastal states (California, Massachusetts) have higher top-percentile wealth due to tech and finance hubs, but also lower median net worth due to housing costs. Rust Belt states show compressed percentiles—fewer ultra-wealthy individuals but also fewer struggling households. Rural areas often have lower overall net worth, with fewer liquid assets beyond land.
Q: Can inheritance explain the top 10%’s dominance in net worth by age and percentile?
Absolutely. Studies show 60–70% of wealth transfers occur through inheritance, not lifetime earnings. A 40-year-old in the 95th percentile is three times more likely to have received a windfall than a median peer. This is why estate taxes and inheritance reforms are critical to narrowing gaps.
Q: How does marriage affect net worth by age and percentile?
Marriage can boost percentiles by combining incomes and assets, but the effect varies by gender. Couples where both partners earn above-median incomes often reach the 80th+ percentile faster. However, divorce or unequal earnings can drag households downward—especially for women, who statistically hold 30% less wealth post-divorce.
Q: What’s the biggest misconception about net worth by age and percentile?
The myth that effort alone determines percentile rank. The data shows that 70% of wealth accumulation is tied to birth cohort, geography, and inheritance—not just savings rates. A 50-year-old in the 90th percentile didn’t just “work harder”; they likely had parents in the top quartile, attended elite schools, or benefited from timing (e.g., buying a home in 2012).
