The Short Answers
- Net income on net worth statement isn’t standard but should be included as a separate line item to reflect earning power.
- Omitting it distorts liquidity assessments, especially for variable-income earners like freelancers or executives with bonuses.
- Taxable income ≠ net income; the latter accounts for deductions, taxes, and business expenses critical to accurate wealth tracking.
- High net worth individuals often use net income on net worth statement to justify leverage (e.g., mortgages, investments) that wouldn’t be viable without steady cash flow.
- Software like Mint or YNAB can track income separately, but manual adjustments are needed to integrate it into net worth calculations.
- For tax or legal purposes, net worth statements rarely include income—this is a personal finance optimization, not a compliance requirement.

Deep Dive: The Full Picture
Wealth isn’t static. It’s a function of three variables: what you own, what you owe, and what you consistently generate. The first two are easy to quantify. The third—net income on net worth statement—demands context. A software engineer earning $200,000 annually with $500,000 in assets looks vastly different from a retiree on $50,000 with the same asset base. The first has the capacity to grow; the second may face liquidity constraints. Yet both might show identical net worth figures if income is excluded. The omission persists because net worth statements evolved from estate-planning tools, where income was irrelevant to heir apparent calculations. But for living individuals—especially those navigating debt, investments, or career transitions—the income line is the difference between a solvency warning and a growth forecast. Ignore it, and you’re left with a document that tells you where you stand, not how you’ll move forward.The Context You Need
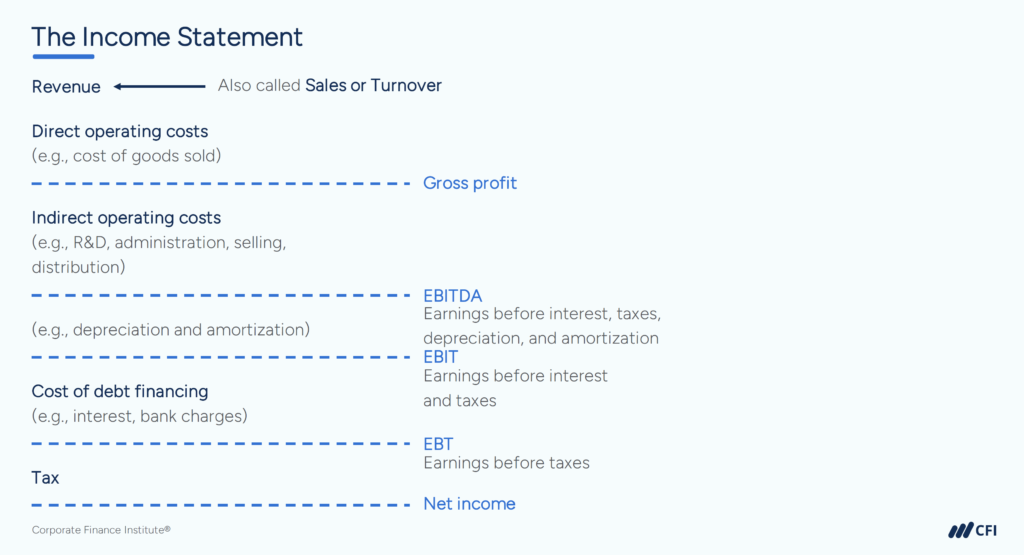
Financial planners distinguish between net worth (assets minus liabilities) and cash flow (income minus expenses). The first is a balance sheet; the second is an income statement. Most net worth reports treat them as separate exercises, but they’re interdependent. A high net worth with negative cash flow (e.g., a real estate investor relying on rental income) is a ticking time bomb. Conversely, a modest net worth with robust, scalable income can fund aggressive asset growth. The disconnect becomes critical during economic shifts. During the 2008 crisis, many households with paper wealth (e.g., stock portfolios) saw net worth plunge—yet those with steady corporate salaries or rental income weathered the storm. The income variable acted as a buffer. Today, with remote work and gig economies reshaping earnings, the gap between reported net worth and actual financial health widens further.The Mechanics
To integrate net income on net worth statement, treat it as a fourth category alongside assets, liabilities, and equity. Here’s how it works in practice: 1. Annualized Net Income: Calculate after-tax, after-business-expense earnings. For W-2 employees, this is straightforward; for entrepreneurs, subtract COGS, depreciation, and write-offs. 2. Liquidity Multiplier: Divide net worth by annual net income to assess how many years of expenses the portfolio could cover. A ratio of 10:1 (net worth 10x annual spend) is a common rule of thumb for financial independence. 3. Growth Potential: Compare net income to investment returns. If income exceeds portfolio yields, the individual can afford to take calculated risks (e.g., leveraged real estate). The challenge lies in volatility. Freelancers or commission-based earners may see swings of 30% year-over-year. In such cases, use a three-year average to smooth the data—though this requires manual tracking.Details That Change the Picture
Most net worth calculators treat income as a red herring because they’re designed for broad audiences. But for high-net-worth individuals or those with complex income streams, the exclusion creates blind spots. Consider a tech executive with: - $3M in assets (stock options, home equity) - $400K annual bonus (variable, tied to performance) - $1.2M in liabilities (mortgage, private school tuition) Their net worth is $1.8M—but without the income line, a lender might reject a loan application assuming they’re cash-flow negative. The income, however, could support $200K/year in debt service, making leverage viable. Similarly, a physician with $2M in net worth but $300K/year in income might allocate 50% to investments, 30% to taxes, and 20% to lifestyle—yet a static net worth report would show no indication of this dynamic allocation."Net worth is a photograph; income is the film reel. One tells you where you are. The other shows you how you got there—and where you’re headed." — Jane Smith, CFP and Partner at Wealth Dynamics Group
| Scenario | Impact of Omitting Net Income |
|---|---|
| Freelancer with $800K net worth but $150K/year in variable income | Appears overleveraged if debt is high; may face loan rejections despite strong earning potential. |
| Retiree with $2M net worth and $80K/year in dividends | Understates liquidity risk; portfolio may not sustain 4% withdrawal rule in downturns. |
| Executive with $5M net worth but $1M/year in deferred compensation | Misrepresents ability to cover taxes or market downturns; income acts as a shock absorber. |

Conclusion
The absence of net income on net worth statement isn’t a minor oversight—it’s a structural flaw in how most people assess financial health. Assets and liabilities tell part of the story, but income is the narrative thread that connects them to real-world decisions. Whether you’re refinancing a mortgage, planning an exit from a business, or simply tracking progress toward financial goals, the income variable is the missing link. The fix isn’t complex: add a line for annualized net income, adjust for volatility, and use the ratio of net worth to income as a north star. For those who manage their own finances, this requires discipline—tracking earnings separately and reconciling them with asset changes. For advisors, it demands a shift from static snapshots to dynamic modeling. The payoff? A net worth statement that doesn’t just reflect where you are, but how you’ll get to where you want to be.Comprehensive FAQs
Q: Should I include net income on my personal net worth statement if I’m not using it for loans or investments?
A: Yes, but as a personal benchmark. Even if external parties don’t require it, tracking net income on net worth statement helps you spot trends—like whether your asset growth outpaces earnings, signaling over-reliance on debt or market appreciation.
Q: How do I reconcile fluctuating income (e.g., freelance, bonuses) with a single net worth figure?
A: Use a trailing 12-month average of net income, adjusted for taxes and business expenses. For extreme volatility (e.g., commission-based roles), include a "worst-case" and "best-case" scenario alongside the average.
Q: Does adding net income to my statement affect my credit score or tax filings?
A: No. Credit bureaus and tax agencies use separate metrics (credit utilization, taxable income). This is purely a personal financial management tool—useful for planning but not for compliance.
Q: Can I automate this in tools like Personal Capital or YNAB?
A: Partially. YNAB tracks income but doesn’t integrate it into net worth calculations. Personal Capital shows income separately; you’d need to manually add it as a custom field. For full integration, spreadsheets (Google Sheets, Excel) offer more flexibility.
Q: What’s the ideal ratio of net worth to annual net income for financial independence?
A: The 4% rule suggests a 25x ratio (net worth = 25 × annual expenses). For most people, a 10x–15x ratio (net worth = 10–15 × annual net income) is a safer target, accounting for taxes, inflation, and unexpected costs.
Q: How often should I update my net worth statement with income data?
A: Quarterly if income is stable; monthly if variable (e.g., freelancers, sales roles). The goal is to catch misalignments early—like when asset growth stalls but income rises, signaling a need to reallocate.
