Where It All Began
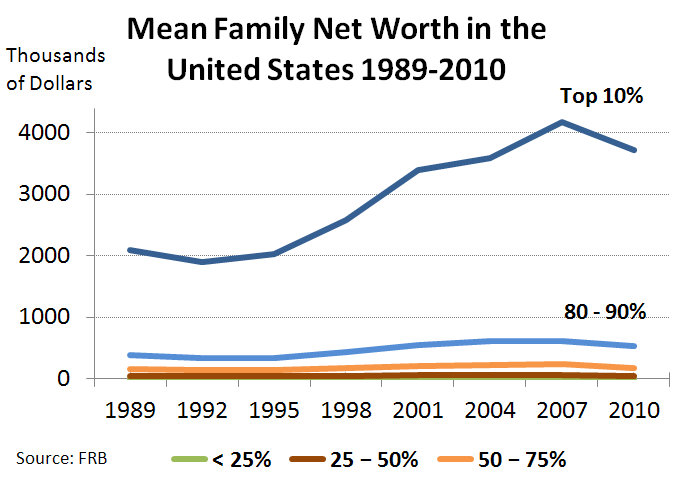
The seeds of America’s wealth were planted in violence and necessity. After the Revolutionary War, the young nation’s economy was a patchwork of agrarian self-sufficiency and fledgling trade. The real breakthrough came with the Industrial Revolution, which turned raw materials into factories, and factories into fortunes. By the late 1800s, railroads and steel barons like Carnegie and Rockefeller had created the first modern wealth machines. The U.S. wasn’t just accumulating capital—it was inventing new ways to hoard it. Trusts and monopolies concentrated wealth faster than any system before, but they also sparked backlash. The Sherman Antitrust Act of 1890 was an early attempt to corral the excesses, though its enforcement was half-hearted until the Progressive Era. The early 20th century brought two world wars, which paradoxically accelerated wealth accumulation. Government contracts, wartime production, and the New Deal’s infrastructure spending created a middle-class economy for the first time. The G.I. Bill (1944) turned soldiers into homeowners and college graduates, while unions negotiated wages that lifted entire regions. For a brief period, the question how much wealth is in the US had an optimistic answer: it was spreading. The postwar boom saw the top 1%’s share of wealth dip to 11% by 1976, the lowest in modern history. But beneath the surface, the foundations were shifting. Debt was rising, wages were stagnating, and the financial system was about to undergo a transformation that would redefine who got rich—and who got left behind.The Early Signs
The cracks appeared in the 1970s. Stagflation—high inflation paired with stagnant growth—eroded savings. The Volcker Shock of 1980, when the Federal Reserve slashed interest rates to crush inflation, also gutted corporate debt and set the stage for a new era: financialization. Banks, hedge funds, and private equity firms emerged as the dominant wealth creators, not manufacturers or farmers. The Tax Reform Act of 1986 slashed capital gains taxes, incentivizing asset speculation over wage growth. By the 1990s, the tech boom would turn Silicon Valley into a wealth factory, but the benefits were concentrated in a handful of cities and industries. The real inflection point came with the deregulation of the financial sector in the 1990s and 2000s. Glass-Steagall, the Depression-era law separating commercial and investment banking, was repealed in 1999. The result? Banks could now gamble with deposits, creating the conditions for the 2008 financial crisis. When the dust settled, the wealth gap had widened irrevocably. The top 1% recovered their losses within two years; the bottom 90% took eight. The crisis didn’t just redistribute wealth—it revealed that how much wealth is in the US was no longer a question of total size, but of who controlled the levers that created it.The Turning Point
The year 2008 wasn’t just a financial reckoning. It was a wealth reset. Before the crash, the U.S. household net worth had peaked at $68 trillion. Afterward, it plunged to $55 trillion. But the recovery that followed wasn’t a return to normalcy. It was a power grab. While Main Street struggled, Wall Street thrived. The Dodd-Frank Act, meant to prevent another crisis, did little to curb the rise of shadow banking—private credit markets where trillions in debt traded outside regulatory oversight. By 2012, the Federal Reserve’s quantitative easing programs had pumped $4.5 trillion into the economy, but most of it flowed to the top. The S&P 500 doubled in value between 2009 and 2013, while real wages for the bottom 90% stagnated. The turning point wasn’t just economic—it was ideological. The Trickle-Down 2.0 doctrine, which argued that tax cuts for the wealthy would stimulate growth, became gospel. Corporate tax rates fell from 35% in 2017 to 21%, while wages for non-supervisory workers grew at 1.3% annually—barely keeping pace with inflation. The result? The top 0.1% now owns more wealth than the entire bottom 90% combined. The question how much wealth is in the US became a proxy for a larger debate: Was America’s economy still a meritocracy, or had it become a financial aristocracy?"Wealth has ceased to be a reward for industry. It is now a reward for knowing where to find it." — John Kenneth Galbraith, economist (1958, but prophetic in 2024)
The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 1945–1970 | Postwar boom, unionization peaks, middle-class expansion. Top 1% wealth share hits 11% (lowest in modern history). How much wealth is in the US? Answer: broadly distributed, but still concentrated in manufacturing and real estate. |
| 1980–1999 | Reaganomics, deregulation, rise of finance. Top 1% wealth share climbs to 25%. Tech bubble inflates asset prices, but crashes in 2000. Wealth creation shifts to stock options and venture capital. |
| 2000–2008 | Housing bubble, subprime lending, shadow banking grows to $10 trillion+. When it bursts, $16 trillion in household wealth vanishes overnight. The recovery favors the top 10%. |
| 2010–Present | Ultra-low interest rates, corporate buybacks, private equity boom. Top 1% wealth share hits 40%. How much wealth is in the US? Now: $150 trillion, but 70% of it is owned by the richest 10%. |
Lessons From the Journey
- Wealth follows power. When policy favors asset holders over wage earners, inequality isn’t a bug—it’s the system’s design. The 1980s tax cuts and deregulation weren’t accidents; they were deliberate shifts toward financial elites.
- Crises redistribute wealth—but unevenly. The 2008 bailouts saved banks, not homeowners. The COVID-19 stimulus saw $1.9 trillion in aid, but 70% went to the top 20% via stock buybacks and capital gains.
- Debt is the silent wealth accumulator. Student loans, mortgages, and corporate debt keep the system running—but they also lock people into cycles of servitude. The rich borrow to invest; the poor borrow to survive.
- Globalization hollowed out the middle. When factories moved overseas, manufacturing jobs vanished, but the profits didn’t return. The U.S. became a consumer nation, not a producer one—and wealth followed the capital, not the people.
Where Things Stand Today
As of 2024, the total U.S. wealth stock—all assets from stocks to real estate to private equity—is estimated at $150 trillion. That’s $450,000 per person, but the median household wealth is $138,000, meaning half of Americans own less than that. The disparity isn’t just moral; it’s structural. The top 1% now holds more wealth than the bottom 90% combined, a first in modern history. And the composition of that wealth has shifted dramatically. In 1980, 60% of U.S. wealth was in tangible assets—homes, cars, businesses. Today, 70% is in financial assets—stocks, bonds, private equity—most of which are controlled by the top 10%. The question how much wealth is in the US today isn’t just about the number. It’s about who can access it. The richest 1% don’t just have more—they have different kinds of wealth. They own startups before they go public, private credit funds, and real estate portfolios that appreciate while most Americans struggle with rent. Meanwhile, the bottom 50% have seen their wealth grow at 0.2% annually since 2000. The system isn’t broken—it’s optimized for a few. And the tools of wealth creation—algorithms, lobbying, and regulatory capture—are now so sophisticated that the game is rigged before it even begins.
Conclusion
The story of how much wealth is in the US is more than a ledger entry. It’s a narrative of power, written in tax codes, deregulation, and the quiet decisions that shape who gets rich and who gets left behind. The numbers tell one story: $150 trillion and counting. The reality tells another: a society where opportunity is a privilege, not a right. The next decade will determine whether America’s wealth machine serves the many or the few. The signs are already there. The question is whether anyone will act on them before it’s too late. The wealth of a nation isn’t just its GDP. It’s the sum of its choices—and the U.S. has made its picks clear.Comprehensive FAQs
Q: How does the U.S. wealth total compare to other countries?
The U.S. holds roughly 40% of global wealth, far outpacing China (20%) and Europe (25%). While China’s GDP growth has been faster, America’s financial depth—stock markets, private equity, and dollar-denominated assets—keeps its wealth lead dominant. The total global wealth is estimated at $500 trillion, with the U.S. capturing nearly half.
Q: Who are the wealthiest individuals in the U.S.?
As of 2024, the top 10 wealthiest Americans include Elon Musk (reportedly $200B+), Jeff Bezos (~$170B), and Mark Zuckerberg (~$120B). However, private equity billionaires—like those in the Blackstone or KKR ranks—often fly under the radar because their wealth is tied to illiquid assets. The top 0.001% (about 1,500 people) own $10 trillion+ combined.
Q: How much wealth is lost in the U.S. due to inequality?
Studies suggest that $2 trillion in annual GDP growth is lost due to wealth inequality, as concentrated capital reduces consumer spending power. The Brookings Institution estimates that if wealth were distributed more evenly, the U.S. economy could grow 1-2% faster per year. The cost isn’t just economic—it’s social, with lower life expectancy, higher crime rates, and weaker civic trust in high-inequality areas.
Q: What role does the stock market play in U.S. wealth?
The S&P 500 alone accounts for ~$40 trillion in market cap, or 25% of total U.S. wealth. Since 40% of Americans own no stock, the market’s growth primarily benefits the top 10%. Retirement accounts (401ks, IRAs) have shifted wealth from pensions to equities, but only 56% of households participate. The 2020s bull market added $30 trillion to U.S. wealth, but 80% of that went to the top 10%.
Q: Could U.S. wealth decline in the future?
Potential risks include:
- Debt overload: U.S. national debt is $34 trillion, and corporate debt has hit $12 trillion. A crisis could trigger defaults.
- Geopolitical shifts: If the dollar loses reserve status (unlikely soon), $100 trillion in global dollar-denominated assets could face volatility.
- Climate change: $1.5 trillion in U.S. real estate is at risk from sea-level rise and wildfires.
- Policy changes: A wealth tax (like France’s failed attempt) or breakup of monopolies could redistribute capital.
Q: How does wealth distribution affect politics?
The top 0.1% donate 40% of all political campaign funds, shaping policy in ways that protect asset values. The Citizens United ruling (2010) allowed unlimited dark money spending, further tilting the playing field. Tax cuts for the wealthy (like the 2017 Tax Cuts and Jobs Act) have increased the deficit by $2 trillion, but 83% of the benefits went to the top 1%. The result? A two-tiered democracy where policy favors capital over labor.
Q: Are there any signs wealth inequality is improving?
Marginal improvements exist but are outpaced by worsening trends:
- Minimum wage increases (e.g., $15/hour laws) have lifted 10 million workers out of poverty.
- Student debt relief (limited by courts) could boost Black and Latino wealth by $100B+ over a decade.
- ESG investing (environmental/social governance) is growing, but only 10% of assets are truly aligned with equity goals.
- Housing vouchers (expanded in 2023) help 5 million low-income families, but only 25% of eligible households receive aid.
