The Short Answers
- For most people in their 20s–30s, a net worth increase of 10–20% annually is achievable with disciplined saving and moderate investment returns, assuming no major debt.
- In your 40s–50s, growth slows to 5–15% per year unless you’re adding high-earning assets (e.g., a business, real estate, or stock options).
- If your net worth isn’t rising at all, you’re likely spending more than you earn, holding too much cash, or facing stagnant income—all fixable with strategy.
- Wealth growth accelerates when you shift from saving to asset accumulation (e.g., buying a home, investing in equity, or launching a side business).

Deep Dive: The Full Picture
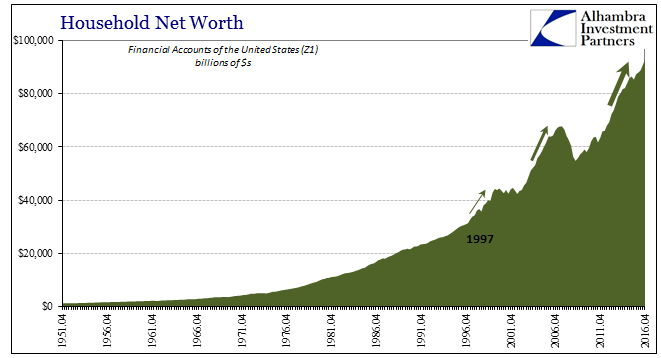
Net worth growth isn’t linear. It follows a career-stage curve: flat in early years (when expenses match income), then exponential during peak earning decades, and finally decelerating in retirement if you’re not reinvesting. The question how much should my net worth rise by year has no one-size-fits-all answer, but the data reveals patterns. A 2023 Federal Reserve report showed that the median net worth for households aged 32–47 was around $180,000—meaning most people in that bracket were adding $10,000–$30,000 annually to their net worth during their prime earning years. For the top 10%, the figure jumps to $50,000+ per year, driven by higher incomes, asset appreciation, and tax-advantaged accounts. The catch? Those median numbers mask volatility. A software engineer in Austin might see their net worth spike 30% one year thanks to a stock grant vesting, only to dip 10% the next due to a market correction. Meanwhile, a nurse in Detroit with a $200,000 mortgage might see zero growth for years despite saving aggressively. The key isn’t chasing a percentage but ensuring your growth outpaces inflation—historically 3–4% annually—while accounting for your personal risk tolerance.The Context You Need
Your baseline growth rate depends on three variables: 1. Income trajectory: A promotion that bumps your salary from $80K to $120K can add $40K/year to your net worth if you save half. A stagnant salary means slower growth. 2. Debt load: Carrying $50K in student loans at 6% interest will eat into your net worth gains until you pay it down. Eliminating debt is often the fastest way to boost annual net worth growth by 5–15%. 3. Asset allocation: Someone with a diversified portfolio (stocks, real estate, retirement accounts) will see compounding effects over time, while someone holding cash or bonds may stagnate. Industry estimates suggest that high-income earners (top 20%) see their net worth grow 1.5–2x faster than the median due to leverage (mortgages, business loans) and higher savings rates. But leverage is a double-edged sword: a real estate investor might see 12% annual growth in a hot market, only to face negative equity in a downturn.The Mechanics
The math behind how much your net worth should rise by year breaks down like this: - Income minus expenses = savings rate. If you save 20% of a $100K salary, that’s $20K/year. Invested at 7% annual return, that grows to $21,400 in Year 1, then $23,000 in Year 2, and so on. - Asset appreciation (stocks, real estate) adds to growth. A $300K home appreciating at 4% adds $12K/year to net worth without lifting a finger. - Debt reduction is often the most underrated lever. Paying down a $30K car loan at 5% interest saves $1,500/year in interest, effectively increasing net worth by that amount. The mistake many make? Focusing only on investment returns while ignoring liquidity and cash flow. A doctor with $500K in student loans might have a high net worth on paper but feel financially trapped. The real question isn’t just how much your net worth should rise by year, but how much usable wealth you’re generating.Details That Change the Picture
Location matters more than most realize. In San Francisco, a $150K salary might yield $10K/year in net worth growth after housing costs, while the same salary in Dallas could net $30K/year. Taxes, local market conditions, and cost of living distort the numbers. Then there’s career volatility: a layoff, industry shift, or health crisis can reset progress overnight. The 2008 financial crisis wiped out 10–20% of net worth for many households, and the pandemic did the same in 2020. What’s often overlooked? The psychology of growth. A 5% annual increase feels like failure if you expected 10%, even if it’s a strong result. The answer to how much your net worth should rise by year isn’t just numerical—it’s about adjusting expectations to your stage of life. A 30-year-old with $50K in net worth shouldn’t compare themselves to a 45-year-old with $500K. The latter had 15 years of compounding; the former is just starting."Wealth isn’t about hitting a target; it’s about controlling the variables you can—saving rate, debt, career choices—and accepting that external forces will dictate the rest." —Morgan Housel, The Psychology of Money
| Career Stage | Typical Net Worth Growth Range (Annual) |
|---|---|
| Early career (20s–early 30s) | 5–15% (if saving aggressively; lower if in debt) |
| Prime earning years (35–50) | 10–25% (with asset appreciation and high income) |
| Late career (50+) | 3–12% (slower unless reinvesting or generating passive income) |
| Retirement (60+) | 0–5% (preservation mode; growth depends on withdrawals) |

Conclusion
The question how much should my net worth rise by year has no perfect answer, but the framework is clear: growth is a function of income, spending, and asset allocation. What’s achievable for one person isn’t for another, and that’s okay. The goal isn’t to hit a specific percentage but to outpace inflation, reduce debt, and build assets that generate future growth. Start by calculating your current net worth growth rate (annual increase ÷ net worth). If it’s below 5%, you’re likely spending too much or not investing enough. If it’s above 20% consistently, you might be taking unnecessary risks. The sweet spot? A growth rate that feels sustainable, aligns with your goals, and accounts for the unpredictability of life.Comprehensive FAQs
Q: My net worth isn’t growing at all. What’s wrong?
You’re likely in one of three scenarios: (1) Your expenses equal or exceed your income (no savings), (2) You’re holding too much cash or low-yield assets (missing out on market returns), or (3) You have high-interest debt (e.g., credit cards, personal loans) that’s eroding your progress. Prioritize cutting discretionary spending, paying down debt, and redirecting savings to investments.
Q: Should I aim for a specific percentage growth each year?
Not rigidly. Use percentages as a guideline, not a rule. A better approach is to set absolute dollar targets (e.g., "Add $20K/year to net worth") and adjust based on market conditions. For example, if stocks crash but your salary increases, you might still hit your dollar goal even if the percentage drops.
Q: Does my age affect how much my net worth should rise?
Absolutely. Younger people (under 35) should focus on building savings and reducing debt, which may mean slower percentage growth but stronger long-term foundations. Those in their 40s–50s can afford to take more risk (e.g., real estate, stocks) to boost growth to 10–20% annually. After 60, preservation becomes the priority.
Q: How do market downturns affect my net worth growth?
Downturns can temporarily compress your net worth (e.g., a 20% stock market drop reduces paper wealth), but they’re also buying opportunities. Historically, markets recover—and if you’re consistently adding to investments (dollar-cost averaging), downturns can increase your average purchase price, setting you up for higher future returns.
Q: What’s the fastest way to increase my net worth growth?
Three levers move the needle fastest: (1) Increase income (negotiate a raise, switch jobs, or start a side hustle), (2) Eliminate high-interest debt (credit cards, payday loans), and (3) Invest in appreciating assets (index funds, real estate, or a business). Even small tweaks—like refinancing a mortgage or automating savings—can add $5K–$20K/year to your growth.
Q: Is it better to focus on net worth or cash flow?
Both matter, but cash flow is the foundation. You can have a high net worth (e.g., a paid-off home) but struggle with monthly expenses. The ideal balance: Strong cash flow (enough to cover needs and save) + assets that grow over time (retirement accounts, investments, real estate). If your cash flow is negative, net worth growth will stall.
Q: How do I adjust my expectations if I’m behind on net worth growth?
First, stop comparing yourself to others. Then, recalibrate: (1) Reduce non-essential spending (even small cuts add up), (2) Increase income streams (freelancing, rental income, etc.), and (3) Extend your timeline—wealth is a marathon, not a sprint. If you’re in your 30s, you still have 20–30 years of compounding ahead.
