
The Short Answers
- There’s no universal "right" amount for average 25-year-old savings—context matters more than the number.
- In the U.S., $10K–$20K is a rough midpoint, but $0–$5K is more common for lower earners.
- Student debt and rent prices are the biggest wildcards affecting these figures.
- Saving 3–6 months’ expenses by 25 is a stronger goal than hitting a dollar target.
- Location dictates everything: a $25K savings in Austin might be "average," but in NYC it’s a red flag.

Deep Dive: The Full Picture
Average 25-year-old savings statistics are useful only as starting points. They ignore the fact that a 25-year-old in healthcare might have $3K saved but $100K in student loans, while a 25-year-old in sales could have $40K saved but no safety net. The real question isn’t "How much should I have?" but "What does my savings enable me to do?" Can you cover a $5K emergency? Afford a $10K down payment on a car? Walk away from a toxic job? These are the metrics that matter more than the balance itself. The data also obscures behavioral trends. Younger generations are saving more than previous ones at the same age—but they’re also facing higher costs. A 2023 Bankrate survey found that 42% of Gen Z and Millennials have less than $1K saved, up from 35% in 2020. Yet, those with stable incomes are prioritizing high-interest debt repayment over traditional savings, a shift that redefines what "savings" even means. The average 25-year-old savings account balance is less important than understanding whether that money is working for you—or just sitting idle in a low-yield account.The Context You Need
Income inequality at 25 is stark. A 2024 Federal Reserve report showed that the top 10% of 25-year-olds earn over $100K annually, while the bottom 10% earn under $20K. That income gap directly translates to savings: the former group can save $1K/month; the latter might save $100. Even within the same income bracket, location destroys averages. Rent in Los Angeles eats 50% of a $50K salary; in Indianapolis, it’s 25%. A $15K savings in L.A. might cover three months of rent; in Indianapolis, it’s nine. Cultural shifts also reshape savings. The rise of side hustles means some 25-year-olds treat savings as a variable expense—money set aside only after gig income or bonuses. Others, especially in gig economies, have no traditional savings but rely on cash flow from irregular work. The average 25-year-old savings figure becomes meaningless when you realize half the population might not even have a dedicated savings account—let alone a balance.The Mechanics
The mechanics of average 25-year-old savings boil down to three levers: income, expenses, and debt. High earners save more not because they’re frugal, but because their savings rate is a byproduct of disposable income. A $150K earner saving $1K/month has a 0.7% savings rate; a $40K earner saving $300/month has a 7.5% rate. The problem? Fixed costs (rent, student loans, healthcare) often absorb the majority of that $40K, leaving little room for growth. Debt is the silent killer. A 25-year-old with $40K in student loans at 6% interest might allocate $500/month to debt repayment—money that could’ve gone to savings. This is why net worth (assets minus liabilities) is a better metric than raw savings. A 25-year-old with $5K in savings but $50K in student loans has a net worth of -$45K, while one with $10K saved and $10K in loans has a net worth of $0. The average 25-year-old savings number ignores this critical distinction.Details That Change the Picture
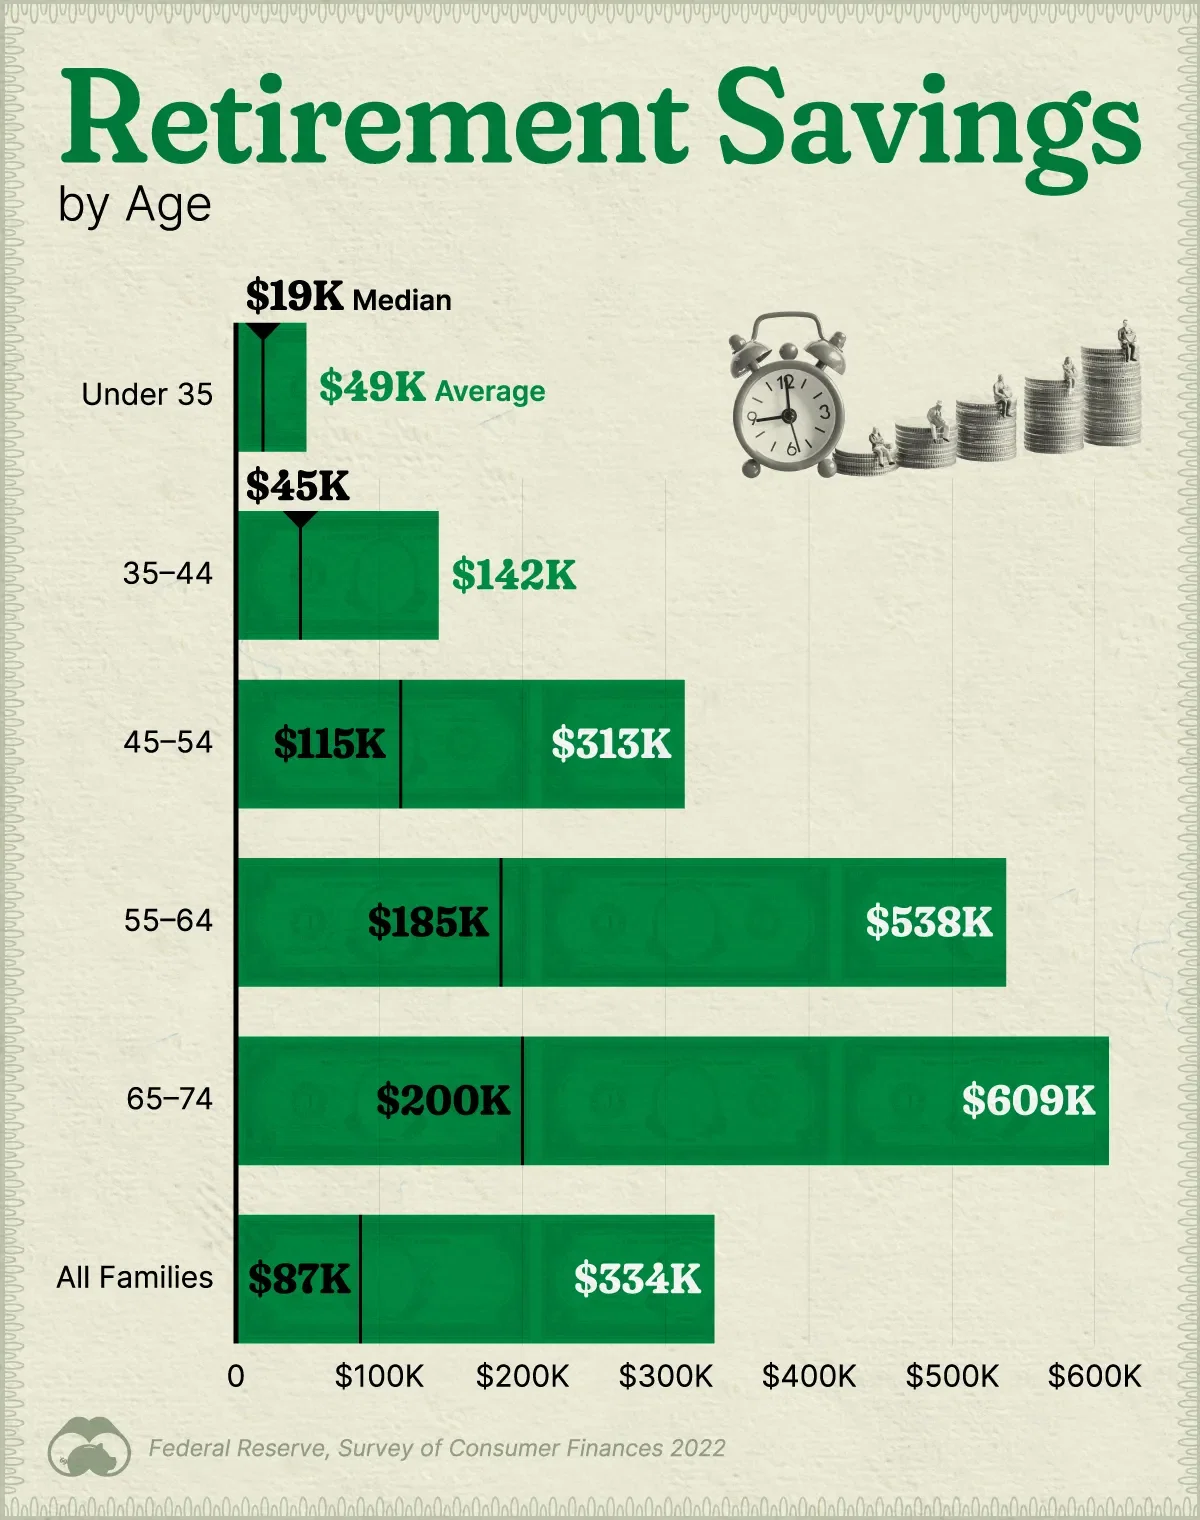
The average 25-year-old savings figure is a moving target. In 2019, the median savings for this age group was $5K; by 2023, it had dropped to $3K due to inflation and pandemic disruptions. Yet, those with employer-sponsored retirement accounts (like 401(k)s) often see their "savings" inflated by matched contributions—money they didn’t personally save. Exclude that, and the real personal savings picture looks bleaker. The average 25-year-old might have $12K in a 401(k) but only $3K in a high-yield account—two entirely different financial realities. What’s often overlooked is the opportunity cost of not saving. A 25-year-old who saves $5K now could see it grow to $50K by 65 with a 7% annual return. But if they save nothing until 30, they’d need to save $10K/year to reach the same goal. The average 25-year-old savings debate isn’t just about dollars—it’s about time decay. Every year delayed is a compounding penalty on future wealth."The average 25-year-old savings number is a distraction. What matters is whether you’re saving more than you spend, not whether you hit some arbitrary benchmark. If you’re saving 10% of your income and paying down high-interest debt, you’re ahead of 70% of your peers—regardless of the balance." — Tiffany "The Budgetnista" Aliche, financial educator
| Factor | Impact on Savings |
|---|---|
| Student debt load | Delays savings by 3–5 years for the median borrower. |
| Rent as % of income | Above 30%? Savings drop by 40% on average. |
| Employer 401(k) match | Can inflate "savings" by 3–5% of salary without personal effort. |
Conclusion
The obsession with average 25-year-old savings is misplaced. The number itself is less important than what it represents: financial resilience, flexibility, and the ability to absorb shocks. A 25-year-old with $20K saved but $80K in debt is in a far different position than one with $5K saved and no debt—even though the latter’s balance is "below average." The goal isn’t to chase a benchmark but to build a system where savings grow faster than expenses. That system starts with three non-negotiables: 1. An emergency fund (even if it’s just $1K). 2. Debt prioritization (high-interest debt first). 3. Automated savings (even $50/month compounds over time). The average 25-year-old savings figure is a starting point, not a destination. The real work begins when you stop comparing your balance to others’ and instead ask: "Is my money working for me—or against me?"Comprehensive FAQs
Q: Is $5,000 a good amount for a 25-year-old to have saved?
A: It depends. If you have no high-interest debt, a stable income, and live below your means, $5K is a solid foundation—especially if it’s in a high-yield account. But if you’re paying 10%+ interest on loans or face unpredictable expenses (like healthcare costs), $5K may not cover emergencies. The better question: Does this amount give you peace of mind? If not, focus on consistent saving rather than hitting a dollar target.
Q: Why do some 25-year-olds have $0 saved?
A: Reasons vary: - Low income (e.g., minimum wage + part-time work). - High fixed costs (student loans, childcare, medical debt). - Lack of financial education (many never learned to prioritize savings). - Irregular income (gig work, freelancing, seasonal jobs). - Emergency spending (car repairs, medical bills, family support). The average 25-year-old savings figure doesn’t account for these realities—$0 isn’t necessarily "bad" if it’s a temporary phase. The key is rebuilding with small, consistent steps.
Q: Should I save aggressively at 25, or invest instead?
A: The ideal is both, but the order matters. Start with: 1. A $1K emergency fund (or enough to cover one major expense). 2. High-interest debt repayment (credit cards, personal loans). 3. Retirement accounts (even $50/month in a 401(k) or IRA). 4. Broader savings (high-yield savings, CDs, or low-risk investments). At 25, time is your greatest asset—but only if you’ve covered the basics. Dumping money into stocks before securing an emergency fund is a gamble. The average 25-year-old savings strategy should balance liquidity (savings) and growth (investments) based on risk tolerance.
Q: How does rent affect average 25-year-old savings?
A: Rent is the single biggest destroyer of savings for this age group. Here’s how: - If rent consumes 30%+ of your income, you’ll save 40% less than someone paying 20%. - In high-cost cities, a $2,000/month rent on a $50K salary leaves $1,500 for everything else—including savings. That’s $18K/year for housing alone. - The average 25-year-old savings in cities like NYC or SF is 2–3x lower than in midwestern cities, even for similar incomes. Solution: Negotiate rent, consider roommates, or prioritize rent stability over location. A $100/month rent reduction = $1,200/year that could go to savings.
Q: What’s the fastest way to improve average 25-year-old savings?
A: Three high-impact moves: 1. Cut one major expense (e.g., switch to a cheaper phone plan, cancel subscriptions). 2. Increase income (ask for a raise, take on a side hustle, monetize a skill). 3. Automate savings (even $100/month adds up—set up auto-transfers the day you get paid). The average 25-year-old savings won’t change overnight, but small, consistent actions compound. For example, saving an extra $200/month for two years = $4,800—enough to double a modest balance. The key is starting before you feel "ready."
