
Breaking Down the Numbers
The debate over what percentage of my net worth should my house be often starts with the 20% rule—a heuristic popularized by financial advisors suggesting that housing should not exceed 20% of net worth for early-career buyers. This aligns with the "one-third rule" from the 1990s, which advised capping housing costs at one-third of gross income. Yet both metrics assume stable incomes and predictable appreciation—neither holds in today’s markets. For example, a 2021 Redfin analysis found that first-time buyers in Austin now allocate 35-50% of net worth to down payments alone, thanks to price surges and stagnant wages. The 20% rule, in short, is a relic of pre-2008 economics. What’s missing from these guidelines is context. A home in Detroit might represent 80% of net worth for a retired couple on fixed income, while the same percentage in Dallas could signal financial distress. The critical factor isn’t the number itself, but whether the home serves as a hedge against inflation or a drag on liquidity. High-net-worth individuals often hold property at 10-15% of net worth, diversifying the rest into stocks or private equity. The ultra-wealthy, meanwhile, treat primary residences as liability shields—allocating 5-10% while parking cash in offshore trusts or alternative assets. The question what percentage of my net worth should my house be thus reveals more about your risk profile than your balance sheet.The Verified Baseline
Public data offers three verifiable benchmarks. First, the Federal Housing Finance Agency (FHFA) tracks home price-to-income ratios, which hit 5.3x in 2023—meaning the median home costs over five years’ income. This implies that for a household earning $100,000, a $530,000 home would represent roughly 40-50% of net worth (assuming $1.2M in assets). Second, the U.S. Census Bureau reports that homeowners aged 35-44 allocate 30-40% of net worth to property, while those 55+ allocate 50-60%. The third data point comes from Black Knight’s Mortgage Monitor, which shows that borrowers with loan-to-value ratios above 80%—common among first-time buyers—see home equity dip below 20% of net worth in the first five years of ownership. These figures are not recommendations, but snapshots of reality. A 2022 study in the Journal of Housing Economics found that households allocating more than 50% of net worth to housing experience 30% higher financial distress rates during recessions. The correlation isn’t causal, but it underscores why planners warn against treating homes as savings accounts. The answer to what percentage of my net worth should my house be isn’t static—it’s a moving target tied to debt levels, local markets, and career stability.What the Estimates Suggest
Industry estimates vary widely, but three schools of thought emerge. Conservative planners (e.g., Vanguard, Fidelity) suggest 10-20% for young buyers, arguing that early-career households should prioritize liquid assets and emergency funds. This aligns with the "10% rule" from The Simple Path to Wealth, which advises keeping housing below 10% of net worth until age 40. Moderate advisors (e.g., Suze Orman, David Bach) recommend 20-30% for mid-career buyers, framing homes as long-term investments but warning against over-leveraging. Their logic: a 30% allocation leaves room for stocks, bonds, and cash reserves without exposing the household to systemic risk. Speculative estimates push higher. Real estate brokers in hot markets often cite 30-50% as "healthy" for clients who view property as a hedge against inflation or tax liabilities. A 2023 survey by the National Association of Realtors (NAR) found that 42% of agents believe buyers should allocate 40-60% of net worth to primary residences, particularly in areas with strong rental demand. Critics dismiss this as conflict-of-interest advice, noting that agents profit from higher home values. The most extreme estimates—60%+ for retirees—reflect a strategy of equity extraction (e.g., reverse mortgages) to fund living expenses, but this carries significant downside risk.
Case Study: A Closer Look
Consider the case of the Smiths, a dual-income couple in Seattle with combined net worth of $1.5 million. In 2018, they purchased a $950,000 home with a 20% down payment ($190,000), leaving them with $1.31M in liquid assets. By 2023, their home was worth $1.3M (a 37% gain), but their net worth had grown to $2.1M due to stock market appreciation. Their home now represents 62% of net worth—far above the 20% heuristic. Yet they’re financially secure: their mortgage is paid off, they hold $800K in diversified investments, and their emergency fund covers two years of expenses. The Smiths’ allocation reflects strategic concentration—they treat their home as a non-liquid but appreciating asset, not a monthly burden. Their story highlights the flaw in percentage-based rules. The Smiths’ 62% allocation would trigger alarms for a 35-year-old, but it’s sustainable for them because: 1. Their income is stable (no freelance volatility). 2. Their home is in a high-appreciation market (Seattle’s median price rose 120% since 2010). 3. They’ve offset risk with liquidity (no reliance on home equity for cash flow)."We don’t think of our home as part of our ‘investable’ net worth. It’s a place to live, not a stock position. The numbers don’t matter if the roof stays dry." — Sarah Smith, Seattle homeowner (name changed)| Factor | Estimated Impact on Net Worth Allocation | |--------------------------|-------------------------------------------------------------------------------------------------------------| | Market Appreciation | +10-20% (Seattle’s gains outpaced inflation; other markets lag) | | Debt Leverage | -5-15% (Mortgage paydown reduces risk; high LTV ratios increase it) | | Liquidity Needs | -10-30% (Retirees may allocate more; early-career buyers less) | | Tax Strategy | ±5-10% (Primary residence exemptions reduce effective cost; capital gains taxes add it) | The Smiths’ case proves that what percentage of my net worth should my house be depends on how you define "net worth." Exclude the home, and their allocation drops to 25%. Include it, and the math changes entirely. The lesson? Percentages are tools, not rules.
What This Means Going Forward
The answer to what percentage of my net worth should my house be will evolve with three trends. First, rising interest rates are pushing buyers toward lower loan-to-value ratios, which naturally reduces home-related net worth exposure. Second, remote work flexibility is allowing households to trade high-cost primary residences for secondary properties, diversifying risk across markets. Third, generational shifts—millennials delaying homeownership, Gen X prioritizing liquidity—are creating asymmetric allocations where housing’s role in net worth varies by cohort. For young buyers, the optimal percentage may shrink further. A 2023 Bankrate survey found that 38% of millennials now aim for 0-10% of net worth in housing, deferring purchases until they can afford all-cash or near-cash deals. This reflects a cultural shift: younger generations view homeownership as one asset among many, not the cornerstone of wealth. Meanwhile, retirees are reversing the trend, using home equity to replace lost income streams—a strategy that works in bull markets but fails in downturns.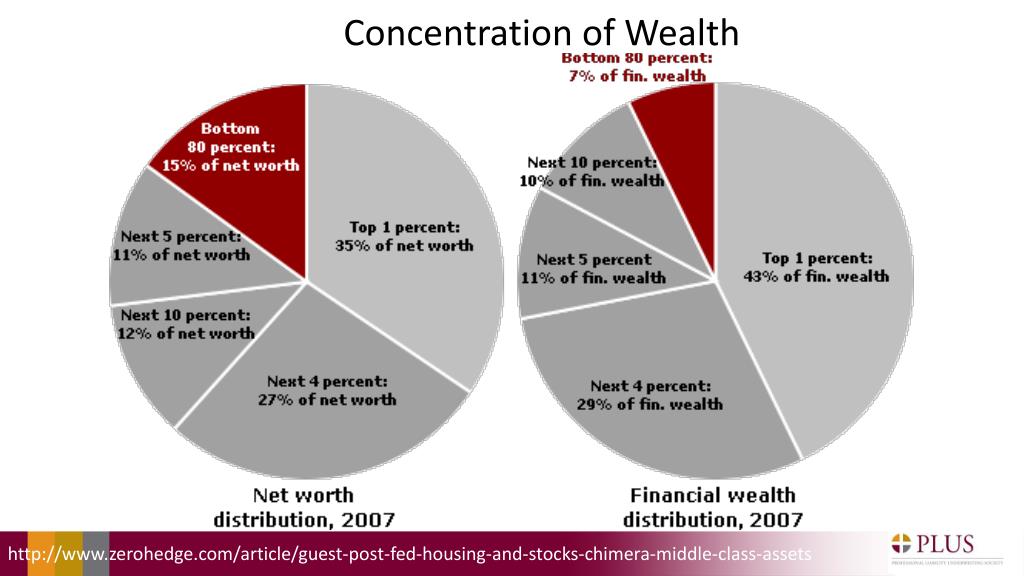
Conclusion
There is no single answer to what percentage of my net worth should my house be, only frameworks. The 20% rule is a starting point for the young, but retirees may need 50% or more to maintain lifestyle stability. The key is aligning your allocation with your goals: Is housing a forced savings vehicle, a liability shield, or a speculative play? The data shows that households allocating 30-50% of net worth to property tend to outperform those at the extremes—either under-leveraged (missing growth) or over-leveraged (risking distress). But the numbers alone won’t tell you what to do. The best approach is dynamic. Reassess your home’s share of net worth annually, adjusting for market shifts, career changes, and liquidity needs. If your home’s percentage creeps above 50% without offsetting liquidity, consider downsizing, refinancing, or diversifying. The question what percentage of my net worth should my house be isn’t about hitting a target—it’s about balancing security and opportunity. And in an era of volatile markets, that balance is more precarious than ever.Comprehensive FAQs
Q: Should I aim for a lower percentage if I’m early in my career?
A: Yes, but with caveats. Early-career buyers often benefit from lower allocations (10-20%) because housing costs eat into income growth. However, if you’re in a high-appreciation market (e.g., Austin, Nashville) and can afford all-cash or near-cash purchases, a slightly higher percentage (20-30%) may make sense—provided you maintain liquidity for emergencies. The trade-off is opportunity cost: capital tied to a home can’t be invested elsewhere. A 2022 study by the St. Louis Fed found that households allocating less than 20% to housing had 25% higher median net worth growth over 10 years, but only if they reinvested the difference in diversified assets.
Q: What if my home’s percentage of net worth spikes during a market downturn?
A: This is a red flag, not a crisis—unless you’re underwater. During downturns, home values can drop 10-30% in hot markets (e.g., 2008, 2022), temporarily inflating your home’s share of net worth. If your mortgage is paid off or well below market value, this may not matter. But if you’re highly leveraged (LTV > 70%), a 20% drop in home value could push your allocation from 40% to 60% overnight. The solution? Maintain a 6-12 month emergency fund and avoid equity-dependent spending (e.g., HELOCs for vacations). Pro tip: Track your home equity-to-net worth ratio quarterly, not just the headline percentage.
Q: Does it matter if my home is in a high-tax state?
A: Absolutely. In states like California or New York, property taxes and capital gains can erode net worth faster than in low-tax states. For example, a $1M home in California might cost $12K/year in property taxes (1.2% of value), while the same home in Texas could cost $4K/year (0.4%). If you’re allocating 40% of net worth to housing, those taxes add up. High-tax states also penalize home sales with capital gains taxes (up to 20% federally + state rates). The fix? Deduct mortgage interest (if itemizing), defer capital gains via the primary residence exemption ($250K/$500K), or consider secondary properties in low-tax states to diversify exposure.
Q: Can I safely allocate more than 50% if I’m retired?
A: It’s possible, but only with guardrails. Retirees often allocate 50-70% to housing because home equity replaces lost income streams (e.g., reverse mortgages, renting out rooms). However, this strategy assumes: 1. Stable home values (no 2008-style crashes). 2. Low debt (preferably paid-off mortgages). 3. Alternative income (pensions, Social Security, or rental income). A 2023 AARP study found that retirees with >60% of net worth in housing had 30% lower median savings but higher quality of life if they lived in low-cost areas. The risk? Illiquidity: If you need cash for medical expenses, tapping home equity via a reverse mortgage adds debt. The safer approach is capping allocations at 50% unless you have offshore liquidity or trust-fund backstops.
Q: How do I adjust if my home’s value surges beyond my target percentage?
A: This is a good problem to have, but it requires proactive management. If your home’s share of net worth jumps from 30% to 50% due to appreciation, consider: - Downsizing (selling and reinvesting the difference). - Investing the gains (e.g., selling a second home and diversifying). - Shifting to a lower-tax state (if relocation is feasible). - Using the proceeds to pay off high-interest debt (e.g., credit cards). The key is not to treat windfalls as free money. A 2021 Harvard Joint Center for Housing Study found that homeowners who reinvested windfalls into stocks saw 2.5x higher net worth growth over 15 years than those who spent or saved the gains passively. If you’re unsure, consult a fee-only fiduciary planner—not a real estate agent—to model the tax and liquidity impacts.
