Where It All Began
The idea that net worth should grow in lockstep with income isn’t new. It traces back to the 1930s, when economists first started tracking household balance sheets during the Great Depression. What they found was that families who survived the crash weren’t the ones with the highest incomes—they were the ones whose debts were minimal and whose assets (often just a home or a small business) outstripped their liabilities. The ratio of net worth to income became an unofficial measure of resilience. By the 1960s, financial advisors in the U.S. and Europe had begun using rough benchmarks: a young professional should aim to have a net worth equal to their annual after-tax income by age 30, doubling it by 40, and tripling it by 50. These weren’t hard rules, but they provided a framework for what healthy wealth accumulation looked like.
The problem was, most people ignored them. In the post-war boom, consumer credit exploded, and the idea that spending was synonymous with success took root. By the 1980s, the gap between income and net worth had widened dramatically. A study from the Federal Reserve in 1989 showed that the median net worth of households headed by someone in their 30s was just 0.8x their annual after-tax income. For those in their 40s, it was 1.5x. The message was clear: the % of income after taxes that should be net worth was being systematically undershot. The financial crisis of 2008 only exposed how fragile this imbalance was. Millions of high earners with thin net worths found themselves underwater on mortgages, drowning in debt, while those with even modest net worths weathered the storm.
#### The Early Signs
The first real push to quantify what % of income after taxes should be net worth came from the "financial independence" movement in the early 2000s. Bloggers like Mr. Money Mustache and Jacob Lund Fisker (of Early Retirement Extreme) popularized the idea that if your net worth was 25x your annual expenses, you could retire early. But they rarely framed it in terms of income. The missing link was income itself. If you’re spending $60,000 a year, but earning $150,000, does a net worth of $1.5 million (25x expenses) make sense? Not if your after-tax income is only $100,000—because that means your net worth should be at least $200,000 to $500,000 just to cover basic living costs without touching principal. The confusion stemmed from a fundamental misalignment: most financial advice focuses on savings rates (e.g., "save 20% of your income") rather than net worth growth. But savings are just a snapshot; net worth is the cumulative result. A 30-year-old earning $80,000 after taxes who saves $16,000 a year will have $160,000 in savings by age 40—assuming no investments. That’s 2x their income, which aligns with the early benchmark. But if they spend that $16,000 on a car, a wedding, and travel, their net worth might only grow by $50,000 over a decade. The question what % of income after taxes should be net worth isn’t about savings; it’s about whether your assets are growing faster than your lifestyle.The Turning Point
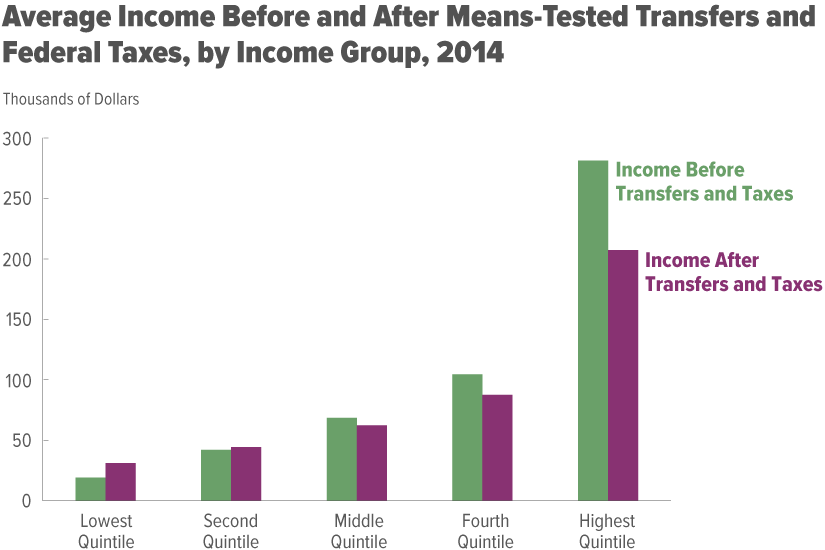
The shift came in 2012, when a team of researchers at the University of Chicago Booth School of Business analyzed net worth trajectories across income percentiles. They found that the median net worth of a 35-year-old in the top 20% of earners was 3.2x their after-tax income. For those in the bottom 20%, it was 0.4x. The disparity wasn’t just about income—it was about how much of that income was being converted into lasting wealth. The researchers dubbed this the "net worth multiplier," and it became the first data-driven answer to what % of income after taxes should be net worth.
What made the study different was its focus on after-tax income, not gross. A $200,000 gross salary doesn’t mean much if 40% of it goes to taxes and debt payments. The real test was whether a person’s take-home pay was being funneled into assets (home equity, investments, business ownership) rather than liabilities (credit cards, car loans, student debt). The turning point wasn’t a policy change or a new investment strategy—it was the realization that net worth growth was a function of income minus lifestyle inflation, not just income alone.
"People assume that because they earn more, they should spend more. But the wealthiest households don’t live like they’re keeping up with the Joneses—they live like they’re building a legacy." — Dr. Harold Pollack, University of Chicago economist
The Build-Up, Year by Year
| Period | What Happened / What Changed | Impact on Net Worth Benchmarks |
|------------------|--------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|---------------------------------------------------------------------------------------------------------------------------|
| 1990s | Rise of consumer debt (credit cards, mortgages), dot-com boom/bust. Net worth benchmarks fell as people leveraged income for lifestyle spending. | Median net worth-to-income ratio dropped below 1x for many households. |
| 2000–2008 | Housing bubble inflated home equity (counted as net worth). High earners borrowed against assets, assuming perpetual growth. | Net worth ratios spiked artificially—until the crash. Median ratios halved for many. |
| 2010–2020 | Shift to passive investing (index funds, ETFs), gig economy, and delayed retirement. Advisors began emphasizing net worth over savings rates. | Benchmarks like "2x by 35" and "5x by 45" gained traction as rules of thumb. |
#### Lessons From the Journey
1. Debt is the silent killer of net worth ratios. A $100,000 salary with $50,000 in student loans and a $30,000 car payment leaves little room for asset-building. The what % of income after taxes should be net worth question becomes meaningless if most of your income is servicing debt. 2. Homeownership distorts the metric. A paid-off home can inflate net worth artificially, making it seem like you’re ahead—even if your liquid assets are stagnant. The real test is whether your home equity is growing faster than your income. 3. Career volatility matters more than salary. A doctor earning $300,000 but with $200,000 in student loans may have a lower net worth ratio than a plumber earning $80,000 with no debt. Consistent after-tax cash flow beats high income alone. 4. Inflation erodes benchmarks over time. A net worth of 3x after-tax income was once a safe target in the 1980s. Today, with rising costs, the same ratio might only cover 10 years of expenses—hardly a buffer. 5. The 2x–5x rule isn’t static. For high-cost cities, the lower end (2x) might be more realistic. For remote workers or those with low living expenses, 5x could be achievable earlier.Where Things Stand Today
Today, the question what % of income after taxes should be net worth is less about rigid benchmarks and more about personalized resilience. The median net worth of a 35-year-old in the U.S. is now estimated at 1.5x their after-tax income, up from 0.8x in the 1990s—but that’s skewed by the ultra-wealthy. For the middle class, the ratio has stagnated. The problem isn’t that people don’t know the answer; it’s that they don’t ask the question until it’s too late.
What’s changed is the tooling. Apps like Personal Capital and YNAB now track net worth-to-income ratios in real time, making it easier to spot when you’re falling behind. The benchmark itself has evolved: financial planners now suggest 1x by 30, 3x by 40, and 5x by 50 as a starting point, with adjustments for debt, career stability, and inflation. The key insight? Net worth growth isn’t linear—it’s exponential when you prioritize assets over spending.
Conclusion
The answer to what % of income after taxes should be net worth isn’t a single number—it’s a conversation between your income, your expenses, and your tolerance for risk. A 25-year-old in San Francisco with $50,000 in student loans will need a different ratio than a 40-year-old in Omaha with a paid-off home. But the principle remains: your net worth should grow faster than your income, not just keep pace with it. The people who get this right aren’t the ones who earn the most—they’re the ones who spend the least relative to what they take home.
The next time you look at your bank account, don’t ask, "How much am I saving?" Ask, "What % of my after-tax income is actually working for me?" That’s the question that separates the financially secure from the perpetually stressed.
Comprehensive FAQs
#### Q: What’s the simplest way to calculate my net worth-to-income ratio?
Subtract your total liabilities (debt, loans, mortgages) from your total assets (cash, investments, home equity, retirement accounts). Then divide that net worth by your after-tax annual income. For example, if your net worth is $200,000 and your take-home pay is $80,000, your ratio is 2.5x. Most financial planners recommend tracking this annually.
####Q: Does this ratio work for everyone, or are there exceptions?
It’s a guideline, not a law. Exceptions include:
- High-debt professionals (e.g., doctors, lawyers) may start with a lower ratio but ramp up quickly after paying off loans.
- Early-career workers in volatile fields (e.g., tech, entertainment) might aim for 1x by 35 instead of 2x.
- Homeowners with mortgages—their net worth grows slowly until the home is paid off, skewing the ratio temporarily.
- Dual-income households may have higher ratios due to shared expenses and combined savings.
Q: If my ratio is below 1x, is it too late to fix?
Not necessarily. The critical factor is how fast you can improve it. If you’re under 35, aggressive debt repayment and high savings rates (30%+ of after-tax income) can catch up quickly. If you’re over 40, focus on increasing income (side hustles, promotions) and reducing fixed expenses (e.g., downsizing housing). The goal isn’t perfection—it’s closing the gap faster than inflation erodes your ratio.
####Q: How does inflation affect this ratio over time?
Inflation shrinks the purchasing power of both your income and net worth, but the impact varies. Historically, a net worth of 3x after-tax income in the 1980s covered ~20 years of expenses; today, it might cover only 10–12 years due to rising costs. To adjust:
- In high-inflation periods, aim for a higher ratio (e.g., 4x by 40 instead of 3x).
- In low-inflation periods, you can be more conservative (e.g., 2.5x by 35).
- Invest in assets that outpace inflation (stocks, real estate, TIPS bonds) to protect your ratio.
Q: What’s the biggest mistake people make when tracking this metric?
Overvaluing home equity as liquid net worth. Many people assume their home’s market value counts fully toward their ratio, but if you can’t sell it quickly (or afford to live elsewhere), that equity isn’t truly liquid. The mistake is treating your net worth ratio as a static number rather than a dynamic measure of financial flexibility. A better approach:
- Separate liquid net worth (cash, investments, retirement accounts) from illiquid assets (home, collectibles).
- Calculate a "stress-test ratio"—what % of your liquid net worth covers 1–2 years of expenses?
- Ignore paper gains (e.g., a stock portfolio up 20% on paper) until realized.
