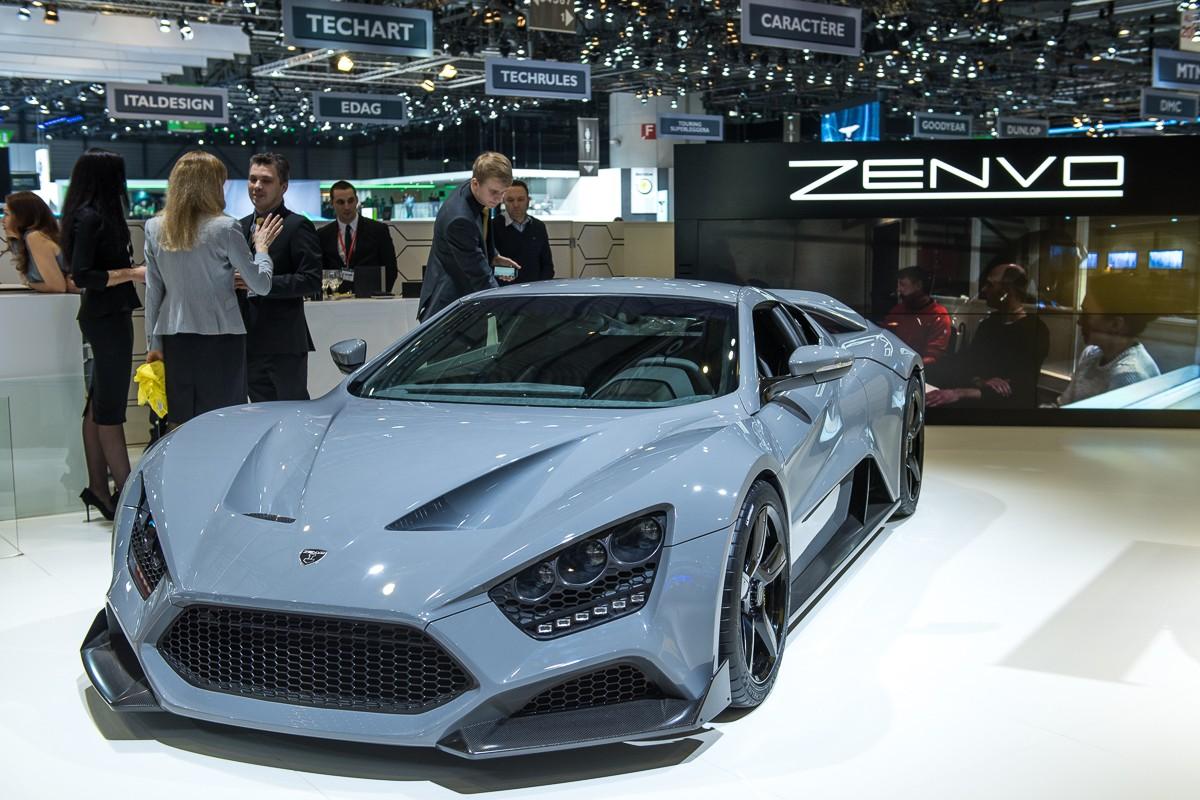
The Short Answers
- Zenvo’s net worth is estimated between £150–200 million, though exact figures are unpublished.
- The company’s revenue (£50–70M annually) comes from selling 50–70 hypercars at $1.5M–$2M each.
- Zenvo’s profit margins exceed 70%, far higher than mainstream automakers.
- Its valuation growth depends on electric hypercar success and potential acquisition interest.
- Unlike public automakers, Zenvo never discloses financials, relying on private equity and niche demand.
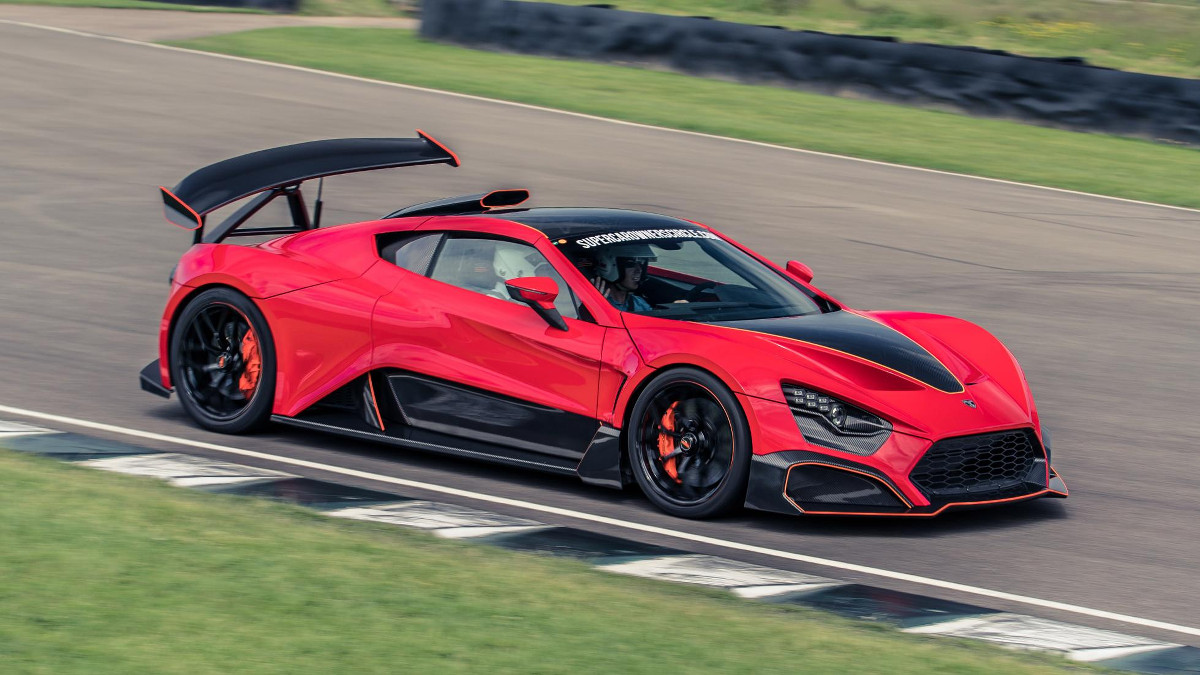
Deep Dive: The Full Picture
Zenvo’s financial narrative begins in 1998, when Gunnar Larson—a former McLaren engineer—founded the company in Denmark with a radical vision: build the world’s fastest production car using titanium monocoque construction. The first Zenvo, the ST1, debuted in 2009 with a 0–60 mph time of 2.8 seconds, a figure that still impresses today. But the real financial innovation wasn’t in speed; it was in pricing strategy. By positioning itself as the anti-Lamborghini—no factory tours, no overproduced models, just hand-built exclusivity—Zenvo carved out a niche where money wasn’t an object. This philosophy directly shapes its net worth: the brand’s value isn’t tied to scale but to perceived scarcity. The mechanics of Zenvo’s financial health revolve around three pillars: direct sales, strategic partnerships, and intellectual property. Direct sales account for the bulk of its revenue, with each car sold at a premium that rivals Bugatti or Koenigsegg. But Zenvo also licenses its titanium manufacturing techniques to aerospace firms, a secondary income stream that adds £10–15 million annually to its net worth. Then there’s the intellectual property—patents for its active aerodynamics and hybrid powertrains—which could fetch £50–100 million in a hypothetical sale. These layers make Zenvo’s valuation more than just a sum of car sales; it’s a portfolio of high-margin, low-volume assets.The Context You Need
Zenvo operates in a $100 billion global hypercar market, but its market share is microscopic—less than 0.1%. This isn’t a weakness; it’s a deliberate business model. The company’s customer base is a who’s who of ultra-high-net-worth individuals (UHNWIs), with buyers including celebrities, royalty, and tech billionaires. A single Zenvo sale can represent 10–20% of the company’s annual revenue, making each transaction a financial milestone. This concentration of wealth in a tiny customer pool ensures that Zenvo’s liquidity isn’t tied to mass appeal but to exclusivity-driven demand. The Danish context also plays a crucial role. Denmark’s government incentives for R&D—particularly in lightweight materials and electric propulsion—have kept Zenvo’s operating costs artificially low. Additionally, the country’s strong currency (DKK) and stable economic policies provide a buffer against the volatility seen in markets like the U.S. or China. These factors contribute to Zenvo’s profitability, allowing it to reinvest aggressively without the pressure to hit quarterly earnings targets. The result? A net worth that grows organically, rather than through forced expansion.The Mechanics
Zenvo’s revenue model is a study in high-margin efficiency. With fixed costs (manufacturing, R&D, labor) spread across 50–70 units per year, each car sold directly impacts the bottom line. Unlike Tesla or Mercedes, Zenvo doesn’t discount—its prices are set at a premium that reflects its engineering and exclusivity. This strategy ensures that gross margins remain consistently above 70%, a figure that would be envied by even the most profitable automakers. The operating margin, while not disclosed, is estimated to be around 30–40%, thanks to lean production and vertical integration (Zenvo controls much of its supply chain). The electric hypercar gambit is where Zenvo’s future valuation will be decided. The company has been quietly developing an EV prototype for years, with rumors suggesting a 2025–2026 launch. If successful, this could double its addressable market—electric hypercars are the next frontier for UHNWIs. Industry estimates suggest that if Zenvo enters this segment with a $2M–$3M price point, its enterprise value could surpass £300 million within five years. But this hinges on battery technology advancements and charging infrastructure—two variables that remain uncertain.Details That Change the Picture
Zenvo’s valuation isn’t static. It fluctuates based on three key variables: production capacity, electric vehicle progress, and acquisition interest. In 2021, reports emerged that Saudi Arabia’s NEOM project had shown interest in acquiring Zenvo’s titanium manufacturing tech, which could have instantly added £100M+ to its net worth. Nothing came of it, but the episode highlighted how strategic buyers view Zenvo—not just as a carmaker, but as a specialized engineering firm. Similarly, the 2023 launch of the Zenvo TSR—a car built for track-only use—demonstrated Zenvo’s ability to command even higher prices for ultra-limited editions. These moves suggest that Zenvo’s long-term valuation could outpace its current estimates, provided it maintains its no-compromise ethos. The hidden cost of Zenvo’s success? Opportunity. By refusing to scale, the company limits its market potential. While its net worth benefits from exclusivity, it also caps growth. For comparison, Koenigsegg—a direct competitor—has publicly traded shares, offering a window into its financials. Zenvo’s private status means its true worth is a moving target, subject to the whims of private equity valuations and founder equity decisions. This opacity is both a strength and a weakness: it protects the brand’s mystique but also makes external investment difficult."Zenvo isn’t just selling cars—it’s selling a philosophy. The numbers don’t matter as much as the story. And right now, that story is about being the last truly independent hypercar brand." — Automotive Analyst, Danish Financial Review (2023)
| Metric | Estimated Range |
|---|---|
| Annual Revenue | £50–70 million |
| Gross Margin | 70%+ |
| Enterprise Value (2024) | £150–200 million |
| Electric Hypercar Potential Value Add | £100–200 million (if successful) |
| Key Revenue Driver | Direct sales (90%+), tech licensing (10%) |

Conclusion
Zenvo’s net worth is a paradox: it’s both immeasurable and undeniable. The company’s refusal to disclose exact figures isn’t just about secrecy—it’s about preserving an image of invincibility. In a world where hypercar brands like Bugatti and McLaren are owned by conglomerates, Zenvo remains independently Danish, a last bastion of automotive purism. Its valuation isn’t just about cars; it’s about legacy, engineering, and the unshakable belief that speed and exclusivity will always have a market. The biggest question isn’t how much Zenvo is worth—it’s where it’s headed. If the electric hypercar succeeds, its net worth could skyrocket, potentially making it a target for private equity or sovereign wealth funds. But if it fails to innovate, it risks becoming a relic of the past, another name lost in the hypercar graveyard. For now, Zenvo’s true worth remains a closely guarded secret—one that only a handful of insiders, investors, and ultra-wealthy buyers will ever truly know.Comprehensive FAQs
Q: Is Zenvo profitable?
Yes. With gross margins exceeding 70% and operating margins estimated at 30–40%, Zenvo is highly profitable—though it reinvests heavily into R&D and production capacity. Its profitability isn’t measured in volume but in high-margin, low-volume sales.
Q: Has Zenvo ever been acquired?
No. Despite rumored interest from Saudi Arabia’s NEOM and other strategic buyers, Zenvo has remained independently owned. Founder Gunnar Larson has stated that preserving independence is a non-negotiable priority, even if it means limiting growth opportunities.
Q: How does Zenvo’s valuation compare to Koenigsegg?
Zenvo’s enterprise value (£150–200M) is significantly lower than Koenigsegg’s publicly traded valuation (£500M+). However, Zenvo’s profit margins and exclusivity make its per-unit profitability far higher. The key difference? Koenigsegg is a growth play; Zenvo is a lifestyle investment.
Q: Could Zenvo’s electric hypercar change its net worth?
Absolutely. If Zenvo’s EV prototype—rumored for 2025–2026—gains traction, its valuation could double or triple. The electric hypercar segment is untapped, and Zenvo’s titanium expertise could give it a first-mover advantage. However, battery tech and charging infrastructure remain wild cards.
Q: Why doesn’t Zenvo disclose financials?
Zenvo operates as a private company, meaning it’s not legally required to publish financials. Additionally, transparency could undermine its exclusivity. By keeping its net worth and production numbers secret, Zenvo maintains an aura of mystery—a strategy that drives demand among its ultra-niche customer base.
Q: What’s the biggest threat to Zenvo’s net worth?
The biggest risk isn’t competition—it’s scaling too fast. If Zenvo compromises on quality to increase production, it could dilute its brand. Additionally, economic downturns could reduce UHNWI spending on hypercars. For now, though, Zenvo’s business model is bulletproof—as long as it stays true to its roots.
