
The Short Answers
- vivobarefoot’s net worth is estimated by industry analysts to fall between £50–100 million, though exact figures are undisclosed.
- The brand operates privately, with no public financial disclosures or IPO plans.
- Revenue growth is tied to its minimalist footwear philosophy, which limits mass-market expansion but ensures high-margin sales.
- Partnerships (e.g., with physiotherapists, athletes) and retail presence (e.g., Selfridges, REI) bolster its perceived value beyond pure sales data.
- Exit strategies—like a potential acquisition—could significantly alter its valuation, but no such rumors have been substantiated.
Deep Dive: The Full Picture
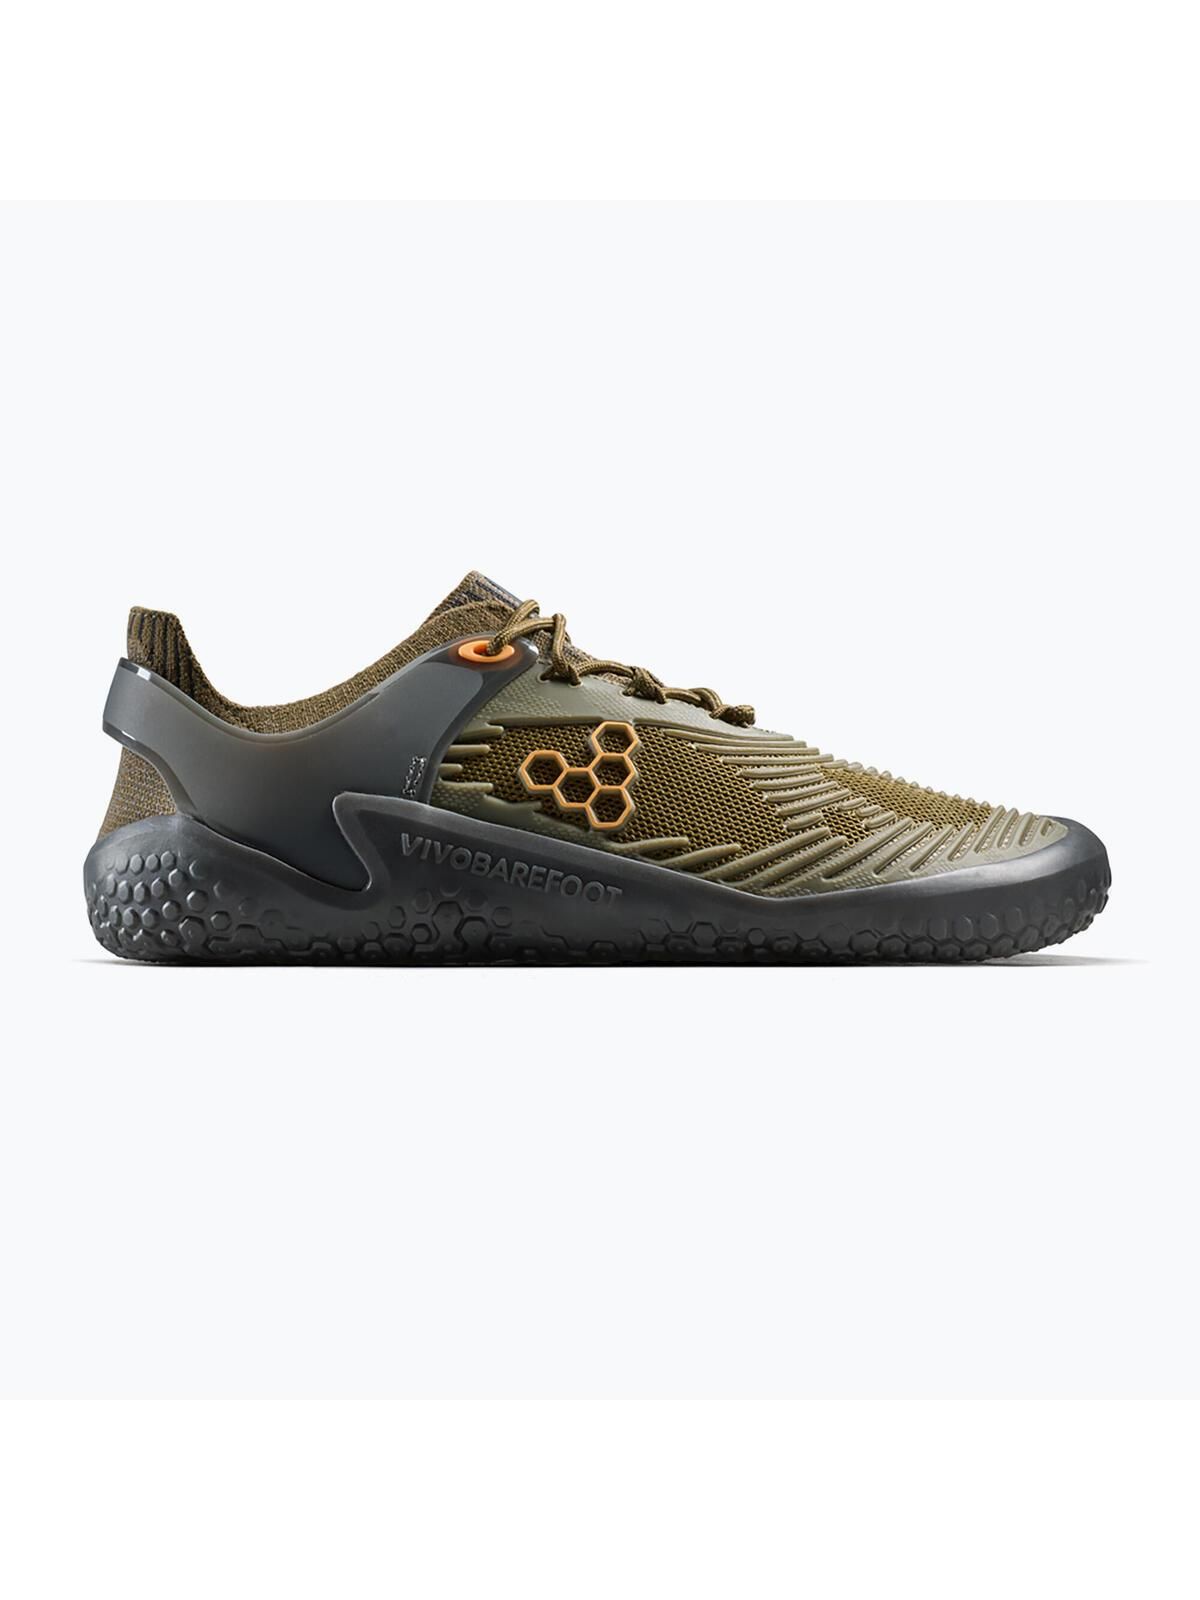
The vivobarefoot net worth isn’t a static number; it’s a reflection of its business model’s duality. On one hand, the brand thrives as a lifestyle niche player, catering to runners, yoga enthusiasts, and those seeking "natural footwear." On the other, its premium pricing and limited distribution keep it from achieving the scale of giants like Allbirds or Hoka. The tension between exclusivity and growth potential defines its financial trajectory. Unlike direct competitors that rely on mass production, vivobarefoot’s valuation is tied to its ability to maintain authenticity—something investors in the wellness sector increasingly prize. What sets vivobarefoot apart is its philosophy-first approach. The brand’s shoes are designed to encourage "barefoot movement," a concept backed by biomechanics research. This isn’t just marketing; it’s a product differentiator that justifies higher price points. For example, its Primus Lite model retails for upwards of £120, yet customers defend the cost as an investment in foot health. Such positioning allows the brand to command premium valuations in private equity circles, where "purpose-driven" businesses often fetch higher multiples than commodity footwear brands.The Context You Need
The minimalist footwear market is a $1.2 billion segment within the broader athletic wear industry, growing at 8% annually. Vivobarefoot occupies a unique position: it’s neither a mainstream brand nor a boutique label. Its net worth is inflated by its cult following—athletes like Mo Farah have been spotted wearing its shoes, and physiotherapists recommend them for rehabilitation. Yet, this same niche appeal limits its addressable market. Unlike Nike, which can pivot into apparel or tech, vivobarefoot’s valuation is constrained by its singular focus on footwear. The brand’s financial health also hinges on supply chain resilience. Unlike fast-fashion competitors, vivobarefoot sources materials ethically (e.g., vegan leather, recycled rubber) and manufactures in Portugal and the UK. These choices add to production costs but align with consumer demand for sustainability—a factor that indirectly boosts its perceived worth in ESG-focused investment circles.The Mechanics
Vivobarefoot’s valuation mechanics revolve around three pillars: revenue streams, cost structure, and brand equity. Revenue comes from direct-to-consumer sales (via its website) and wholesale partnerships (e.g., running stores, luxury retailers). Costs are high due to thin-margin retail partnerships and R&D investment in shoe design. Yet, its gross margins reportedly hover around 50–60%, far above industry averages. This efficiency is critical for a privately held brand with no public scrutiny. The brand’s exit strategy—if it ever pursued one—would likely hinge on its intellectual property. Patents on its "barefoot engineering" technology and its proprietary sole designs could attract acquirers. However, the lack of a clear succession plan (founders Darren and Emma Cross remain deeply involved) keeps speculation about a sale or IPO speculative. For now, its net worth is tied to organic growth: expanding product lines (e.g., sandals, children’s shoes) and international markets (particularly the US and Europe).Details That Change the Picture
The vivobarefoot net worth isn’t just about shoes—it’s about community and credibility. The brand’s ambassador program, which includes physiotherapists and elite runners, acts as free marketing. These endorsements aren’t paid; they’re built on genuine advocacy, which enhances the brand’s perceived value without traditional ad spend. This grassroots approach reduces customer acquisition costs, a key factor in its financial health. Another wildcard is retailer power. Vivobarefoot’s presence in high-end stores like Selfridges and Net-a-Porter signals luxury positioning, but it also means wholesale margins are negotiated downward. The brand must balance prestige with profitability—a delicate act that influences its valuation in private markets. Analysts suggest that if vivobarefoot were to consolidate distribution (e.g., prioritize DTC over wholesale), its margins—and thus its net worth—could climb sharply."Vivobarefoot isn’t just selling shoes; it’s selling a movement. That’s why its valuation isn’t about units sold—it’s about the loyalty those units generate." — Footwear industry analyst, 2023
| Factor | Impact on Valuation |
|---|---|
| Niche Market Loyalty | High customer retention reduces churn, boosting long-term revenue stability. |
| Premium Pricing | Margins of 50–60% justify higher multiples in private equity assessments. |
| Supply Chain Costs | Ethical sourcing adds 15–20% to COGS, limiting scalability but aligning with ESG trends. |
| Retailer Dependence | Wholesale partnerships dilute margins but expand reach; DTC focus could improve valuation. |
| Intellectual Property | Patents on sole designs are a potential acquisition target, adding hidden value. |

Conclusion
The vivobarefoot net worth remains an enigma, but the clues are there. It’s a brand that rejects conventional growth metrics in favor of philosophy-driven sales. Its valuation isn’t about dominating shelves; it’s about dominating minds—convincing customers that their feet deserve better. For investors, the risk is clear: limited scalability. For consumers, the reward is a product that aligns with their values. The tension between these two realities is what makes vivobarefoot’s financial story so fascinating. Will it stay a cult brand or evolve into a mainstream player? The answer will define its net worth for years to come. One thing is certain: vivobarefoot’s valuation isn’t just about numbers. It’s about proving that profit and purpose can coexist—a rare feat in an industry often driven by quarterly earnings. Whether that experiment succeeds financially remains to be seen, but its impact on the footwear world is already undeniable.Comprehensive FAQs
Q: Is vivobarefoot profitable?
Yes, but exact figures are undisclosed. Industry estimates suggest gross margins of 50–60%, which indicate profitability, though net profitability depends on retail partnerships and marketing spend.
Q: Has vivobarefoot ever been acquired?
No, the brand remains independently owned. Founders Darren and Emma Cross have no public plans to sell, though private equity interest in niche footwear brands has grown in recent years.
Q: How does vivobarefoot’s valuation compare to Allbirds?
Allbirds, which went public in 2021, had a pre-IPO valuation of $1.7 billion. Vivobarefoot, by contrast, is privately held and estimated at £50–100 million—a fraction of Allbirds’ scale but with a more loyal, high-margin customer base.
Q: Does vivobarefoot disclose financials?
No. As a private company, it does not publish annual reports or revenue figures. Any estimates come from third-party analysis of retail trends and industry benchmarks.
Q: Could vivobarefoot go public?
Speculation exists, but no concrete plans have emerged. A public listing would require scaling revenue—something the brand’s niche focus may limit. If it pursued an IPO, its valuation would likely hinge on proving mass-market appeal.
