The Short Answers
- Visage Imaging’s net worth is estimated to be in the hundreds of millions, though exact figures remain private.
- Its valuation is driven by AI-powered medical imaging software, not hardware sales.
- Major revenue streams include hospital subscriptions, enterprise licensing, and strategic partnerships with tech giants.
- Recent funding rounds (pre-2020) suggest venture capital interest in its AI-driven diagnostics.
- Competitors like Siemens Healthineers and Philips dwarf Visage in scale, but its niche focus keeps it relevant.
- The company’s worth is tied to regulatory approvals—delays or rejections could impact its growth trajectory.
Deep Dive: The Full Picture
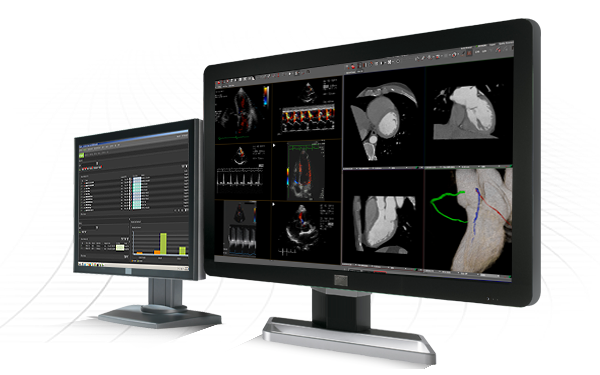
Visage Imaging’s financial standing isn’t just about balance sheets; it’s about influence. The company’s software doesn’t just display images—it augments clinician decision-making by flagging anomalies, quantifying risks, and even predicting outcomes. That functional edge translates into sticky contracts with hospitals, where downtime isn’t just costly—it’s potentially lethal. The result? A business model that relies less on one-time sales and more on recurring revenue, a gold standard in SaaS (Software as a Service) economics. Yet unlike consumer tech firms, Visage’s customer base isn’t price-sensitive; it’s risk-averse. Hospitals don’t shop for the cheapest imaging tool; they invest in systems that can mitigate lawsuits, improve survival rates, and justify premium pricing. The catch? Scalability. Visage operates in a fragmented market where adoption depends on clinician buy-in, IT infrastructure, and—critically—proof of ROI. A single large contract (e.g., with a Mayo Clinic or Johns Hopkins) can swing its annual revenue, making its net worth a moving target. Analysts point to two wild cards: AI advancements (which could render its current tools obsolete) and consolidation (if a bigger player like IBM or Google acquires it). For now, though, Visage’s worth is less about market cap and more about operational leverage—the ability to charge premium rates while keeping customer churn low.The Context You Need
The medical imaging sector is a $30 billion+ industry, but Visage doesn’t compete on volume—it competes on specialization. While giants like GE Healthcare sell scanners, Visage sells software layers that turn raw scans into actionable insights. This niche strategy has two consequences: higher margins (since development costs are spread across fewer customers) and lower visibility (since it’s not a household brand). The company’s net worth reflects this duality: it’s not a unicorn by traditional standards, but its customer lifetime value is astronomical in an industry where a single misdiagnosis can cost millions. What’s often overlooked is Visage’s indirect valuation drivers. For example, its partnerships with NVIDIA (for GPU-accelerated AI) and Microsoft Azure (for cloud hosting) add intangible value. These alliances don’t appear on balance sheets but reduce risk for investors. Similarly, its FDA clearances for specific applications (e.g., cardiac imaging) act as growth catalysts, allowing it to charge more for certified versions of its tools. The company’s worth isn’t just a number—it’s a portfolio of trust markers that hospitals weigh before signing contracts.The Mechanics
Visage’s revenue model is subscription-first, with enterprise licensing as a secondary stream. Most hospitals pay annual fees tied to usage, not per-image analysis—a model that aligns incentives (the more doctors use the tool, the more Visage earns). This contrasts with traditional imaging firms, which often sell hardware upfront. The shift to software-as-a-service has been a boon, but it also means Visage’s net worth is sensitive to customer concentration risk. If a single large client (like a regional health system) drops its contract, the revenue hit can be disproportionate. Behind the scenes, Visage’s R&D budget is a black box. Industry estimates suggest it reinvests 30–40% of revenue into AI training, regulatory compliance, and new modules. That’s a high burn rate, but it’s necessary in a field where one breakthrough (e.g., a new algorithm for early cancer detection) can justify a valuation spike. The company’s worth isn’t just about past performance—it’s about future monetization potential, a gamble that venture capitalists have repeatedly backed.Details That Change the Picture
Visage’s financial health isn’t static. Two factors loom larger than others: regulatory hurdles and competitive encroachment. The FDA’s approval process for medical AI is lengthy and unpredictable, meaning delays can stall revenue growth. Meanwhile, big tech (Google, Amazon) and traditional med-tech (Siemens, Philips) are aggressively entering the AI imaging space, forcing Visage to either innovate faster or find a niche it can defend. These dynamics mean its net worth isn’t just a reflection of today’s contracts—it’s a hedge against tomorrow’s disruptions. Then there’s the hidden leverage: Visage’s software often integrates with existing hospital IT stacks, creating lock-in effects. A radiology department that adopts Visage for lung cancer analysis might hesitate to switch vendors, even if a cheaper alternative emerges. This network effect is invisible in financial statements but elevates its worth in practice. The company’s ability to monetize stickiness—not just sell software, but own the workflow—is what separates it from competitors."Visage doesn’t sell pixels; it sells confidence. In healthcare, that’s a premium product." — Radiology IT consultant, 2023
| Factor | Impact on Valuation |
|---|---|
| AI Accuracy Improvements | Could justify higher subscription tiers or new premium modules. |
| FDA Approvals | Each clearance unlocks new revenue streams (e.g., cardiac vs. oncology). |
| Competitor Entry | May force price wars or feature races, pressuring margins. |
| Cloud Migration Trends | Shifts from on-premise licenses to SaaS subscriptions, altering revenue mix. |

Conclusion
Visage Imaging’s net worth isn’t a fixed number—it’s a living equation where code meets capital. The company’s strength lies in its invisibility: most patients never interact with its software, yet its algorithms influence their care. That paradox—high impact, low public profile—makes its valuation a puzzle. For investors, the appeal is clear: recurring revenue, high margins, and life-saving utility. For hospitals, the risk is equally clear: dependency on a single vendor. The balance between these forces will determine whether Visage remains a quiet billion-dollar player or gets absorbed into a larger med-tech empire. One thing is certain: the company’s worth isn’t just about dollars. It’s about trust. In an industry where errors can be fatal, Visage’s software isn’t just a tool—it’s a guardrail. And in healthcare, guardrails are worth far more than their weight in gold.Comprehensive FAQs
Q: Is Visage Imaging publicly traded?
A: No. Visage remains a private company, meaning its financials aren’t disclosed to the public. Valuation estimates come from industry reports, funding rounds, and insider insights—not SEC filings.
Q: How does Visage Imaging make money?
A: Primarily through subscription-based licenses (annual fees per hospital or department) and enterprise contracts for specialized imaging workflows. Unlike hardware firms, its revenue is recurring, not tied to one-time sales.
Q: What’s the biggest threat to Visage’s valuation?
A: Regulatory delays (FDA approvals can stall growth) and competition from big tech (Google, Amazon) entering AI imaging. A single misstep in either area could erode its market position.
Q: Has Visage Imaging been acquired?
A: Not yet. While it has strategic partnerships (e.g., NVIDIA, Microsoft), there’s been no confirmed acquisition. Rumors of interest from private equity have circulated, but no deal has materialized.
Q: How does Visage Imaging’s valuation compare to competitors?
A: It’s a niche player compared to giants like Siemens Healthineers (public, ~$20B+ market cap) or Philips (~$25B). Visage’s worth is likely orders of magnitude smaller, but its margins and customer loyalty are higher.
Q: Does Visage Imaging profit from AI advancements?
A: Yes. Its AI-driven diagnostics (e.g., tumor detection, stroke prediction) allow it to charge premium rates for certified modules. Each algorithm improvement can justify higher subscription tiers or unlock new contracts.
Q: What’s the most valuable asset in Visage’s portfolio?
A: Its FDA-cleared applications. Each approval acts as a growth catalyst, enabling the company to target specific medical specialties (e.g., cardiology, oncology) with tailored solutions—and charge accordingly.
Q: Could Visage Imaging’s worth double in the next 5 years?
A: It’s possible, but not guaranteed. Growth depends on AI accuracy gains, expanded FDA clearances, and resistance to big-tech competition. A single breakthrough (e.g., a first-to-market AI for early Alzheimer’s detection) could supercharge its valuation.
