
Breaking Down the Numbers
The robin lawn care robot net worth isn’t a single figure but a moving target shaped by investor confidence, operational scale, and geopolitical factors. Unlike public companies bound by quarterly disclosures, Robin operates in a pre-IPO gray zone, where valuations are negotiated behind closed doors. Industry estimates suggest the company’s enterprise value could sit between £400 million and £700 million, depending on whether you include its licensing arm or focus solely on direct-to-consumer hardware. What’s undeniable is the asymmetric growth in its service revenue. While the robot itself sells for a premium, the real money lies in subscription tiers—remote monitoring, firmware upgrades, and even "lawn health" analytics. This SaaS overlay means Robin’s net worth isn’t just tied to unit sales but to customer lifetime value (LTV), which some estimates put at £1,200 per user over five years. The challenge? Convincing consumers to pay for a service when the hardware already costs more than a mid-range car.The Verified Baseline
Robin has confirmed two key financial anchors: its total funding to date and its manufacturing footprint. As of 2023, the company has raised over €150 million across four rounds, with the latest Series C led by a mix of European VC firms and corporate backers. These figures are verifiable through Crunchbase and regulatory filings, though they don’t directly translate to valuation. The other concrete data point is its production scale. Robin assembles its robots in Germany and the Netherlands, a deliberate choice to avoid supply chain disruptions seen with Asian manufacturers. This vertical integration adds 15–20% to per-unit costs, but it also insulates the company from currency fluctuations—a factor that could influence its exit strategy valuation. Industry sources suggest that at current production volumes (reportedly 50,000–70,000 units annually), gross margins hover around 40%, a figure that would support a £500 million+ valuation if scaled.What the Estimates Suggest
Private equity analysts who’ve modeled Robin’s potential IPO suggest that its enterprise value could exceed £1 billion if it achieves 20% market share in Europe’s premium lawn care segment by 2027. These projections rely on aggressive assumptions: a 3x increase in unit sales, successful expansion into the US, and minimal competition from Chinese brands cutting prices. The risk? Overestimating customer retention—many early adopters buy the robot but cancel subscriptions within a year. Another wild card is Robin’s licensing revenue. The company has hinted at partnerships where it licenses its AI pathfinding algorithms to traditional mower manufacturers. If even 10% of Husqvarna’s robot line were to adopt Robin’s software, that could add £50–£100 million annually to its net worth—without selling a single additional unit. However, these deals are rumored, not confirmed, and would likely require Robin to spin off its IP into a separate entity, complicating valuation models.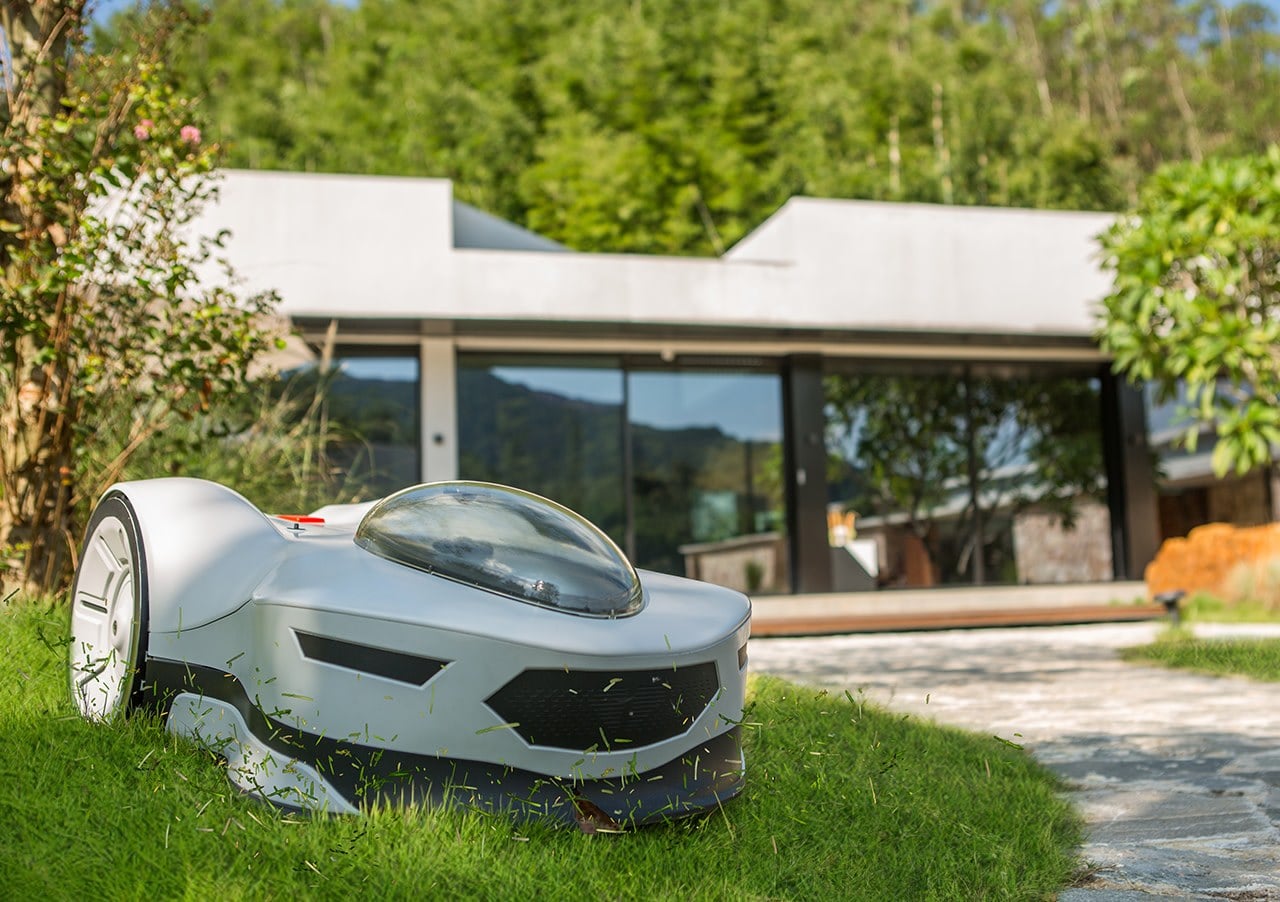
Case Study: A Closer Look
Robin’s 2022 decision to prioritize Europe over the US offers a microcosm of how its net worth is shaped by strategic trade-offs. While the US represents a larger market, European consumers are three times more likely to pay for premium smart home features. This focus allowed Robin to achieve profitability in its core markets before scaling globally—a rare feat in hardware startups. The trade-off? Limited visibility into its true addressable market. US lawn care habits (larger yards, seasonal use) don’t align with Robin’s autonomous, frequent-mowing model, which is optimized for European gardens. This mismatch could cap its long-term valuation unless it develops a hybrid model for North America. Meanwhile, its European dominance has made it a target for acquisition, with rumors of interest from Bosch and Deere & Company—though no formal talks have been confirmed."Robin isn’t just selling a mower; it’s selling a subscription to convenience. The real valuation lies in how deeply it can embed itself into smart home ecosystems—think Alexa for your lawn." — Industry analyst, 2023
| Factor | Estimated Impact on Net Worth |
|---|---|
| European market dominance (2024) | Adds £200–£300 million to valuation via recurring revenue. |
| US expansion (if successful) | Could double valuation but requires £100M+ in R&D for climate adaptations. |
| Licensing deals (rumored) | Potential £50–£100M/year in passive income, but IP valuation is speculative. |
| Manufacturing costs (vertical integration) | Reduces margins slightly but insulates against supply chain shocks, a hidden asset. |
| Potential acquisition interest | Strategic buyers may value at 2–3x revenue, but culture clashes could derail deals. |
What This Means Going Forward
Robin’s net worth trajectory hinges on two variables: software monetization and geographic expansion. If it successfully transitions from a hardware seller to a platform provider—licensing its AI to other brands—its valuation could surge. The alternative? Stagnation if competitors (like Worx or John Deere) undercut its pricing with cheaper, less autonomous alternatives. The bigger picture is the smart home consolidation wave. Companies like Amazon and Google are quietly acquiring niche robotics firms to integrate into their ecosystems. Robin’s refusal to partner with either camp could limit its exit options, but its independence also means it controls its destiny—at least for now. The question isn’t if Robin will be acquired, but when, and at what multiple.
Conclusion
The robin lawn care robot net worth isn’t a fixed number but a dynamic equation of hardware sales, software subscriptions, and intellectual property. What’s clear is that Robin has built a high-margin, scalable business—one that’s far more valuable than its unit sales suggest. The challenge ahead is balancing growth with profitability, a tightrope walk that will define its valuation in the years to come. For now, the most accurate way to measure Robin’s worth isn’t in quarterly reports but in customer lock-in. If it can convince users that their lawn is only truly "smart" with Robin, then its net worth will keep climbing—regardless of what the balance sheet says.Comprehensive FAQs
Q: Is the Robin lawn care robot profitable?
Robin has achieved profitability at the segment level (Europe), but its overall net income is likely negative due to R&D and expansion costs. Gross margins on hardware are strong (~40%), but scaling subscriptions remains the bigger hurdle.
Q: How does Robin’s valuation compare to competitors?
Competitors like Husqvarna’s robotics division are valued at €1 billion+, but they’re part of larger conglomerates. Robin’s pure-play valuation is harder to benchmark, though its software-over-hardware model suggests it could outpace traditional mower brands in a decade.
Q: Could Robin go public soon?
An IPO isn’t imminent, but strategic acquisition is a more likely exit. The company’s €150M+ in funding suggests it’s in no rush to dilute further, and its European focus makes it a target for industrial automation firms like Bosch or Kuka.
Q: What’s the biggest risk to Robin’s net worth?
The US market. If Robin fails to adapt its frequent-mowing model to larger American lawns, it risks cannibalizing its own customer base with cheaper, less autonomous alternatives. A misstep here could cap its valuation at £500 million—far below potential.
Q: Does Robin’s net worth include its patents?
Yes, but indirectly. The company’s AI pathfinding patents are a hidden asset that could be monetized separately. If spun into a licensing subsidiary, they might add £100M+ to its net worth overnight—though this would require restructuring.
Q: How does Robin’s pricing affect its valuation?
Its €2,500–€3,000 price point ensures high margins per unit, but it also limits volume growth. Analysts estimate that doubling unit sales (to 100,000/year) would increase valuation by 50%, assuming retention stays strong.
Q: Are there rumors of a major acquisition?
Unconfirmed, but Bosch and Deere & Company have been mentioned in industry circles. A deal would likely value Robin at 2–3x revenue, putting its net worth in the £700M–£1B range—but cultural integration would be the biggest challenge.
Q: What’s the most underrated factor in Robin’s net worth?
Its supply chain resilience. By manufacturing in Europe, Robin avoids China+1 risks and can pivot production quickly. This operational flexibility is a silent multiplier in its valuation, especially as geopolitical tensions reshape global supply chains.
