
The Short Answers
- In the U.S., the average net worth per adult is about $130,000, but the median is $67,700—half the population has less.
- Globally, the average net worth varies wildly: $6,600 in India vs. $450,000 in Switzerland (per Credit Suisse data).
- Age matters—Gen Xers (44–59) hold the most wealth, while Millennials (28–43) lag due to student debt and housing costs.
- Homeownership is the single biggest wealth driver: Owners have 40x more net worth than renters on average.
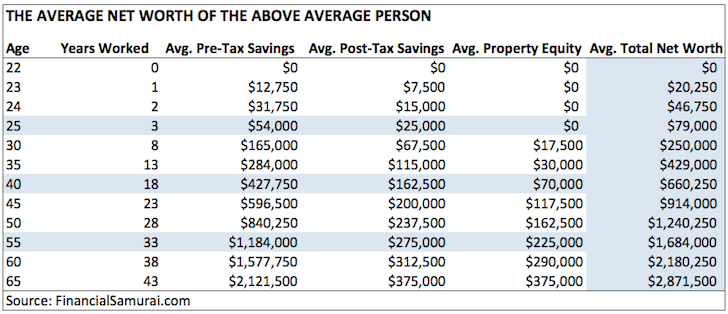
Deep Dive: The Full Picture
Net worth isn’t just a number—it’s a snapshot of economic opportunity. The Federal Reserve’s 2022 Survey of Consumer Finances shows that the top 10% of U.S. households control 70% of all wealth, while the bottom 50% hold just 2.6%. This isn’t just inequality; it’s structural. Wealth compounds over generations. A family that inherits a home or savings account starts ahead, while those without such headwinds face an uphill climb.
The global picture is just as uneven. Credit Suisse’s Global Wealth Report 2023 estimates that half the world’s adults have net worth below $10,000. In countries like Nigeria or Indonesia, the average is under $2,000, reflecting limited access to banking, property, or stable investments. Even in wealthy nations, regional divides exist: a Londoner’s average net worth (£250,000) dwarfs that of someone in Manchester (£120,000), thanks to housing markets and job opportunities.
#### The Context You Need
Understanding "how much is the average person's net worth" requires distinguishing between mean and median. The mean (average) is inflated by billionaires—Warren Buffett’s $120 billion skews U.S. figures upward. The median, however, tells a truer story: half the population has less than $67,700. This gap explains why discussions about wealth often focus on median rather than average. Demographics play a crucial role. Boomers (59–77) hold the most wealth, thanks to decades of home appreciation and stock market growth. Gen X follows, while Millennials (now 28–43) are still recovering from the 2008 crash and student debt. The Federal Reserve’s data shows Millennials’ median net worth at $92,300—but that includes those with inherited wealth. For the typical Millennial without family support, the number is closer to $25,000. ####The Mechanics
Net worth is calculated simply: assets minus liabilities. Assets include cash, investments, retirement accounts, and home equity. Liabilities are debts—mortgages, student loans, credit cards. A 30-year-old with $50,000 in student debt and $10,000 in savings has a negative net worth. A 50-year-old with a $400,000 home (no mortgage) and $150,000 in investments has $550,000. The biggest wealth driver? Homeownership. The Federal Reserve’s data shows that homeowners have 40 times the net worth of renters. This isn’t just about property values—it’s about forced savings. Renters pay landlords; owners build equity. Policies like first-time buyer grants or rent control directly impact who accumulates wealth.Details That Change the Picture
The numbers shift dramatically by country. In Nordic nations, high taxes fund strong social safety nets, but average net worth still reflects lower inequality. Sweden’s average is €200,000, but the median is €80,000—showing that even in wealthy societies, wealth isn’t evenly distributed. Meanwhile, in Latin America, informal economies and limited banking access keep averages low. Brazil’s average net worth is $15,000, but the top 10% hold 80% of all wealth.
Education also matters. A Harvard Business School study found that college graduates earn 84% more over their lifetime than high school graduates. But debt cancels out some gains: the average 2023 graduate leaves school with $37,000 in student loans, which can take decades to pay off. This explains why young professionals with degrees sometimes have lower net worth than their peers without them—at least in the short term.
"Wealth isn’t just about money. It’s about access—access to education, housing, and opportunities that let you build assets." — Raghuram Rajan, Former Governor of the Reserve Bank of India
| Demographic | Average Net Worth (U.S.) |
|---|---|
| White households | $188,200 |
| Black households | $24,100 |
| Hispanic households | $36,400 |
| Homeowners (all races) | $319,200 |
| Renters (all races) | $8,300 |

Conclusion
The question "how much is the average person's net worth" has no single answer because wealth is not distributed evenly. It’s shaped by race, age, geography, and luck. Policies that expand homeownership, reduce student debt, or provide financial literacy could shift these numbers—but only if structural barriers are addressed. For now, the data shows one clear truth: the average masks the extreme disparities beneath it.
What these figures don’t show is aspiration. Many people with modest net worth today will see it grow with time, especially if they invest early or benefit from market upswings. But for those left behind—renters, young workers, and marginalized groups—the system is rigged against them. The real question isn’t just "how much is the average person's net worth?" but how we can make that average higher for everyone.
Comprehensive FAQs
#### Q: What’s the difference between average and median net worth?
The average (mean) is calculated by adding up all net worth values and dividing by the number of people. This gets skewed by billionaires. The median is the middle value—half the population has less, half has more. For example, the U.S. average is $130,000, but the median is $67,700 because a few ultra-wealthy individuals inflate the average.
####Q: How does homeownership affect net worth?
Homeownership is the single biggest wealth driver. The Federal Reserve’s data shows that homeowners have 40 times the net worth of renters. This is because mortgages act like forced savings—each payment builds equity. Renters, meanwhile, pay landlords without building assets. Policies like down payment assistance or rent control directly impact who accumulates wealth over time.
####Q: Why do Millennials have lower net worth than Gen X?
Millennials (now 28–43) entered the workforce during the 2008 financial crisis, which wiped out jobs and retirement savings. They also face higher student debt—the average 2023 graduate leaves school with $37,000 in loans. Gen X (44–59) benefited from rising home prices and stock market growth in the 1990s and 2000s. Additionally, Millennials entered a high-cost housing market, making homeownership harder to achieve early.
####Q: How does race impact net worth in the U.S.?
Racial wealth gaps are staggering. White households have a median net worth of $188,200, while Black households have just $24,100. Hispanic households sit at $36,400. This disparity stems from historical discrimination (redlining, predatory lending) and systemic barriers (education access, wage gaps). Even when controlling for income, Black and Hispanic families accumulate wealth at a slower rate due to these factors.
####Q: Can negative net worth be a good thing?
Negative net worth isn’t inherently bad—it’s common for young adults, students, or those with high debt. For example, a 25-year-old with $50,000 in student loans and $5,000 in savings has negative net worth. But if they’re building a career, investing, or saving aggressively, this is a temporary phase. The key is trajectory: someone with negative net worth today could outearn and outsave someone with modest assets if they increase income or reduce debt over time.
####Q: How do global averages compare to the U.S.?
Globally, the average net worth varies wildly. In Switzerland, it’s $450,000; in India, it’s $6,600. Credit Suisse’s 2023 Global Wealth Report found that half the world’s adults have less than $10,000. The U.S. ranks above the global median, but its wealth inequality is worse than in many European nations. For example, Germany’s average is €120,000, but its median is €40,000—showing that even in wealthy countries, disparities exist.
