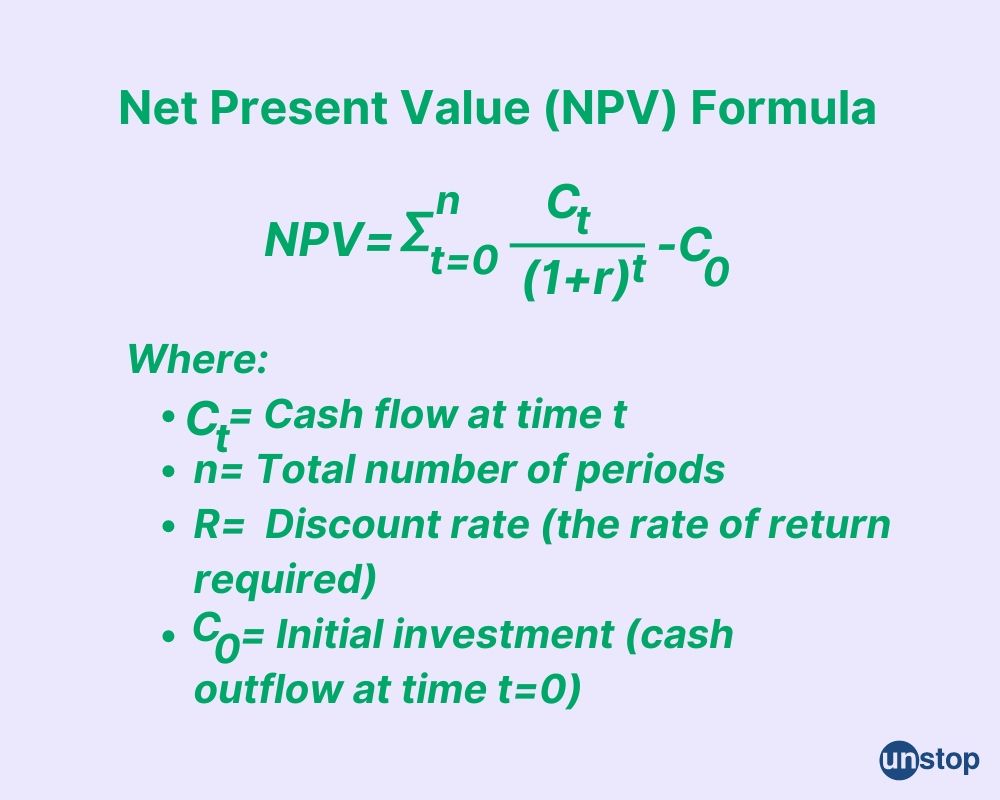
The Short Answers
- NPV valuation for your business depends on projected free cash flows, your industry’s discount rate (typically 10-20%), and terminal value assumptions.
- Forbes-backed valuations often use a weighted average cost of capital (WACC) between 12-18% for mid-market firms, higher for early-stage startups.
- Terminal value—your business’s worth beyond the 10-year projection—can swing NPV by 50% or more if miscalculated.
- Even with identical revenue, two businesses in the same sector may have NPVs differing by 30% due to risk profiles and growth trajectories.

Deep Dive: The Full Picture
NPV isn’t just a financial formula; it’s a narrative about your business’s future. When Forbes analysts evaluate a company, they don’t start with balance sheets—they dissect the story behind the numbers. A biotech firm with a single FDA-approved drug might have a higher NPV than a diversified conglomerate if the drug’s patent life and pipeline are robust. The key variable? The discount rate. A 15% WACC assumes higher risk than a 10% rate, and that 5% difference compounds over decades. That’s why private equity firms push for lower rates during due diligence—they’re not being generous; they’re recasting your business’s risk profile. The real test of NPV comes when you compare it to other valuation methods. A multiple-of-EBITDA approach might suggest one figure, while DCF (discounted cash flow) delivers another. Forbes often highlights cases where the two diverge by 20-30%. The discrepancy isn’t a flaw—it’s a signal. If DCF yields a lower NPV, it may indicate overvaluation based on current market conditions. Conversely, if NPV exceeds multiples, it could mean your business has hidden growth potential that traditional metrics miss.The Context You Need
Industry benchmarks matter, but they’re a starting point, not a rulebook. A software company in Austin might see NPVs in the $50M-$150M range based on SaaS multiples, but if its customer concentration is extreme (e.g., 40% revenue from one client), the discount rate spikes, and NPV drops. Forbes data shows that customer diversity alone can adjust NPV by 15-25%. Similarly, a family-owned distributor with $20M in revenue might have an NPV of $12M-$18M, but if it lacks a succession plan, lenders apply a 20%+ risk premium, cutting the figure by nearly half. The timing of your valuation also distorts NPV. Selling during an economic downturn doesn’t just lower the top-line price—it forces buyers to assume higher discount rates. A 2022 Forbes study of middle-market exits found that businesses sold in Q4 often saw NPVs 10-15% lower than those sold in Q1, even with identical financials. That’s because investors bake in recessionary buffers. The lesson? NPV isn’t a fixed number; it’s a moving target influenced by macroeconomic sentiment.The Mechanics
At its core, NPV boils down to three components: 1. Projected Free Cash Flows (FCF): Your business’s ability to generate cash after capital expenditures, taxes, and working capital changes. Forbes analysts often stress-test these projections with stress scenarios (e.g., a 20% revenue decline). 2. Discount Rate (WACC): The hurdle rate that accounts for the cost of debt, equity, and sector-specific risk. A tech startup might use a 18-22% WACC, while a utility company could use 8-12%. 3. Terminal Value: The value of your business beyond the projection period, typically calculated using a perpetuity growth model (e.g., 2-4% growth rate). This is where most valuations go wrong—assuming terminal value is "infinite" without justification. Forbes frequently cites the case of a $30M-revenue logistics firm where the terminal value alone accounted for $22M of the $35M NPV. The owner’s mistake? Using a 5% growth rate for terminal value when the industry average was 2%. That 3% difference shaved $5M off the total. The takeaway: Terminal value isn’t an afterthought; it’s the linchpin.Details That Change the Picture
The NPV you calculate today may not be the NPV a buyer accepts. That’s because control premiums, synergies, and tax implications aren’t factored into your standalone valuation. A strategic acquirer might pay 20-30% above NPV if your business fills a gap in their supply chain. Conversely, a financial buyer (like a PE firm) will discount aggressively for lack of operational synergies. Forbes data shows that synergy assumptions can add or subtract 15-25% from the final purchase price, even if the NPV remains unchanged. Another wild card? The exit multiple. If your industry’s exit multiples are rising (e.g., SaaS companies now fetch 12x revenue vs. 8x five years ago), your NPV increases not because cash flows improved, but because the terminal value’s growth rate assumption becomes more optimistic. The reverse is true in downturns. A 2008-era Forbes analysis of financial services firms found that NPVs dropped 25-40% not because earnings fell, but because exit multiples collapsed."NPV is less about math and more about storytelling. You’re not just presenting numbers—you’re selling a vision of what your business will be in five, ten, or twenty years. The discount rate isn’t arbitrary; it’s the market’s vote of confidence in that story." — Forbes Valuation Advisory Board, 2023
| Factor | Impact on NPV (Estimated Range) |
|---|---|
| Discount Rate Adjustment (e.g., +2%) | 10-15% decrease in NPV |
| Terminal Growth Rate (e.g., 3% vs. 5%) | 20-30% difference in terminal value |
| Customer Concentration (>30% from one client) | 15-25% higher discount rate applied |

Conclusion
The answer to how much is my business worth net present value forbes isn’t a single number—it’s a range defined by your industry’s risk appetite, your ability to articulate growth, and the timing of the exit. The businesses that command premium NPVs aren’t always the most profitable; they’re the ones that can justify their projections with data, mitigate perceived risks, and align with buyer motivations. A $10M-revenue business in a niche market might have a higher NPV than a $50M-revenue conglomerate if the former has scalable tech and the latter lacks clear succession. The hard truth? Most business owners overestimate NPV by focusing on top-line revenue rather than free cash flow. Forbes’ valuation teams spend more time on working capital efficiency and capital expenditure cycles than on gross margins. If your NPV feels low, ask: Are we projecting realistic growth rates? Is the discount rate too optimistic? The difference between a $20M and $30M valuation often comes down to these details—not the headline revenue.Comprehensive FAQs
Q: How does Forbes determine the discount rate for NPV calculations?
Forbes analysts use a weighted average cost of capital (WACC) that combines: - The cost of debt (based on your current interest rates and leverage). - The cost of equity (derived from the Capital Asset Pricing Model, or CAPM, adjusted for sector beta). - A risk premium specific to your industry (e.g., biotech may add 4-6% over tech). For mid-market firms, WACC typically ranges from 12-18%, but early-stage startups can see rates above 20%. The rate isn’t static—it’s recalibrated during due diligence based on market conditions.
Q: Can I increase my business’s NPV without growing revenue?
Yes, but it requires operational leverage. Forbes highlights three high-impact levers: 1. Improving free cash flow conversion (e.g., reducing working capital by 10-15%). 2. Lowering capital expenditures (e.g., shifting to SaaS from on-premise software). 3. Reducing customer concentration risk (diversifying revenue streams to justify a lower discount rate). A case study from Forbes showed a $15M-revenue firm increasing NPV by $3M simply by reducing days sales outstanding (DSO) from 60 to 45 days—no revenue growth needed.
Q: What’s the most common mistake in NPV calculations?
Overestimating terminal value. Many business owners assume perpetual growth rates of 5-7%, but Forbes data shows that 2-4% is more realistic for most industries. A 3% growth rate assumption can cut terminal value by 30-50% compared to a 5% assumption. The second biggest error? Ignoring exit multiples—if your industry’s multiples are declining (e.g., from 10x EBITDA to 8x), your NPV drops even if cash flows stay flat.
Q: How do strategic buyers vs. financial buyers affect NPV?
Strategic buyers (e.g., a competitor acquiring you) often pay 20-40% above NPV because they assume synergies (cost savings, revenue growth). Financial buyers (PE firms, family offices) pay closer to NPV because they lack operational synergies. Forbes’ 2022 exit market report found that strategic sales commanded 1.5-2x the NPV of financial sales for businesses under $100M in revenue. The catch? Strategic buyers scrutinize NPV assumptions more aggressively—they’ll challenge your growth projections with their own data.
Q: Should I use NPV or multiples for my valuation?
NPV is better for growth-stage businesses with unpredictable cash flows, while multiples work for stable, mature firms. Forbes recommends using both: - NPV for startups, turnaround situations, or businesses with intangible assets (e.g., IP, brand). - Multiples (EBITDA, revenue) for established firms in cyclical industries (e.g., manufacturing, retail). A hybrid approach—NPV for the core business + multiples for assets—is common in mid-market deals. For example, a Forbes-backed valuation of a $25M-revenue tech firm used NPV for its software IP but applied a 7x revenue multiple to its hardware division.
Q: How often should I recalculate my business’s NPV?
At least annually, or whenever: - Your industry’s discount rates shift (e.g., Fed rate hikes). - You achieve a major milestone (e.g., new product launch, client contract). - Market conditions change (e.g., recession, sector consolidation). Forbes’ valuation teams recalculate NPV quarterly for portfolio companies, but most business owners can get away with semi-annual updates. The key is tracking sensitivity analysis—how small changes in growth rate or discount rate affect the final NPV. A 1% change in the discount rate can swing NPV by 5-10%, so staying current is critical.
