
Breaking Down the Numbers
To approach the kinokuniya bookstore net worth, it’s essential to distinguish between what’s verifiable and what’s speculative. The company’s last available consolidated financials, filed in 2022, showed total sales for the Kinokuniya Group hovering around ¥100 billion annually (approximately $680 million at the time). However, this figure includes all business segments, not just bookselling. Breaking it down further requires parsing regulatory filings, press releases, and third-party analyses—each offering fragments rather than a complete picture. The bookselling division itself is estimated to account for roughly 40–50% of total revenue, according to industry estimates. This would place its annual turnover in the ¥40–50 billion range ($270–340 million). Yet revenue alone doesn’t translate to net worth. Kinokuniya’s profitability is bolstered by its premium positioning—think limited-edition manga, rare English-language hardcovers, and stationery priced as lifestyle statements. Margins in this segment are likely higher than traditional booksellers, but exact figures remain undisclosed. The company’s real estate holdings, particularly prime Tokyo locations, add another layer of asset value, though these are rarely quantified separately.The Verified Baseline
Publicly available data offers a few concrete anchors. Kinokuniya’s IPO in 2013 on the Tokyo Stock Exchange provided a snapshot of its valuation at the time: the company was valued at roughly ¥20 billion ($200 million) during its listing. However, it delisted shortly afterward, returning to private ownership—a move that further obscured financial transparency. Since then, the group has expanded aggressively in Asia, opening stores in Singapore, Hong Kong, and Malaysia, while maintaining its dominance in Japan. The most reliable metric comes from real estate appraisals. Kinokuniya’s Ginza store, for instance, occupies a prime 10,000-square-meter space in one of Tokyo’s most expensive districts. While the company doesn’t disclose lease or ownership details, industry sources suggest the property’s value alone could exceed ¥50 billion ($340 million). This single asset underscores why the kinokuniya bookstore net worth is often discussed in terms of both revenue and physical capital. Even without digging into intangibles like brand equity, the tangible assets provide a floor for valuation estimates.What the Estimates Suggest
Private equity analysts and retail consultants who’ve modeled Kinokuniya’s worth typically arrive at figures ranging from ¥80 billion to ¥150 billion ($540 million to $1 billion) for the entire group. This range accounts for: - Bookselling revenue (¥40–50 billion annually), - Stationery and travel goods (another ¥20–30 billion), - Real estate holdings (including flagship stores and warehouses), - Brand value, which for a company like Kinokuniya is substantial given its status as a cultural institution. However, these estimates are fluid. The kinokuniya bookstore net worth isn’t static; it fluctuates with market conditions, expansion plans, and even geopolitical factors (e.g., demand for Japanese content in Asia). The company’s decision to remain private means no forced disclosures, leaving room for speculation. Some analysts argue that if Kinokuniya were to relist, its valuation could spike due to its defensible niche—few competitors combine physical retail with such deep cultural cachet.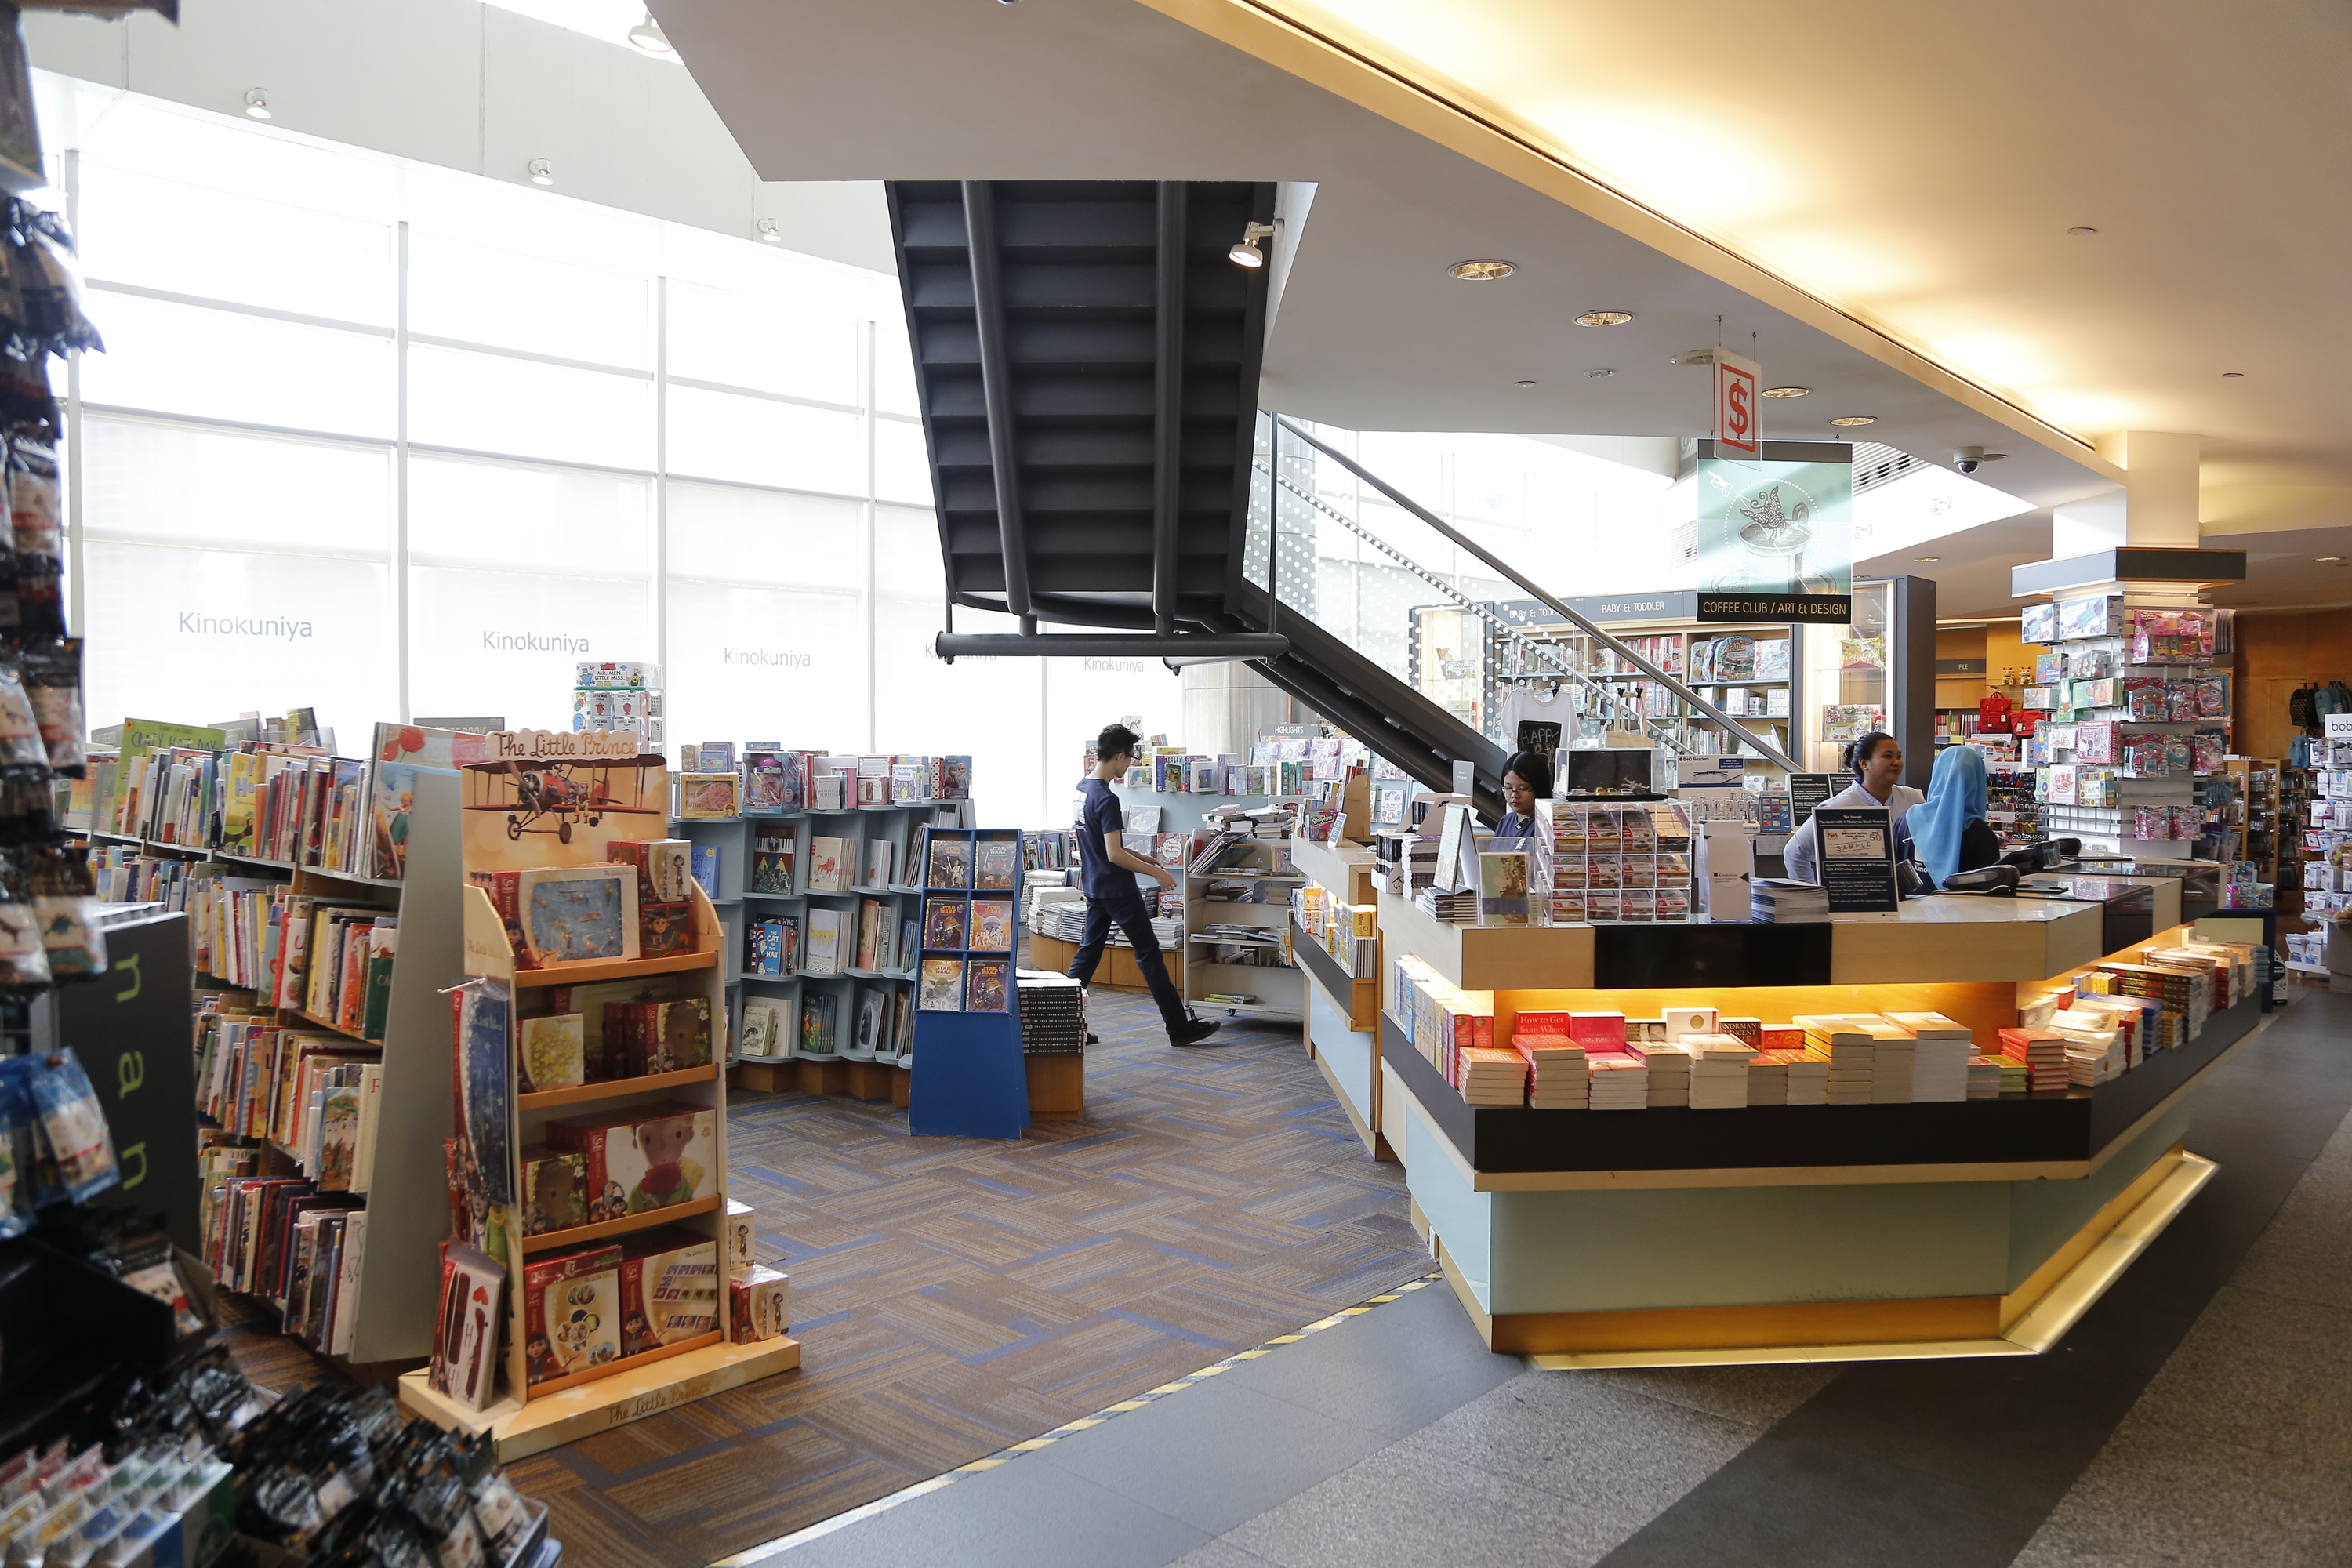
Case Study: A Closer Look
Consider Kinokuniya’s 2018 acquisition of The Book Depository, a Dubai-based online bookseller catering to English-language readers in the Middle East and Asia. The deal, though not publicly priced, highlighted the company’s strategy: expanding beyond physical stores into digital and regional markets. This move wasn’t just about e-commerce; it was about consolidating Kinokuniya’s position as the go-to destination for English books in non-English-speaking markets. The acquisition also diversified revenue streams, reducing reliance on Tokyo-centric sales. The impact of this decision can be measured in several ways: - Market expansion: The Book Depository’s global shipping model complemented Kinokuniya’s brick-and-mortar focus. - Customer overlap: Many of The Book Depository’s clients were also Kinokuniya’s target demographic—expats, students, and collectors. - Operational synergy: Kinokuniya’s supply chain could now serve both online and offline channels more efficiently.| Factor | Estimated Impact on Kinokuniya’s Valuation |
|---|---|
| Acquisition of The Book Depository | Added ~$20–30 million in annual revenue; long-term brand synergy effects unclear. |
| Ginza flagship store real estate | Property value estimated at ¥50+ billion; contributes to enterprise value but not directly to profit margins. |
| Stationery and lifestyle goods margins | Higher than bookselling (reportedly 30–40% vs. 10–20% for books), but exact figures undisclosed. |
| Brand equity in Asia | No precise valuation, but comparable to luxury retailers; likely adds 20–30% premium to asset-based estimates. |
| Private ownership (no IPO pressure) | Reduces transparency but may allow for strategic long-term investments without shareholder scrutiny. |
"Kinokuniya isn’t just selling books—it’s selling an experience. That’s why its valuation isn’t just about inventory or square footage. It’s about the emotional connection to its stores, the trust built over a century, and the fact that, for many, stepping into a Kinokuniya is like entering a temple of knowledge." — Retail analyst, Tokyo-based
What This Means Going Forward
Kinokuniya’s financial trajectory hinges on three key variables. First, digital transformation: While the company has dabbled in e-commerce, its core remains physical retail. The rise of Amazon and local e-readers could pressure margins if Kinokuniya fails to innovate. Second, geographic expansion: Asia’s growing middle class presents opportunities, but political risks (e.g., China’s market access restrictions) could complicate plans. Finally, pricing power: Kinokuniya’s ability to maintain premium pricing depends on its ability to differentiate itself—not just as a bookseller, but as a cultural institution. The company’s kinokuniya bookstore net worth will also be shaped by external forces. For instance, Japan’s aging population and shrinking domestic book market could push Kinokuniya to rely more on international sales. If it were to pursue another IPO or partial sale, the valuation would likely reflect its unique blend of retail, real estate, and cultural capital. However, given its private status, such moves remain speculative.
Conclusion
The kinokuniya bookstore net worth is less about hard numbers and more about intangibles—trust, location, and the unquantifiable allure of its stores. While estimates place its value in the hundreds of millions to over a billion dollars, these figures are educated guesses at best. What’s undeniable is Kinokuniya’s resilience. In an era where bookstores are closing globally, it has thrived by doubling down on premium positioning, cultural relevance, and strategic acquisitions. For investors, the challenge is separating hype from substance. For customers, the value is simpler: Kinokuniya isn’t just a place to buy books—it’s a destination. And in the end, that’s what keeps the lights on, even when the ledgers stay private.Comprehensive FAQs
Q: Is Kinokuniya publicly traded?
No. Kinokuniya was briefly listed on the Tokyo Stock Exchange in 2013 but delisted shortly afterward, returning to private ownership. This lack of transparency makes precise valuation difficult.
Q: How does Kinokuniya’s net worth compare to other global bookstore chains?
Kinokuniya’s estimated net worth (¥80–150 billion) is dwarfed by publicly traded giants like Barnes & Noble (market cap: ~$1.5 billion) but exceeds many niche retailers. Its strength lies in brand equity and real estate, not just revenue.
Q: Does Kinokuniya disclose profit margins?
No. While industry estimates suggest stationery and lifestyle goods margins are 30–40%, and bookselling margins around 10–20%, the company does not break these figures down publicly.
Q: Has Kinokuniya ever sold a store or asset?
There are no widely reported cases of Kinokuniya selling a flagship store. However, it has leased space in high-traffic locations (e.g., Tokyo’s Ginza) rather than owning outright, which affects valuation models.
Q: Could Kinokuniya’s valuation increase if it went public again?
Possibly. A relisting might unlock higher valuations due to investor speculation on its cultural brand value, but it could also face scrutiny over its real estate-heavy balance sheet and slower digital adoption.
Q: What’s the biggest risk to Kinokuniya’s financial health?
The shrinking domestic book market in Japan and competition from e-commerce pose the greatest threats. Kinokuniya’s reliance on premium pricing means it must continuously justify its value proposition to younger, cost-conscious consumers.
Q: Are there any rumors of Kinokuniya being acquired?
No credible rumors have surfaced in recent years. The company appears focused on organic growth (e.g., expanding in Southeast Asia) rather than mergers or takeovers.
