The Short Answers
- Edmund Morris’ net worth is not publicly disclosed, but industry estimates place it in the mid-to-high six figures—far below the fortunes of commercial authors but comfortable for a literary figure of his stature.
- His primary income sources have been book advances, royalties, and academic salaries, with occasional lecture fees and media appearances contributing to his financial stability.
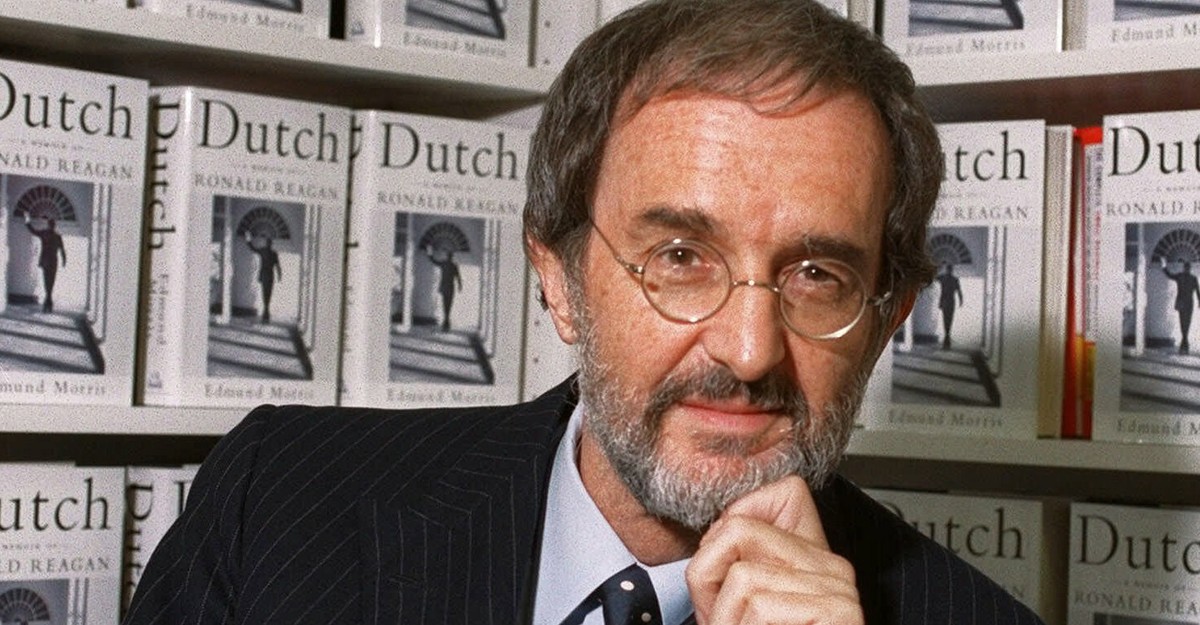
- While Dutch: A Memoir of Ronald Reagan was a bestseller, its advance was not in the range of modern political memoirs (e.g., $1M+), reflecting the lower commercial expectations for literary biography in the late 20th century.
- Morris has never been associated with high-profile business ventures, real estate speculation, or endorsements, keeping his wealth tied to traditional intellectual pursuits.
- His lowest-earning periods likely coincided with the decline in print journalism and the rise of digital media, which shifted cultural capital away from long-form biography.
- Unlike contemporaries who leveraged their fame into media empires (e.g., Stephen King’s film deals), Morris’ wealth remains rooted in his reputation as a historian, not a brand.

Deep Dive: The Full Picture
Edmund Morris’ career arc mirrors the evolution of American biography itself—a genre that peaked in the mid-20th century before fragmenting into niches. His breakthrough, The Rise of Theodore Roosevelt, arrived at a moment when presidential biographies were still considered high art. The book’s Pulitzer win cemented his place in literary history, but the financial rewards were modest by today’s standards. Advances in the 1970s and 1980s for serious nonfiction rarely exceeded six figures, even for winners of major awards. Morris’ subsequent works—Columbus: The Four Voyages (1970) and Fool for Love (1989)—sold steadily but didn’t generate the kind of secondary income (e.g., film adaptations, merchandising) that could balloon an author’s net worth. The Reagan biography, Dutch, changed the game—but not in the way one might expect. Published in 1999, it became a New York Times bestseller, staying on the list for weeks. Yet the advance Morris secured was likely well below the seven figures that political figures like Newt Gingrich or Hillary Clinton now command for their memoirs. The difference lies in audience: Morris wrote for readers who valued prose over scandal, a demographic that shrunk as tabloid-style political narratives dominated the market. His later years saw fewer major publications, a trend common among authors whose work becomes a reference point rather than a commercial product.The Context You Need
To understand Edmund Morris net worth, one must account for the decline of print journalism’s golden age. In the 1960s and 1970s, magazines like The New Yorker and Harper’s paid premium rates for long-form journalism—a field where Morris honed his craft. Those earnings, while substantial at the time, don’t translate to modern wealth metrics. By the 1990s, as digital media ate into print’s dominance, the market for serious nonfiction contracted. Morris’ refusal to chase trends (e.g., self-help, celebrity tell-alls) meant his income streams narrowed. Academia offered stability. His tenure at Princeton and other institutions provided a steady paycheck, though university salaries have never been a path to wealth accumulation. Lectures and public readings added incremental income, but these rarely rivaled the sums generated by commercial speaking tours. The key insight? Morris’ financial comfort wasn’t built on Edmund Morris financial empire but on a lifetime of modest, consistent earnings—a model increasingly rare in an era of viral fame and algorithm-driven success.The Mechanics
Book advances are the most visible component of how Edmund Morris built his wealth, but they’re deceptive. A six-figure advance for Dutch might sound substantial, but it was spread over years of research and writing. Royalties, meanwhile, are a slow burn: Morris’ books likely earn a few thousand dollars annually per title, not the millions associated with mass-market paperbacks. His later career saw fewer advances, as publishers grew wary of betting on literary biography in an age of declining print sales. Tax implications further complicate the picture. As a nonfiction author, Morris would have benefited from long-term capital gains rates on book sales, but his primary income—salaries, advances—was taxed at ordinary rates. Unlike investors or tech founders, he had no Edmund Morris asset diversification beyond books, real estate (if any), and perhaps modest investments. His wealth, in other words, was liquid but not leveraged—a reflection of his priorities.Details That Change the Picture
The Reagan biography’s cultural impact far outstripped its financial one. While Dutch sold over 500,000 copies, its advance was nowhere near the $1M+ that modern political memoirs command. The discrepancy highlights how Edmund Morris’ financial trajectory was tied to an older publishing economy—one where prestige mattered more than marketability. His later works, Lessons of History (2011) and Eye on Reagan (2014), sold in far smaller numbers, suggesting a gradual decline in commercial viability. Morris’ personal life also played a role. Unlike authors who monetize their personal brands (e.g., through social media, merchandise), he remained a private figure, avoiding the kind of public persona that could generate side income. His marriage to historian Patricia O’Toole provided intellectual collaboration but no financial synergy. Even his Reagan connections, while invaluable for access, didn’t translate into Edmund Morris business ventures—no consulting gigs, no Reagan-branded products."The biographer’s job is to tell the truth, not to sell it." —Edmund Morris, in a 2000 interview with The Paris Review
| Income Source | Estimated Contribution to Net Worth |
|---|---|
| Book advances (pre-2000) | Mid-six figures (lifetime) |
| Royalties (ongoing) | Low five figures annually |
| Academic salaries | Modest but stable (1980s–2010s) |
Conclusion
Edmund Morris’ financial story is one of quiet accumulation, not sudden wealth. His net worth—whatever the exact figure—reflects a career where intellectual capital outpaced financial capital. In an era where authors chase bestseller lists and media empires, Morris’ trajectory is a relic of a time when Edmund Morris net worth was measured in influence, not Instagram followers. His legacy isn’t in the size of his bank account but in the way he shaped how we remember presidents and history itself. Yet his financial journey also serves as a cautionary tale. The publishing industry’s shift toward digital and commercial nonfiction has left literary biographers like Morris in a precarious position. Without the ability to monetize their work through modern channels—social media, film rights, or self-publishing—authors of his ilk must rely on the fading prestige of print. For Morris, that’s been enough. For future generations of historians, it may not be.Comprehensive FAQs
Q: Did Edmund Morris ever disclose his net worth?
No. Unlike commercial authors or celebrities, Morris has never publicly discussed his financial standing, a rarity even among literary figures. His focus has remained on his work, not his wealth.
Q: How does his net worth compare to other presidential biographers?
Morris’ estimated net worth is likely far lower than that of contemporary political biographers like Michael Wolff or Karen Blumenthal. While Wolff’s Fire and Fury reportedly earned him millions in advances and media deals, Morris’ earnings were tied to literary prestige, not commercial exploitation.
Q: Did Dutch: A Memoir of Ronald Reagan make him wealthy?
The book was a critical and commercial success, but its financial impact on Morris’ net worth was modest by modern standards. Advances for literary biography in the late 1990s rarely exceeded $500,000–$1M, and royalties from hardcover sales would have been a fraction of that.
Q: Has Edmund Morris invested in real estate or other assets?
There’s no public record of Morris owning high-value real estate or diversifying into investments. His wealth appears to be primarily liquid, tied to book earnings and academic income rather than assets.
Q: Why hasn’t he written more books to increase his net worth?
Morris’ writing pace has always been deliberate. Unlike authors who churn out books for commercial gain, his work requires decades of research—a process that doesn’t align with the fast turnover needed to maximize royalties. His later books reflect this approach.
Q: Could he have earned more by writing for Hollywood?
Morris has never pursued film or TV adaptations of his work, a choice that would have likely increased his earnings but at the cost of creative control. His biographies are literary, not commercial—a stance that prioritizes integrity over profit.
