
Breaking Down the Numbers
The net worth of average doctor is a moving target, shaped as much by geography as by profession. A 2023 Medscape compensation report placed the median total compensation for U.S. physicians at $315,000, but that figure obscures critical details: it includes bonuses, productivity incentives, and regional adjustments. When stripped down to take-home pay—after malpractice insurance, practice overhead, and taxes—the picture shifts. In California, a general surgeon might net $350,000 annually, while a Mississippi family doctor could see $180,000 after deductions. The disparity isn’t just about income; it’s about how quickly that income translates to wealth. Wealth accumulation hinges on two variables: liquidity and leverage. Doctors in high-cost states often face a "wealth drag"—their salaries vanish into mortgages, childcare, and healthcare premiums before they can invest. Meanwhile, those in lower-cost areas or with early financial planning (e.g., tax-advantaged retirement accounts) see their net worth compound faster. The net worth of average doctor isn’t linear; it’s a function of when they entered the field (pre- or post-2008 financial crisis), their debt load, and whether they chose private practice or academia. For context, a 2022 survey by the American Medical Association found that 40% of physicians under 40 had net worths below $100,000—a figure that would shock those who assume white coats equate to instant affluence.The Verified Baseline
Publicly available data paints a stark contrast between gross earnings and net worth. The U.S. Bureau of Labor Statistics reports that physicians and surgeons earned a median annual wage of $208,000 in 2022, but this excludes self-employed doctors (who often earn more but face variable expenses). The Federal Reserve’s Survey of Consumer Finances offers a rare glimpse into physician net worth: in 2022, households headed by someone with a professional degree (including doctors) had a median net worth of $636,500—double the national median. However, this aggregate number masks critical outliers. Pediatricians, for instance, frequently cite lower net worths due to lower earning potential and higher lifestyle costs tied to family needs. What’s verifiable is that debt is the great equalizer. The average medical school graduate in 2023 leaves with $200,000 in student loans, a figure that can balloon to $300,000+ for those pursuing residencies in high-cost specialties like dermatology or ophthalmology. Repayment timelines vary: some doctors use income-driven repayment plans (capping payments at 10–20% of discretionary income), while others aggressively pay down loans in their 30s. The latter strategy can accelerate net worth growth by 20–30 years, but it requires disciplined budgeting—a skill not all physicians prioritize, given the mental load of their careers.What the Estimates Suggest
Industry estimates suggest that the net worth of average doctor stabilizes around $1 million to $2 million by age 50, but this is highly dependent on specialization. High-earning specialties—such as cardiology, orthopedics, and radiology—often see physicians hit $3 million+ by retirement, particularly if they own practices or invest in real estate. Lower-earning fields (primary care, psychiatry) may plateau at $500,000–$1 million, especially if practitioners take public-sector roles with lower pay but reduced overhead. The Mercer Marsh Benefits 2023 Survey estimated that physicians in their peak earning years (ages 45–55) have net worths ranging from $1.5 million to $5 million, with the top 10% exceeding $10 million. Lifestyle choices further refine these estimates. Doctors who defer gratification—prioritizing loan repayment over luxury spending—can see their net worth grow 3–5x faster than peers who treat their salaries as disposable income. For example, a dermatologist in Boston might spend $20,000 annually on childcare and private education, while a rural OB-GYN could allocate that budget to index funds. The estimates also assume no major financial missteps: divorce, malpractice lawsuits, or poor investment decisions can derail even the most optimistic projections. What’s clear is that the net worth of average doctor isn’t a static number—it’s a dynamic equation where timing, location, and personal finance skills play equal roles.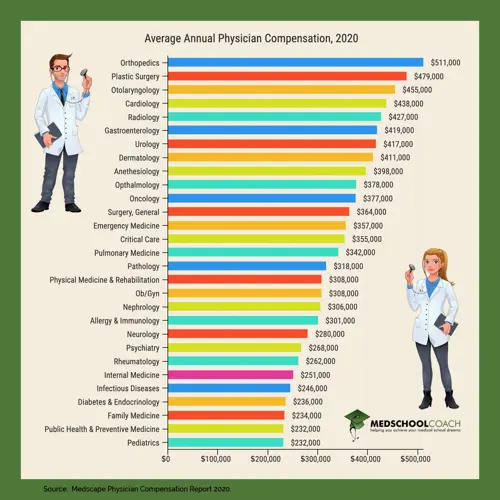
Case Study: A Closer Look
Consider Dr. Elena Vasquez, a 42-year-old family physician in Albuquerque, New Mexico. She graduated from medical school in 2010 with $180,000 in debt, entered a residency program that offered loan forgiveness for primary care, and began practicing in 2013. By 2023, her gross income hovered around $220,000, but her net worth—after repaying $120,000 of her loans and investing in a rental property—stood at $850,000. Her frugality (owning a 2018 SUV, cooking at home, and avoiding credit card debt) allowed her to max out her 401(k) and Roth IRA contributions annually. Had she chosen private practice in Manhattan, her income might have been 50% higher, but her net worth would likely be 20–30% lower after accounting for New York’s cost of living. What separates Dr. Vasquez from her peers isn’t just her salary, but her debt-to-income ratio and asset allocation. Her story underscores a critical truth: the net worth of average doctor isn’t determined by the size of their paycheck alone. It’s a product of how aggressively they manage debt, where they live, and what they prioritize. For high-earning specialists, the equation shifts—owning a medical practice can mean $1 million+ in annual revenue, but also $500,000 in practice overhead, leaving less liquidity for personal wealth-building."People assume doctors are rich because they see the big salaries, but the reality is that wealth is about cash flow, not just income. If you’re spending $10,000 a month on a penthouse in Miami, you’re not building equity—you’re just funding someone else’s mortgage." — Dr. Raj Patel, financial advisor to physicians (2023)
| Factor | Estimated Impact on Net Worth |
|---|---|
| Student Loan Debt | Can reduce net worth by $100,000–$300,000 in early career if not managed aggressively. |
| Geographic Location | Living in a high-cost state (e.g., California) can halve net worth growth compared to a low-cost state. |
| Specialization | High-earning specialties (e.g., surgery) may see 2–3x faster net worth accumulation than primary care. |
| Investment Discipline | Physicians who invest >20% of income annually see net worth grow 40% faster than average. |
What This Means Going Forward
The net worth of average doctor is evolving alongside healthcare’s economic pressures. Rising malpractice insurance costs (up 15% annually in some states), the shift from fee-for-service to value-based care, and the looming student debt crisis for incoming classes will reshape physician wealth trajectories. Younger doctors entering the field today face $300,000+ in loans—a figure that, when combined with stagnant salary growth in primary care, could delay wealth accumulation by a decade. Meanwhile, the gig economy for physicians (e.g., telemedicine, locum tenens) offers flexibility but often at the expense of long-term financial stability. For those already established, the key to maintaining—or growing—their net worth lies in diversification. Real estate, private equity, and alternative investments (like farmland or wine collections) are increasingly popular among physicians looking to hedge against healthcare policy shifts. The days of simply "saving the rest" are fading; today’s high-earning doctors treat wealth management as a second career. This trend will likely persist, as the net worth of average doctor becomes less about raw income and more about financial agility in an unpredictable industry.
Conclusion
The net worth of average doctor is neither a fixed benchmark nor a guarantee of prosperity. It’s a product of structural advantages (high earning potential) tempered by structural challenges (debt, lifestyle inflation, and industry risks). The physicians who thrive are those who treat their finances with the same rigor they apply to patient care—anticipating risks, optimizing cash flow, and avoiding the pitfalls of lifestyle creep. For the next generation, the equation may grow even more complex, as student debt burdens rise and healthcare’s business model continues to evolve. What remains constant is the power of discipline over destiny. A doctor earning $300,000 in Texas can outpace a $500,000-earner in New York if the former invests wisely and the latter doesn’t. The net worth of average doctor isn’t just a statistic—it’s a testament to how financial habits, not just salaries, define long-term security.Comprehensive FAQs
Q: What’s the fastest way for a doctor to build net worth?
A: Aggressively pay down high-interest debt (student loans, credit cards), maximize tax-advantaged accounts (401(k), HSA), and invest at least 20% of income in low-cost index funds or real estate. Geographic arbitrage—living in a low-cost state—can accelerate growth by 30–50%.
Q: Do doctors in private practice have higher net worth than those in academia or public health?
A: Generally, yes—but with caveats. Private practitioners often earn more upfront but face practice overhead (malpractice insurance, staff salaries). Academics and public-sector doctors may earn less but enjoy lower lifestyle costs and pension benefits, which can yield comparable net worths by retirement.
Q: How does malpractice insurance affect a doctor’s net worth?
A: Premiums for high-risk specialties (obstetrics, surgery) can run $50,000–$100,000 annually, directly reducing take-home pay. Over a career, this can delay net worth growth by 5–10 years if not budgeted for. Tail coverage (insurance for past claims) adds another layer of expense.
Q: Can a doctor retire early with a net worth of $2 million?
A: It depends on withdrawal rate and location. The 4% rule suggests $80,000/year in passive income, but healthcare costs (insurance, long-term care) can erode this. In a low-cost state, $2 million may suffice for a $60,000–$70,000/year lifestyle. High-earning doctors often aim for $3–5 million to retire comfortably.
Q: What’s the biggest financial mistake doctors make?
A: Underestimating lifestyle inflation. Many assume their high salaries mean they can afford luxury spending, but without disciplined budgeting, they end up with high expenses but stagnant net worth. Others overlook tax planning—failing to use trusts, LLCs, or charitable giving to optimize wealth retention.
