Where It All Began
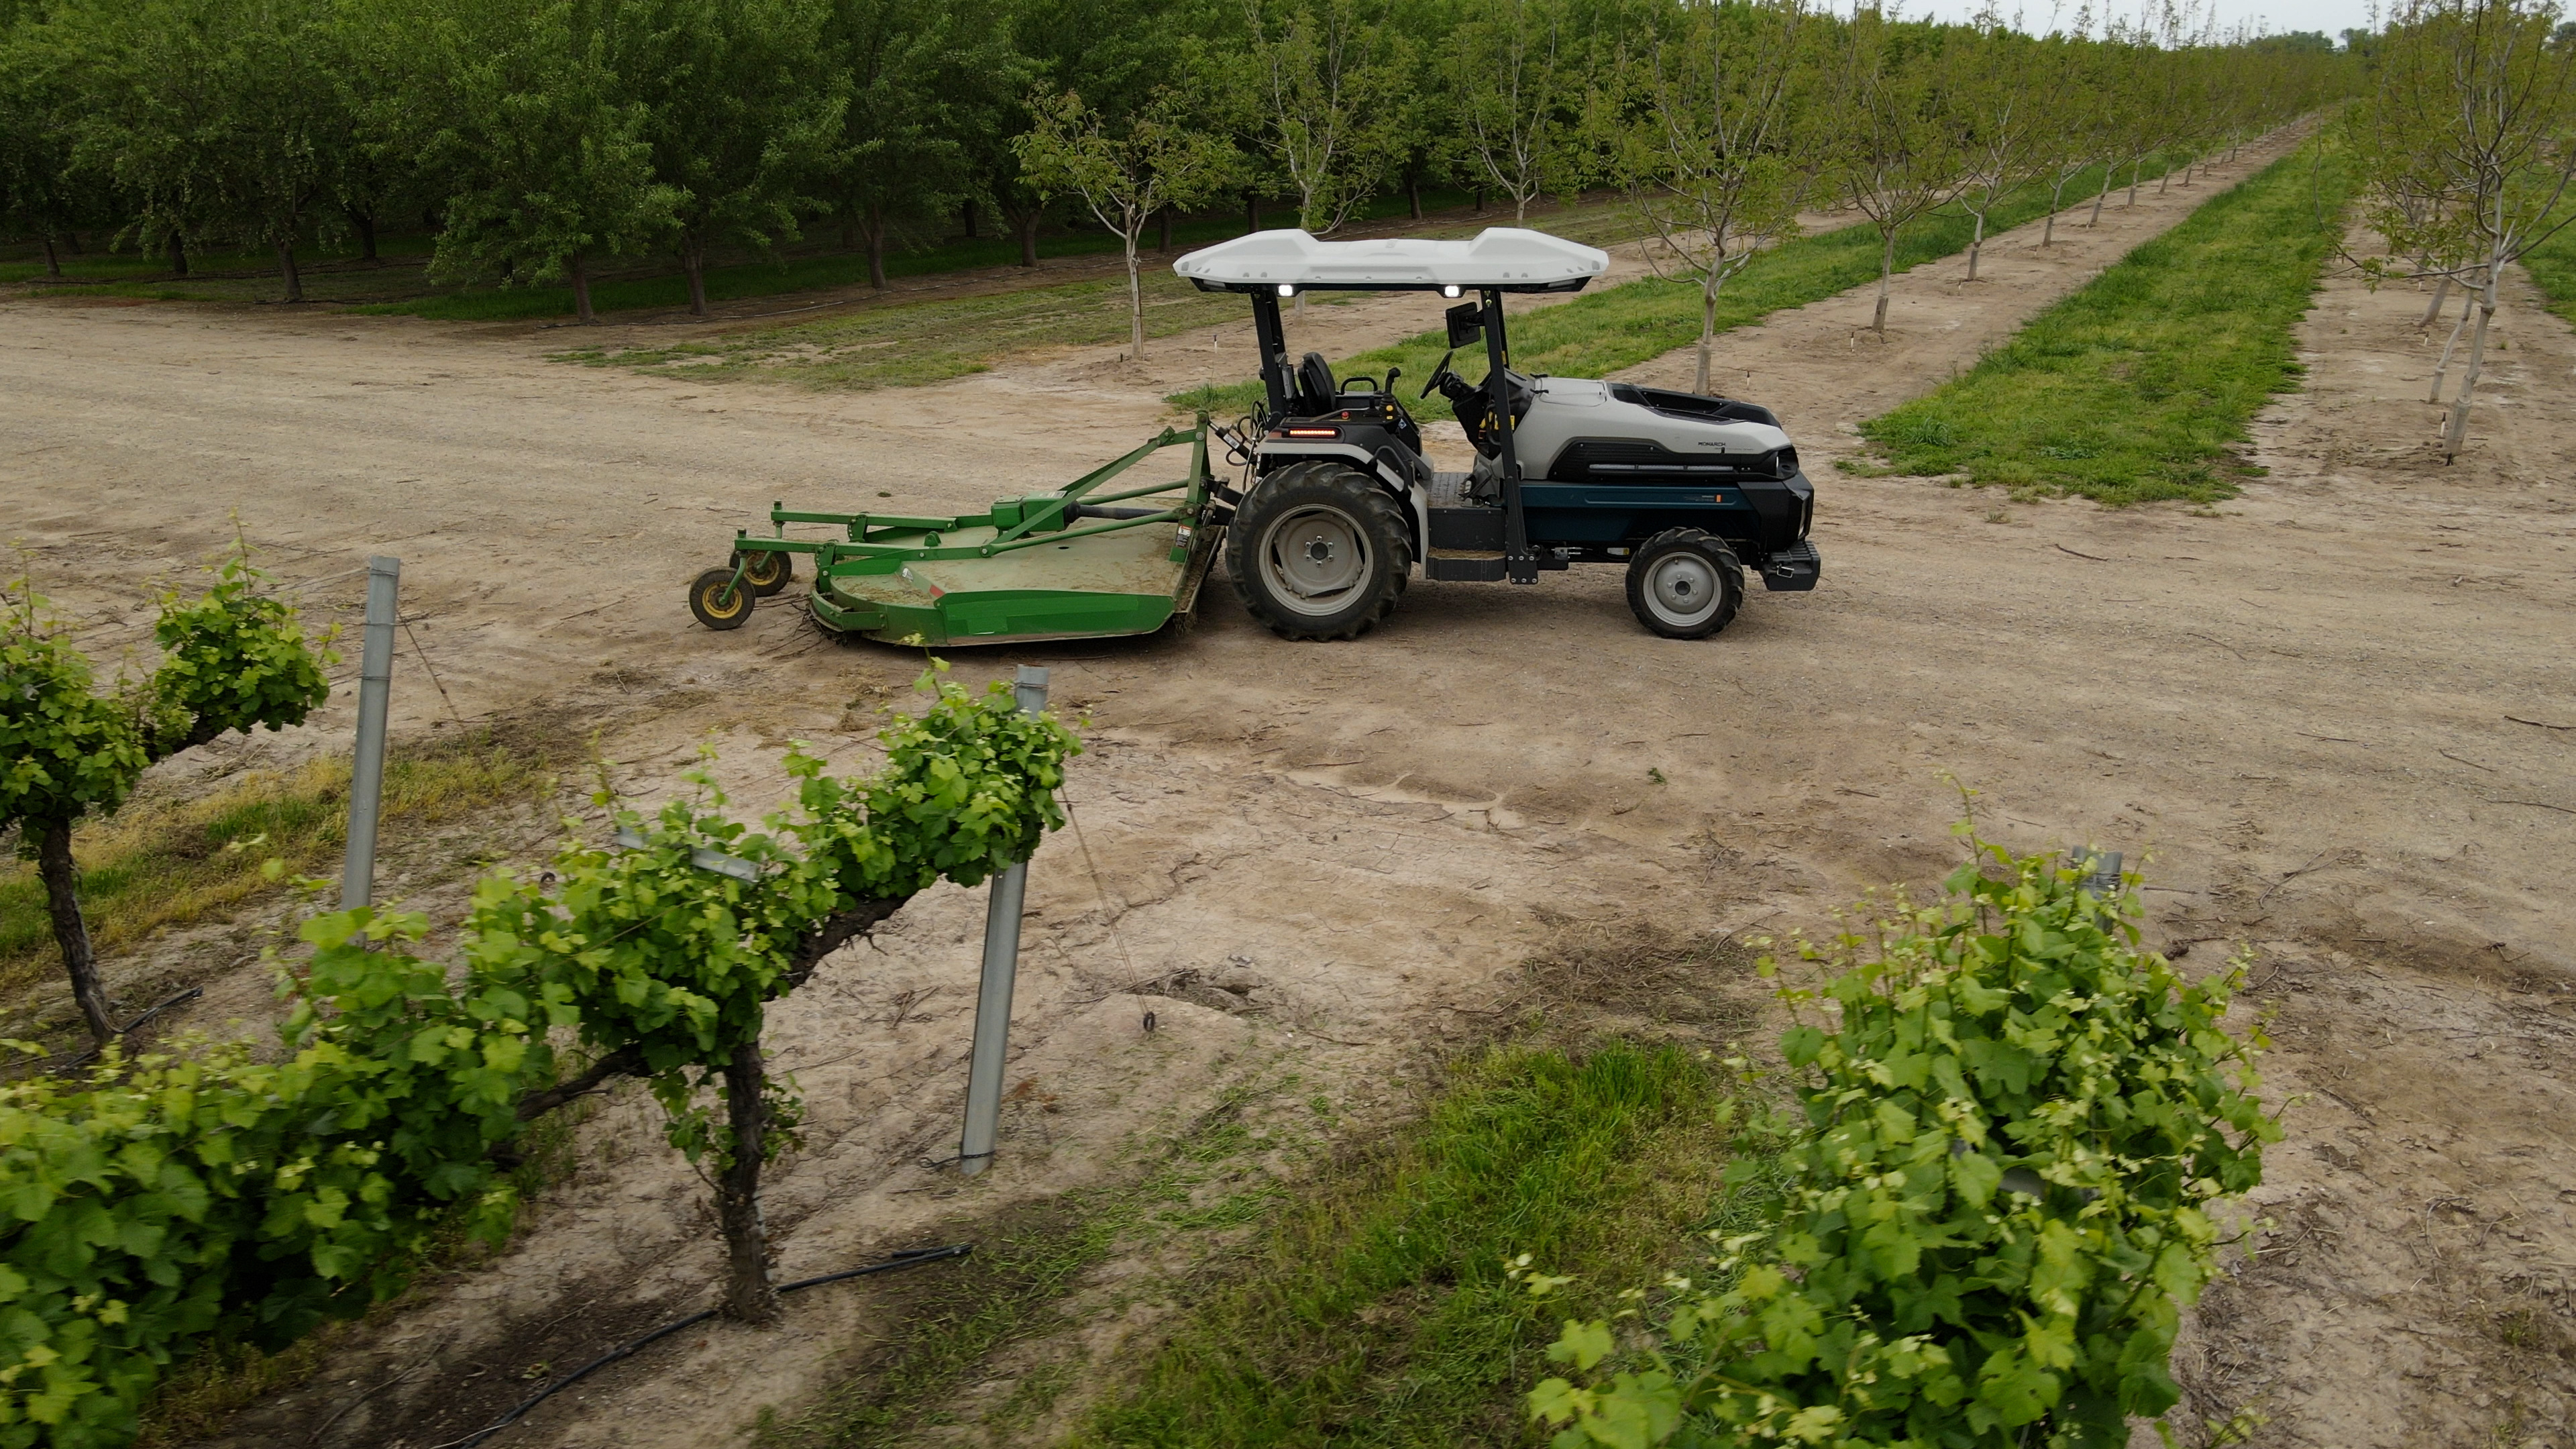
The seeds of today’s autonomous farming revolution were sown in the late 1990s, when GPS-guided steering systems first appeared on commercial tractors. These early autosteer units—like the Trimble GreenStar system—weren’t fully autonomous, but they automated the most tedious part of plowing: keeping straight rows. Farmers who adopted them saw yields climb by 5–10% overnight, but the self-driving tractor price for these basic systems was still prohibitive. In 1999, a full autosteer kit ran around $15,000, a sum that made sense only for large-scale operators. The real breakthrough came when sensor fusion—combining GPS, LiDAR, and camera data—became cheap enough to embed in farm equipment. By 2005, companies like AGCO and Deere were testing prototypes that could perform basic field operations without human intervention. The turning point arrived in 2011, when the U.S. Department of Agriculture began funding research into "smart farming" as part of its broader push for precision agriculture. Suddenly, venture capital flowed into startups like Blue River Technology, which developed a computer vision system to cull weeds in real time. These weren’t just tractors anymore; they were mobile data centers on wheels. The cost of autonomous tractors was still high, but the ROI calculations started to make sense. A study from the University of Illinois estimated that autonomous weeding could cut herbicide use by 90%, a critical factor as regulations tightened. The tech was no longer a luxury—it was a compliance tool.The Early Signs
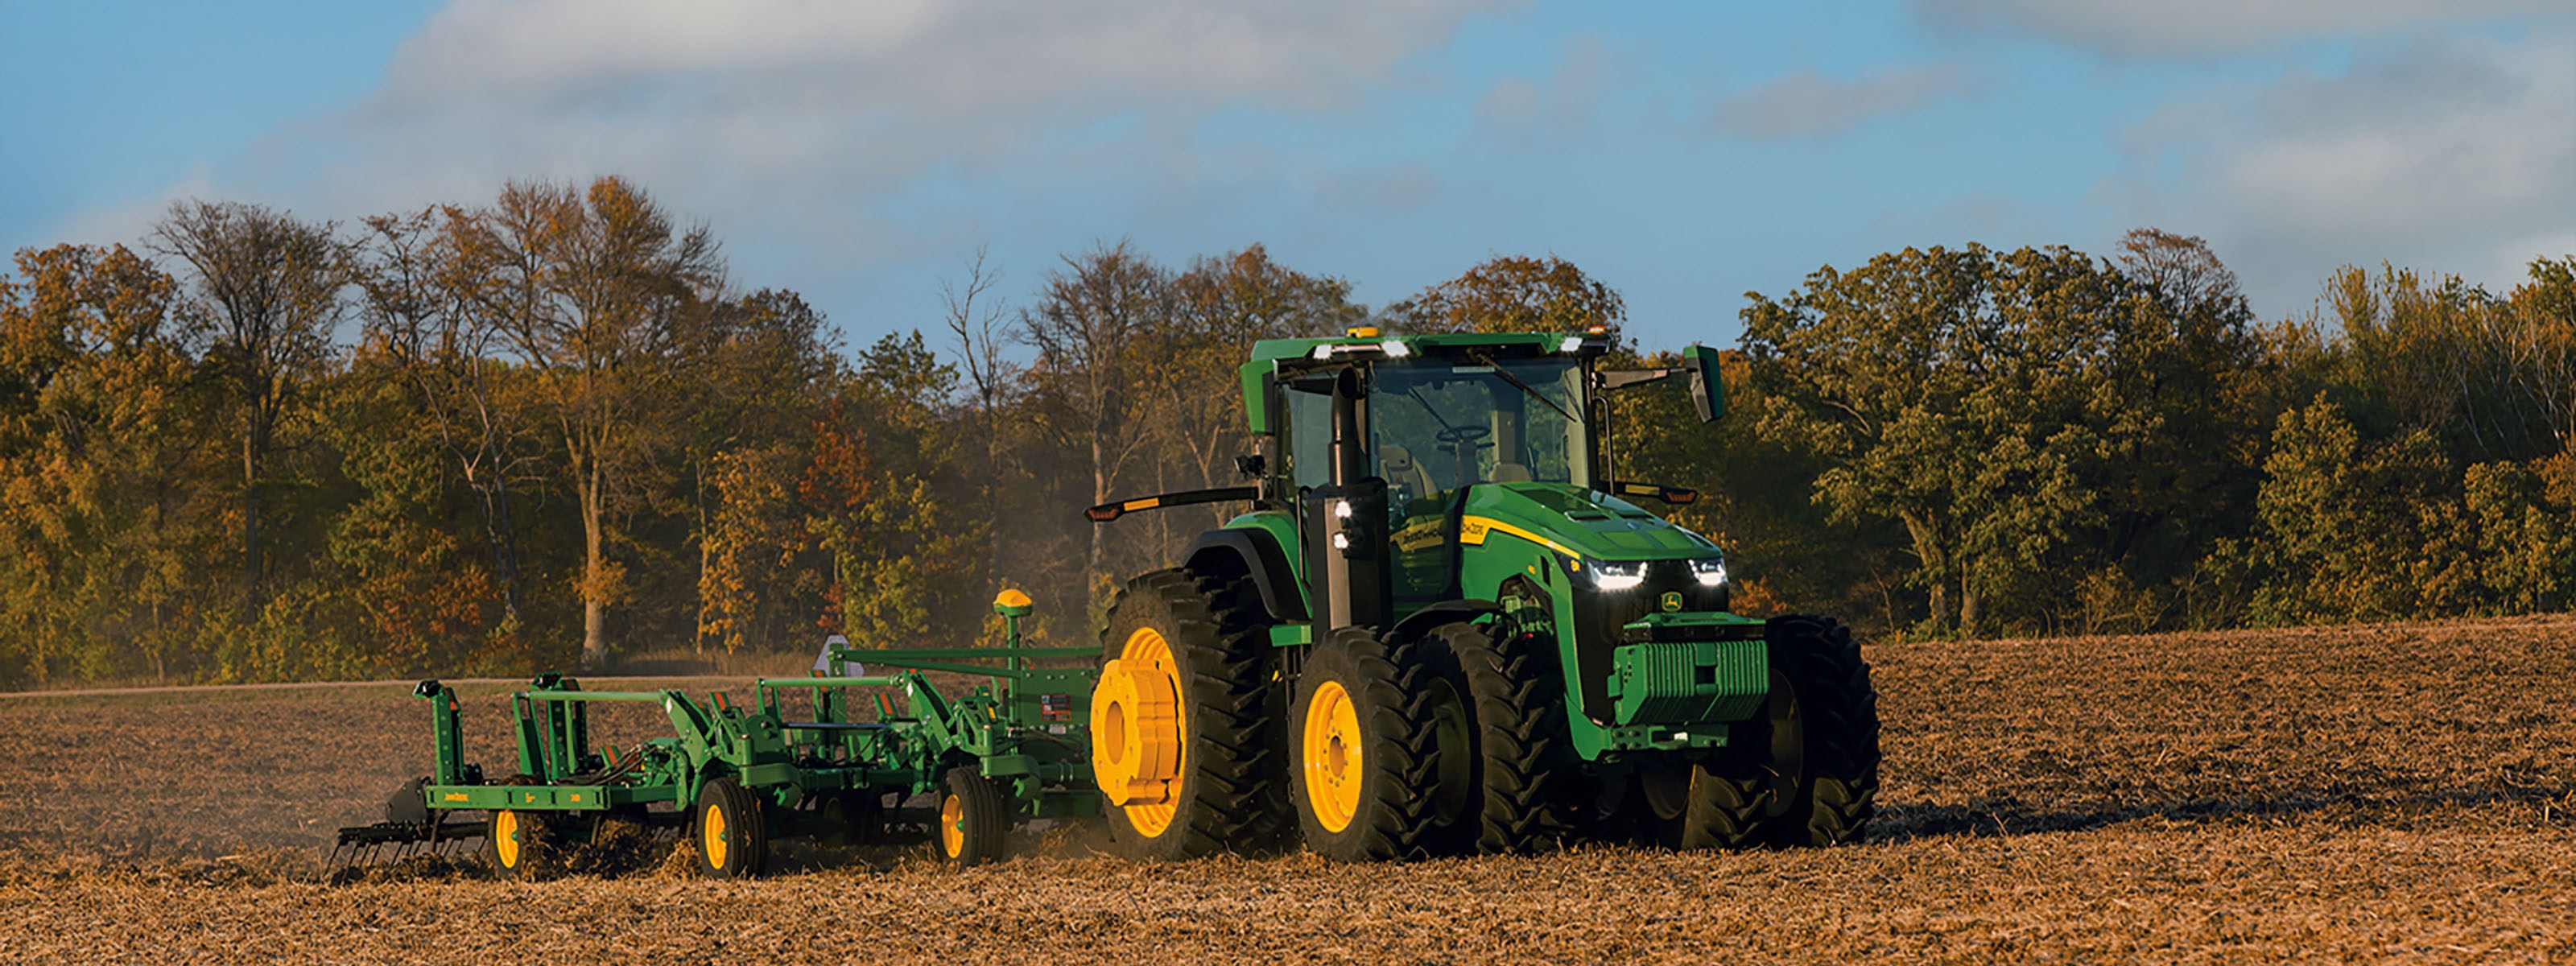
The first commercial autonomous tractors hit fields in 2014, but they weren’t what most people imagine today. Instead of sleek, driverless machines, they were retrofitted John Deere 8Rs with extra batteries and a human "spotter" walking alongside to intervene if the system faltered. The self-driving tractor price for these early models was eye-watering—reportedly in the $300,000–$500,000 range—but the real barrier was trust. Farmers who’d spent their lives gripping a steering wheel were suddenly asked to hand control to an algorithm. Glitches were inevitable. One viral video from a Canadian farm showed an autonomous swather veering into a ditch, its sensors confused by a sudden snowstorm. What saved the technology wasn’t perfection—it was scalability. By 2016, companies like Blue River had shrunk their systems enough to fit on smaller tractors, and the price of autonomous farming equipment began to drop. Leasing programs emerged, letting farmers test the tech without committing to a purchase. Meanwhile, European farmers, facing stricter labor laws, adopted autonomous solutions at twice the rate of their American counterparts. The lesson was clear: the self-driving tractor price wasn’t the only factor. Infrastructure mattered just as much.The Turning Point
The inflection point came in 2018, when John Deere announced it would stop selling its own GPS receivers and instead license the technology to competitors. The move was a seismic shift—Deere, the company that had dominated farm tech for decades, was admitting that no single player could corner the market alone. Around the same time, the European Union’s Common Agricultural Policy began offering subsidies for "digital farming" investments, effectively underwriting the cost of autonomous tractors for small and mid-sized farms. The writing was on the wall: autonomy wasn’t a niche play anymore. The final catalyst was the COVID-19 labor crisis. With migrant farmworkers stranded at borders and domestic crews scarce, the price of self-driving tractors became a secondary concern to the question of whether farms could stay operational. Governments in Australia and Brazil fast-tracked approvals for autonomous harvesters, and Chinese manufacturers flooded the market with low-cost, semi-autonomous models. By 2021, the self-driving tractor price had dropped by nearly 40% in some regions, thanks to economies of scale and the influx of new players."The moment farmers realized autonomy wasn’t about replacing them—it was about giving them back the hours they’d lost to exhaustion." — Mark Winegardner, CEO of Blue River Technology (2022)
The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 2005–2010 | GPS sensor fusion becomes viable; first prototypes tested in controlled environments. The self-driving tractor price remains experimental, with early adopters paying $200,000+ for custom builds. |
| 2011–2015 | USDA funding boosts R&D; Blue River and Seegrid enter the market. Leasing models emerge, reducing the upfront cost of autonomous tractors by 25–30%. First commercial failures highlight reliability gaps. |
| 2016–2020 | EU subsidies and Chinese manufacturers (e.g., XAG) drive prices down. John Deere’s autonomous combine, the Autonomous Concept Machine, debuts at $400,000. The price of self-driving tractors splits into high-end and modular tiers. |
| 2021–Present | Labor shortages accelerate adoption; Tesla’s robotics division sparks interest in scalable autonomy. The self-driving tractor price ranges from $50,000 (retrofits) to $1M+ (fully autonomous systems). Insurance and regulatory hurdles remain the biggest obstacles. |
Lessons From the Journey
- Price isn’t the only barrier. Even as the self-driving tractor price has fallen, adoption hinges on integration with existing farm infrastructure—something older equipment can’t handle.
- Subsidies make the difference. EU and Australian grants have driven adoption rates far higher than in the U.S., where federal support has been slower.
- Modularity wins. Retrofit kits (like those from Taranis) have slashed the cost of autonomous tractors by letting farmers upgrade incrementally.
- Labor shortages are the ultimate catalyst. The self-driving tractor price became irrelevant when farms faced a choice: pay more for workers or invest in machines that didn’t need them.
- Trust is earned, not sold. The most successful adopters paired autonomy with human oversight—never a full replacement.
Where Things Stand Today
In 2024, the self-driving tractor price is no longer a monolith. At the high end, Case IH’s Autonomous Concept Combine—capable of full-field operations with minimal human input—still commands figures around the $1 million mark, but only for farms with 5,000+ acres. The sweet spot now lies in the mid-tier: semi-autonomous models from Deere, AGCO, and newer players like Kinze, which offer self-driving tractor pricing starting at $150,000 for basic autosteer plus AI-assisted planting. The real disruption is coming from the low end, where companies like Israel’s Taranis offer conversion kits for $20,000–$50,000, turning a conventional tractor into a semi-autonomous unit overnight. The catch? The cost of autonomous tractors is only part of the equation. Farmers still grapple with insurance premiums that can double for autonomous equipment, and regulatory landscapes vary wildly. In the U.S., most states require a licensed operator to be "on call" during autonomous operations, while the EU’s Machinery Directive allows full autonomy under certain conditions. The result is a fragmented market where the self-driving tractor price you pay depends as much on where you farm as on what you buy.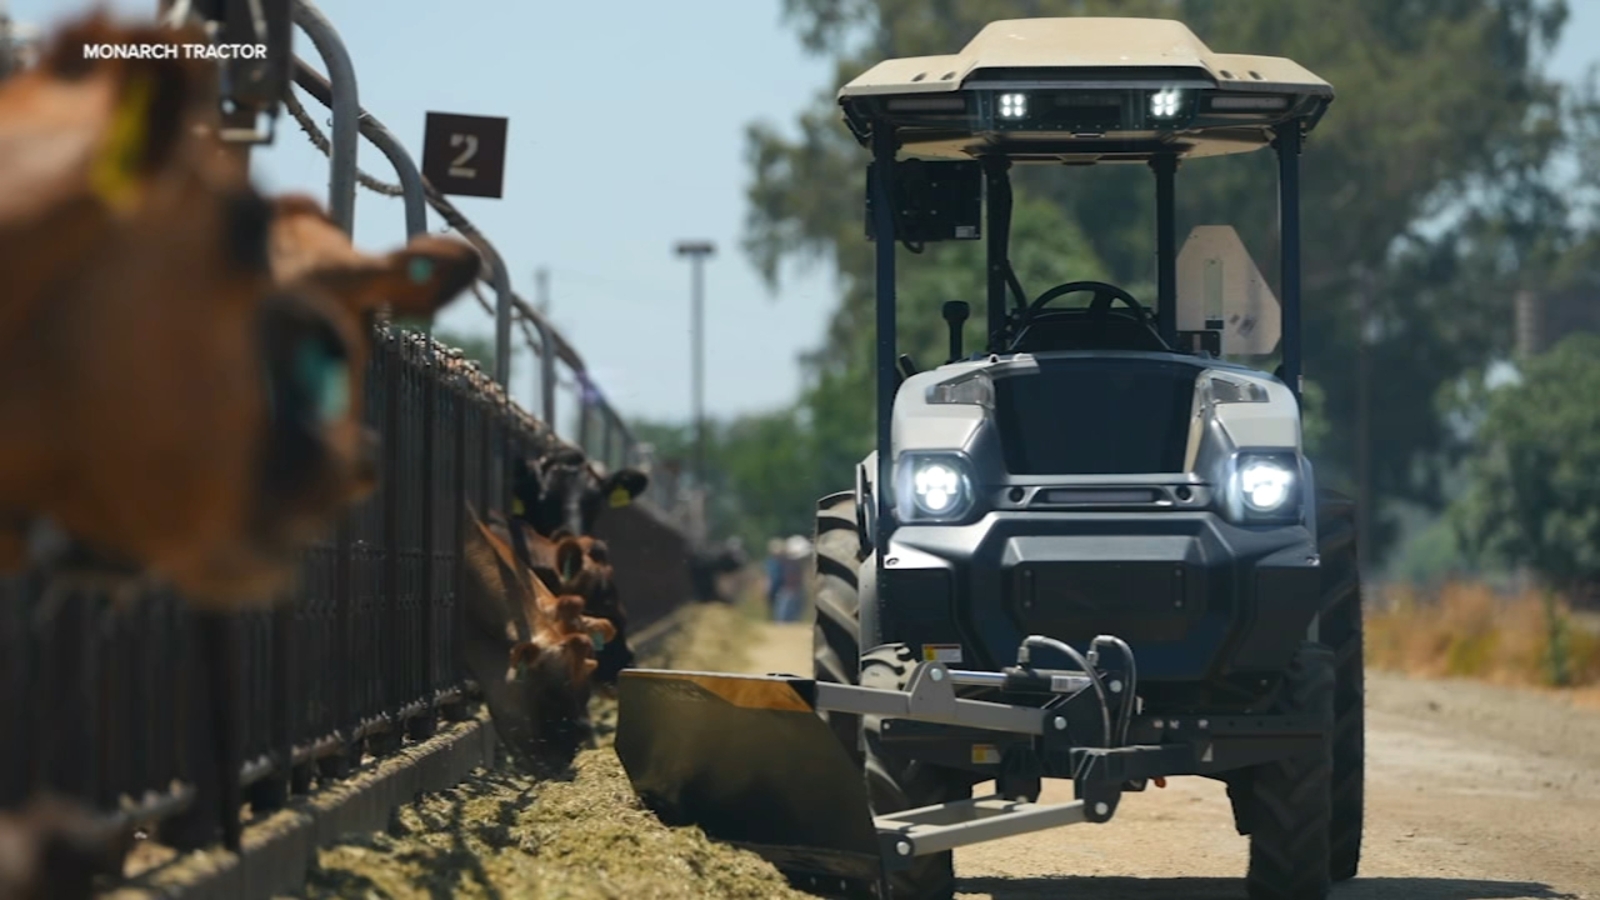
Conclusion
The arc of autonomous farming isn’t about replacing farmers—it’s about redefining what their work looks like. The self-driving tractor price has dropped to the point where even mid-sized operations can experiment, but the real story is in the data. Every autonomous pass through a field generates terabytes of insights, from soil moisture to pest migration patterns. The machines aren’t just cheaper labor; they’re partners in a new kind of agriculture. Yet for all the progress, the industry still faces a fundamental question: Can the price of self-driving tractors keep falling fast enough to outpace the climate and labor crises bearing down on global food systems? The answer may lie in the margins. The farmers who’ll thrive in the next decade won’t be the ones with the deepest pockets or the fanciest tech—they’ll be the ones who treat autonomy as a tool, not a replacement. And that starts with understanding the self-driving tractor price not as a sticker shock, but as an investment in resilience.Comprehensive FAQs
Q: What’s the average self-driving tractor price in 2024?
The range is wide: basic autosteer systems start at $20,000–$50,000, while fully autonomous combines can exceed $1 million. Mid-tier models (e.g., John Deere’s autonomous seeders) typically land between $150,000–$300,000. Leasing options have made entry far more accessible.
Q: Are there subsidies or grants to offset the cost of autonomous tractors?
Yes, but availability varies by region. The EU’s Common Agricultural Policy offers grants for "digital farming" investments, while Australia’s Rural R&D for Profit program covers up to 50% of autonomous equipment costs. In the U.S., state-level programs (e.g., California’s Healthy Soils Program) sometimes include autonomy incentives, but federal support remains limited.
Q: Can I retrofit an old tractor to be semi-autonomous?
Absolutely. Companies like Taranis (Israel) and Blue River (now owned by Deere) sell conversion kits that add autosteer, computer vision, and basic AI to conventional tractors. The price of self-driving tractor retrofits starts around $20,000, making it a cost-effective entry point for smaller farms.
Q: Do I need special insurance for autonomous tractors?
In most cases, yes. Policies must account for liability if the system fails, and some insurers require additional training for operators. Premiums can increase by 30–100% depending on the level of autonomy. Always check with your provider before purchasing—some, like FM Global, offer specialized coverage for precision agriculture.
Q: What’s the biggest misconception about self-driving tractor pricing?
The assumption that the sticker price is the only cost. Many farmers underestimate the need for upgraded infrastructure (e.g., high-speed internet in fields) and ongoing software updates. The price of autonomous tractors also includes hidden expenses like cybersecurity measures to protect against hacking risks.
Q: Are there any fully autonomous tractors under $100,000?
Not yet, but the gap is closing. Some Chinese manufacturers (e.g., XAG) offer semi-autonomous models in the $80,000–$100,000 range, though they may require manual intervention for complex tasks. For true full autonomy under $100K, you’ll likely need to wait until modular AI systems mature further.
Q: How do I know if my farm is ready for autonomous tractors?
Assess three things: 1) Field conditions (e.g., GPS signal strength, terrain variability), 2) existing equipment compatibility, and 3) your team’s willingness to adopt new workflows. Start with a pilot program—many dealers offer rentals or short-term leases to test the waters before committing to the self-driving tractor price.
