The Complete Overview of How Much Currency Is in Circulation in the US
The U.S. dollar’s physical presence is a paradox. On one hand, it’s the world’s reserve currency, with trillions in circulation across continents. On the other, domestic cash usage has plummeted—contactless payments now account for over 60% of transactions in major cities. This tension defines the modern dollar supply: a global asset with a shrinking role in its home economy. The Federal Reserve’s Currency in Circulation report, released quarterly, tracks this duality by measuring two key metrics: the total value of notes and coins outside Federal Reserve vaults, and the number of banknotes in circulation. As of mid-2024, the total value of U.S. currency in circulation hovers around $2.3 trillion, with roughly 15.4 billion banknotes active—each with an average lifespan of about 5.8 years before being replaced. What drives these numbers? The answer lies in three interlocking forces: demand elasticity, policy intervention, and structural shifts. Demand elasticity means the Fed doesn’t set a target for cash supply—it responds to market needs. When panic buying spikes (as in 2020), or when remittances to Latin America surge, banks order more cash from the Fed’s regional branches. Policy intervention comes into play during crises, like the 2008 financial meltdown, when the Fed injected billions in liquidity to stabilize markets. Structural shifts, meanwhile, reflect the rise of digital payments: while Venmo and Zelle dominate urban transactions, cash remains king in sectors like real estate, healthcare, and informal economies. The result? A currency system that’s simultaneously globalized and localized, with circulation patterns dictated by everything from cryptocurrency adoption to the Fed’s interest rate decisions.Historical Background and Evolution
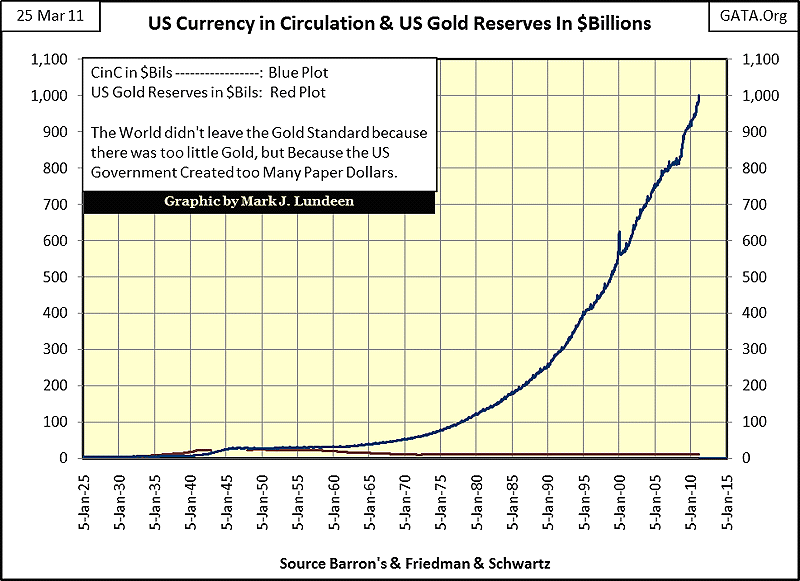
The story of how much currency is in circulation in the US begins not in the 20th century, but in the 1860s, when the National Banking Acts standardized banknote issuance. Before then, private banks printed their own money—leading to wild inflation and counterfeiting. The Fed’s creation in 1913 centralized control, but it wasn’t until the 1960s that the U.S. abandoned the gold standard, allowing the money supply to expand based on economic needs rather than commodity backing. This shift coincided with the rise of the dollar as the world’s primary reserve currency, a role cemented by the Bretton Woods Agreement in 1944. By the 1970s, how much currency was in circulation in the US was no longer just a domestic concern—it was a global one, as foreign central banks began hoarding dollars to back their own currencies. The 1980s and 1990s saw two critical developments. First, the Fed introduced M1 and M2 metrics to measure money supply, separating physical cash (M1) from broader liquidity (M2, including savings accounts). Second, technological change accelerated: ATMs debuted in the late 1960s, and by the 1990s, electronic payments were cutting into cash’s dominance. Yet the 2000s proved cash wasn’t obsolete. The Great Recession of 2008 led to a 30% increase in U.S. currency in circulation as households and businesses hoarded liquidity. Simultaneously, the Fed’s Quantitative Easing (QE) programs—where it purchased trillions in bonds—indirectly boosted the cash supply by keeping interest rates low and encouraging banks to lend more. Today, the Fed’s balance sheet remains bloated, with over $4.5 trillion in assets, though the link between that and physical currency circulation is indirect.Core Mechanisms: How It Works
The Fed doesn’t print money willy-nilly—it responds to demand through a decentralized distribution network. When a bank needs more cash (say, to restock ATMs or meet customer withdrawals), it submits an order to the Fed’s regional branch. The Fed then ships currency bundles—packets of $10,000 in $100 bills, for example—via armored trucks or commercial carriers. These bundles are tracked via serial numbers, and the Fed uses this data to monitor circulation patterns. If too much cash leaks into underground economies (like drug trafficking or tax evasion), the Fed can adjust supply or work with law enforcement to trace suspicious batches. What happens when cash is destroyed? The Fed’s Currency Production Office in Fort Worth, Texas, processes worn or damaged bills, shredding those beyond repair and recycling the paper. In 2023, the Fed destroyed over $1.5 billion in damaged currency—a fraction of the total supply but a critical part of maintaining trust. The system is designed for resilience: even if a single banknote’s lifespan is short, the total currency in circulation in the US remains stable because banks continuously replace worn-out bills. Meanwhile, the Fed’s Currency Education Program ensures the public knows how to spot counterfeit notes—a growing concern as digital printing technology improves.Key Benefits and Crucial Impact
Understanding how much currency is in circulation in the US isn’t just academic—it’s a window into economic stability. Cash provides a backstop for financial systems, especially during crises like power outages or cyberattacks that disrupt digital payments. When the 2021 Texas freeze knocked out payment processors, ATMs ran dry, and cash became the only reliable medium. Similarly, in countries with volatile currencies (like Venezuela or Argentina), U.S. dollars—whether physical or digital—serve as a hedge against inflation. Domestically, cash supports financial inclusion: the unbanked rely on it for everyday transactions, and small businesses in rural areas often prefer cash over card fees. Yet the benefits aren’t uniform. The Fed’s data shows that how much currency circulates in the US is heavily skewed by geography and demographics. Urban areas see faster turnover, while rural regions hoard cash longer. This disparity can create inefficiencies—banks in cash-rich areas may struggle with surplus inventory, while others face shortages. The Fed mitigates this through its Cash Product Office, which redistributes excess currency from high-demand regions to low-demand ones. Still, the system isn’t perfect. During the COVID-19 pandemic, some banks faced $50 million in cash shortages as demand surged for stimulus checks and small business loans."Cash is the ultimate equalizer—it doesn’t require a bank account, an internet connection, or even a name. But as digital payments grow, we risk creating a two-tiered economy where those without access to technology are left behind." — Federal Reserve Board Governor Michelle Bowman, 2023
Major Advantages
- Financial resilience: Cash operates independently of banks or power grids, making it critical during emergencies.
- Global trust anchor: The dollar’s physical form reinforces its role as the world’s reserve currency, used in trade and reserves.
- Privacy protection: Transactions in cash leave no digital trail, appealing to consumers concerned about data security.
- Low-cost transactions: No interchange fees or merchant processing costs, benefiting small businesses and low-income households.
- Countercyclical tool: During recessions, cash demand rises as consumers and businesses hoard liquidity, stabilizing spending.
- Anti-fragility: Even in extreme scenarios (e.g., a cyberattack on payment systems), cash remains functional.

Comparative Analysis
| Metric | U.S. Currency in Circulation (2024) | Eurozone (2024) |
|---|---|---|
| Total value in circulation | $2.3 trillion (Fed data) | €1.4 trillion (ECB data) |
| Banknotes per capita | ~70 notes per person | ~50 notes per person |
| Share held abroad | ~40% (Fed estimates) | ~20% (ECB estimates) |
Future Trends and Innovations
The next decade will likely see how much currency is in circulation in the US continue its slow decline, but not disappear entirely. The Fed’s own research suggests cash usage could drop to 20% of transactions by 2030, with the biggest declines in urban areas. Yet cash isn’t going extinct—it’s evolving. Smart cash (banknotes embedded with NFC chips for contactless payments) is being tested in pilot programs, while programmable money (digital cash with expiration dates or usage restrictions) could emerge as a tool for social welfare. The Fed’s FedNow instant payment system, launched in 2023, is already competing with cash for small-value transactions, with adoption growing among credit unions. Globally, the trend toward digital currencies—whether central bank digital currencies (CBDCs) or private stablecoins—will pressure physical cash. China’s digital yuan, for instance, has processed over $15 billion in transactions since its 2020 pilot, offering a model for how governments might phase out paper money. In the U.S., however, resistance remains strong: 60% of Americans still prefer cash for at least some transactions, according to a 2023 Pew Research survey. The Fed’s stance is pragmatic: it won’t eliminate cash, but it will continue shrinking its production as demand wanes. The question isn’t if cash will decline, but how quickly—and whether the U.S. will follow Europe’s gradual approach or adopt a more aggressive digital-first strategy.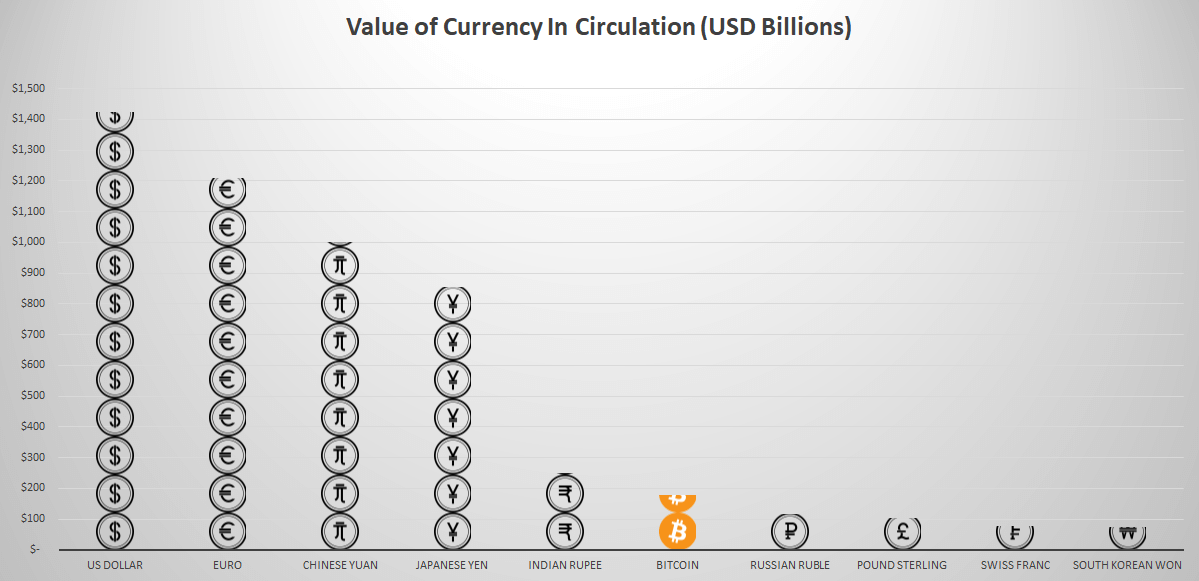
Conclusion
The amount of currency in circulation in the US is more than a number—it’s a reflection of economic behavior, technological change, and geopolitical power. While digital payments dominate headlines, cash remains a vital tool for millions, from the unbanked to global traders. The Fed’s role in managing this supply is subtle but profound: by adjusting circulation in response to crises, it helps stabilize markets without direct intervention. Yet the system isn’t static. As CBDCs and private digital currencies gain traction, the balance between physical and digital money will shift, forcing policymakers to rethink what money itself should look like. One thing is certain: the dollar’s physical form won’t vanish overnight. But its relevance will depend on whether it can adapt—whether through smart cash, hybrid payment systems, or a new social contract around financial inclusion. For now, the trillions in circulation tell a story of resilience. The challenge ahead is ensuring that story doesn’t become one of obsolescence.Comprehensive FAQs
Q: How does the Fed decide how much currency to print?
The Fed doesn’t set a target for printing—it responds to demand. Banks order cash from the Fed when their reserves run low, and the Fed ships it via armored carriers. The total supply adjusts based on withdrawals, destruction of damaged bills, and global demand (e.g., foreign central banks holding dollars). The Fed also monitors circulation data to detect anomalies, like sudden spikes that might indicate illegal activity.
Q: Why does the U.S. have so much currency abroad?
About 40% of U.S. currency is held outside the country, primarily in Latin America, Asia, and the Middle East. This reflects the dollar’s role as the world’s reserve currency: businesses and governments use it for trade settlements, debt payments, and as a hedge against local inflation. Remittances (e.g., Mexican workers sending money home) also drive demand. The Fed has no control over this—it’s a market-driven phenomenon.
Q: Can the Fed just print more money to fix economic problems?
No. While the Fed can increase the money supply (e.g., via QE), doing so risks inflation if demand outstrips production. The Fed’s mandate is price stability, so it balances liquidity needs with inflation risks. Printing money without economic growth leads to devaluation—as seen in Zimbabwe or Venezuela. The U.S. system is designed to prevent this by tying money creation to real activity, not political whims.
Q: How does cash circulation affect inflation?
More cash in circulation doesn’t directly cause inflation, but it can contribute if the economy isn’t growing fast enough to absorb it. For example, during the pandemic, stimulus checks and low interest rates led to record cash holdings, but inflation only spiked when supply chains broke down. The Fed watches velocity of money (how quickly cash changes hands)—if it slows, excess liquidity can fuel price increases. That’s why the Fed now focuses on digital liquidity (e.g., bank reserves) as much as physical cash.
Q: What happens to old or damaged U.S. currency?
The Fed’s Currency Production Office in Fort Worth processes worn bills. Notes with minor damage (e.g., tears, stains) are replaced by banks, while severely damaged ones are shredded. The Fed recycles the paper into new banknotes or other products. Counterfeit bills are tracked via serial numbers and removed from circulation. In 2023, the Fed destroyed over $1.5 billion in damaged currency—a small fraction of the total supply but critical for maintaining trust.
Q: Will the U.S. ever go cashless?
Unlikely in the near term. While digital payments are rising, 60% of Americans still use cash regularly, per Pew Research. The Fed has no plans to eliminate it, citing financial inclusion and emergency resilience. However, the trend is clear: cash usage is declining fastest among younger, urban populations. The Fed is exploring hybrid solutions, like smart cash or CBDCs, but a full phase-out would require major legislative and cultural shifts.
Q: How does the Fed track counterfeit money?
The Fed uses serial number tracking, color-shifting ink, and microprinting to detect fakes. Banks submit suspicious notes to the Secret Service, which investigates counterfeiting rings. The Fed also works with law enforcement to trace large volumes of counterfeit cash, often linked to organized crime. In 2023, counterfeit bills made up 0.02% of all currency in circulation—a small but persistent problem.
Q: Does the amount of currency in circulation affect interest rates?
Indirectly. If too much cash is circulating without economic growth, it can depress interest rates (since lenders have excess liquidity). Conversely, if cash is scarce, rates may rise as banks compete for deposits. The Fed’s monetary policy now focuses more on digital reserves (e.g., bank deposits at the Fed) than physical cash, but the two are linked—excess cash can spill into digital markets, influencing rates.
