The Short Answers
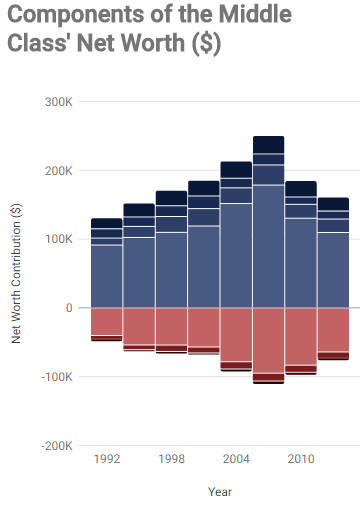
- The median middle class net worth in 2017 for households earning $50K–$150K was about $120,000, down from pre-2008 levels when adjusted for inflation.
- Regional differences were extreme: coastal middle-class families often held 30–50% less net worth than peers in lower-cost states due to housing costs.
- Homeownership remained the single largest driver of middle-class wealth, but recovery from the 2008 crash left many families with negative equity.
- Policy shifts in 2017—like the Tax Cuts and Jobs Act—primarily benefited the top 20%, widening the gap with stagnant middle-class assets.

Deep Dive: The Full Picture
The 2017 Federal Reserve data wasn’t just a snapshot—it was a Rorschach test for America’s economic health. When broken down, the middle class net worth 2017 figures exposed how wealth accumulation had become a zero-sum game. For the top 10%, net worth had surged by 40% since 2013, while the bottom 50% saw gains of just 2%. The middle—families earning between $50,000 and $150,000—had been left in the middle of nowhere. Their median net worth of $120,000 included a mix of home equity, retirement accounts, and liquid savings, but the latter two categories were often anemic. Many middle-class families had less than $5,000 in emergency savings, leaving them vulnerable to even minor financial shocks. What the data failed to capture was the psychological weight of these numbers. A $120,000 net worth sounds substantial until you realize it’s spread across a mortgage, student loans, and a 401(k) that’s barely growing. For families in their 40s and 50s, the 2017 figures were a gut punch: they’d worked through the Great Recession, only to find their financial security had eroded. The middle class net worth 2017 wasn’t just a statistic—it was a measure of how far the American Dream had slipped for millions.The Context You Need
To understand the middle class net worth 2017 crisis, you had to look back—and forward. The 2008 financial collapse had gutted middle-class balance sheets, and by 2017, the recovery had yet to fully reach them. Home values had rebounded, but wages hadn’t kept pace. The median home price in 2017 was 30% higher than in 2012, yet the median income had only risen by 15%. This mismatch meant that even middle-class families who bought homes were often house-poor, with little left for savings or investments. The policy environment in 2017 didn’t help. The Tax Cuts and Jobs Act, passed late in the year, slashed corporate rates but offered limited relief to middle earners. The child tax credit expanded slightly, but the bulk of benefits flowed to higher-income households. Meanwhile, student debt—now $1.4 trillion nationally—had become a millennial albatross. For middle-class families with children, the middle class net worth 2017 figures were a ticking time bomb: how could they save for retirement when tuition payments and mortgage rates ate up their paychecks?The Mechanics
The mechanics of middle-class wealth in 2017 boiled down to three pillars: homeownership, retirement savings, and liquid assets. Homeownership was the linchpin. Families with mortgages saw their net worth rise as housing markets recovered, but those who’d lost homes in the crash were still rebuilding. The middle class net worth 2017 median for homeowners was $250,000, while renters averaged just $10,000. This disparity wasn’t just about housing—it was about generational wealth. Homeowners had a head start; renters were playing catch-up in a market where prices had outpaced incomes. Retirement accounts were the second weak link. The median 401(k) balance for middle-class families in 2017 was $25,000—enough to cover roughly six months of expenses if withdrawn. But most middle earners couldn’t afford to tap into retirement funds without penalty. Meanwhile, Social Security benefits—relied upon by nearly half of middle-class retirees—were being squeezed by inflation and political gridlock. The third leg, liquid savings, was the most fragile. Over 40% of middle-class families had less than three months’ worth of expenses saved. In a year where natural disasters and medical emergencies rose, this lack of cushion was a national vulnerability.Details That Change the Picture
The middle class net worth 2017 narrative shifted when you zoomed in on demographics. Age played a critical role: families headed by someone in their 30s had half the net worth of those in their 50s, thanks to decades of compounding home equity and retirement contributions. Race was another factor. White middle-class families held median net worth 13 times higher than Black families and 10 times higher than Hispanic families, a gap that persisted even when controlling for income. These weren’t just statistical anomalies—they were the result of systemic barriers in education, hiring, and lending. Then there was geography. In states like Texas or Ohio, middle-class families could buy a home and build equity without breaking the bank. But in California or Massachusetts, the middle class net worth 2017 median was dragged down by sky-high housing costs. A family earning $100,000 in San Francisco might have negative net worth after student loans and rent, while a similar earner in Indianapolis could own a home outright. The data revealed that middle-class wealth wasn’t just about income—it was about where you lived, who you were, and when you started."The middle class isn’t disappearing—it’s being hollowed out from the inside. The numbers in 2017 show that for every family that moves up, two are being held back by debt and stagnant wages." —Edward N. Wolff, Professor of Economics at NYU, 2017
| Metric | 2017 Middle Class Net Worth (Median) |
|---|---|
| Homeowners | $250,000 |
| Renters | $10,000 |
| Families with College Degrees | $180,000 |
Conclusion
The middle class net worth 2017 data wasn’t just a historical footnote—it was a warning. By 2017, the middle class had become a financial tightrope, with one wrong step sending families into debt or dependency. The stagnation in net worth wasn’t a temporary blip; it was the new normal for millions. Policy responses—from wage stagnation to healthcare costs—had failed to address the root issue: how to build wealth when the cost of living outpaced earnings. The 2017 figures weren’t just about money; they were about who gets to participate in the economy’s upside. What happened next would determine whether the middle class could recover—or if the middle class net worth 2017 crisis became a permanent feature of the American landscape. The data suggested that without structural changes—better wages, affordable housing, and debt relief—the gap would only widen. For now, the numbers spoke for themselves: the middle class wasn’t just holding on. It was barely hanging on.Comprehensive FAQs
Q: How did the 2017 tax law affect middle-class net worth?
The Tax Cuts and Jobs Act of 2017 primarily benefited higher-income households through reduced capital gains taxes and corporate rate cuts. Middle-class families saw modest increases in child tax credits, but the overall impact on middle class net worth was minimal—most gains went to the top 20%. The law also reduced deductions for state and local taxes, hitting homeowners in high-tax states hardest.
Q: Were there any bright spots in middle-class net worth in 2017?
Yes, but they were narrow. Families with strong home equity in recovering markets saw net worth rise, and those with employer-sponsored retirement plans benefited from market gains. However, these gains were offset by rising healthcare costs and stagnant wage growth. The brightest spot was among younger middle-class families who avoided the worst of the 2008 crash and could start building wealth early.
Q: How did student debt impact middle-class net worth in 2017?
Student debt was a major drag on middle-class net worth. In 2017, borrowers under 40 held $1 trillion in student loans, suppressing homeownership and retirement savings. Middle-class families with degrees had higher net worth than peers without, but the debt burden meant many were asset-poor despite higher incomes. The Fed’s data showed that student loan balances had grown faster than incomes for middle earners.
Q: Did regional differences in net worth persist in 2017?
Absolutely. Middle-class families in low-cost states like Iowa or Nebraska had net worth 2–3 times higher than peers in California or New York due to housing costs. Even within states, urban vs. suburban divides existed—suburban families often had better school districts and lower property taxes, boosting long-term wealth. The middle class net worth 2017 median was a national average masking deep regional fractures.
Q: How did homeownership rates affect middle-class net worth?
Homeownership was the single biggest driver of middle-class wealth. In 2017, middle-class homeowners had net worth 25 times higher than renters. The recovery from the 2008 crash had helped, but many families still faced negative equity or underwater mortgages. For those who owned, home equity accounted for 70% of their net worth—but for renters, the figure was near zero.
Q: Were there generational differences in middle-class net worth?
Yes, sharply. Families headed by someone under 35 had median net worth of $50,000, while those headed by someone 55–64 had $200,000. The gap reflected decades of home equity accumulation and retirement savings. Younger middle-class families in 2017 were also burdened by student debt, which older generations lacked. This divide threatened to perpetuate wealth inequality across generations.
Q: How did healthcare costs factor into middle-class net worth?
Healthcare was a silent wealth destroyer. In 2017, middle-class families spent 18% of their income on healthcare—up from 12% in the 1990s. High deductibles and out-of-pocket costs forced many to dip into savings or take on debt, eroding net worth. The lack of employer-sponsored coverage for part-time workers (a growing segment of middle earners) made the problem worse. For families without emergency savings, a single medical event could wipe out years of financial progress.
Q: What policy changes could have improved middle-class net worth in 2017?
Several measures could have helped, but few were enacted. Wage growth tied to productivity, expanded Social Security benefits, and student debt relief would have directly boosted net worth. Affordable housing policies—like down payment assistance or zoning reforms—could have helped renters transition to homeownership. Even small changes, like automatic 401(k) enrollment, could have increased retirement savings. However, in 2017, policy debates focused more on tax cuts for the wealthy than structural fixes for the middle class.
