Where It All Began
The origins of the net worth of Michael Dell trace back to a single, unassuming moment in 1984, when Dell—then a pre-med student at the University of Texas—realized that the IBM PC’s success had created a gap in the market. While IBM sold standardized machines, businesses needed faster, more powerful systems tailored to their needs. Dell saw an opportunity: eliminate the middleman. Instead of relying on retailers or distributors, he would sell directly to customers, using mail orders and telemarketing to cut costs and pass savings on to buyers. The first product—a 14.77 MHz Turbo PC with 640KB of RAM—wasn’t revolutionary, but the model was. By 1985, Dell had dropped out of college, moved operations to a rented house, and hired his first employees. The company’s revenue that year: $6 million. What made Dell’s early strategy so effective wasn’t just the direct sales model, but the cash-flow discipline he instilled from the start. Unlike competitors that loaded up on inventory, Dell operated on a just-in-time principle: components were ordered only after a sale was secured. This kept capital tied up in inventory low and margins high. By 1987, Dell had expanded into Europe and Asia, and its revenue had surpassed $70 million. The company’s IPO in 1988 at $8.50 a share—later adjusted for splits—made Dell a millionaire before his 24th birthday. But the real inflection came in 1992, when Dell introduced the Dell Dimension, a line of preconfigured desktop PCs. It was a pivot from bespoke builds to mass-market appeal, and it worked. Revenue hit $1 billion in 1996, and Dell became the youngest CEO of a Fortune 500 company at the time.The Early Signs
Even in its infancy, Dell’s business acumen stood out. While other tech founders chased glamorous products or rapid scaling, Dell focused on operational efficiency. His obsession with supply chain optimization wasn’t just about cost savings; it was a competitive moat. By the early 1990s, Dell had built a reputation for aggressive pricing—undercutting IBM and Compaq while maintaining profitability. The company’s gross margins consistently hovered around 20%, a figure that would later be cited as a benchmark for the industry. Dell’s ability to turn inventory every 12 days—compared to competitors’ 45-day cycles—meant he could reinvest profits faster than anyone else. The early 1990s also saw Dell’s first foray into corporate branding. Unlike IBM, which relied on its blue-suited salesforce, Dell positioned itself as the anti-establishment tech company. His 1997 book, Direct from Dell, became a bestseller, blending business philosophy with memoir. The book’s central thesis—that companies should listen to customers and eliminate inefficiencies—wasn’t just marketing; it was the blueprint for Dell’s growth. By the time the dot-com bubble peaked in 2000, Dell Inc. was the third-largest PC vendor in the world, with a market cap of over $50 billion. Dell’s personal stake in the company, combined with his salary and stock options, put his net worth of Michael Dell in the billions. But the bubble’s collapse would force a reckoning.The Turning Point
The late 1990s and early 2000s were a period of brutal self-examination for Dell. The company’s stock, which had soared to $50 in 1999, fell below $10 by 2003. The issues were systemic: over-reliance on debt, a bloated supply chain, and a failure to adapt to changing consumer habits. Dell’s direct model, once a strength, became a weakness as competitors like HP and Lenovo caught up in customization. Worse, the rise of Apple’s Mac and the shift toward consumer-friendly retail made Dell’s no-frills approach seem outdated. By 2004, Dell’s market share had slipped, and the company was hemorrhaging cash. The question wasn’t whether Dell Inc. would survive—but whether Michael Dell would be the one to fix it. The turning point came in 2007, when Dell made a high-risk, high-reward decision: he took the company private in a $24.9 billion leveraged buyout. The move required him to sell nearly half his shares and borrow heavily, but the strategy was clear. Dell would strip the company of excess, refocus on core markets, and emerge leaner. Critics called it desperation; Dell called it a reset. The buyout didn’t just save the company—it transformed it. By 2013, Dell had merged with EMC, creating one of the largest tech firms in the world. The move diversified Dell’s revenue streams beyond PCs into data storage, cybersecurity, and enterprise software. What had once been a single-product play became a multi-billion-dollar conglomerate, and Dell’s personal fortune, tied to the company’s performance, began climbing again. > "The best way to predict the future is to create it." —Michael Dell, reflecting on the 2007 buyout decision.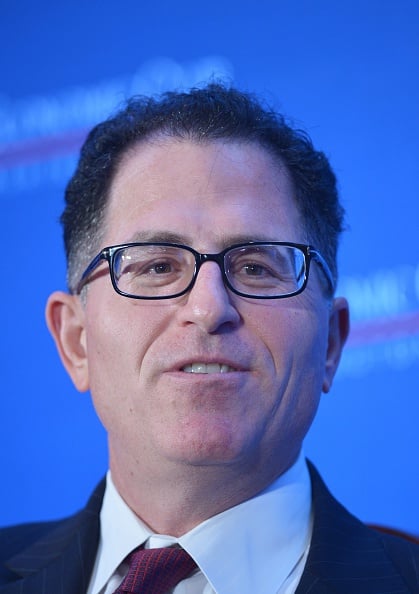
The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 1984–1987 | Dell founds PC’s Limited in a dorm room; revenue hits $6M by 1985. Moves to direct sales model, bypassing retailers. |
| 1988–1992 | IPO at $8.50/share; revenue surpasses $100M. Introduces Dimension line of preconfigured PCs, shifting from bespoke to mass-market. |
| 1996–2000 | Revenue hits $1B in 1996; becomes youngest Fortune 500 CEO. Dot-com bubble peaks, but Dell’s debt-fueled growth becomes a liability. |
| 2007–2013 | Takes Dell private in $24.9B buyout; merges with EMC in 2013, creating a diversified tech giant. |
Lessons From the Journey
- Cash is king. Dell’s early success hinged on inventory discipline—a principle he never abandoned. Even during the dot-com boom, he avoided overleveraging, a mistake many of his peers made.
- Direct-to-consumer isn’t always scalable. Dell’s model worked in the 1990s but faltered as competitors caught up. The 2007 buyout forced a pivot to enterprise and services.
- Mergers can be a lifeline. The EMC acquisition wasn’t just about size; it was about diversification. Dell’s fortune today is tied to data storage and cybersecurity, not just PCs.
- Reinvention is non-negotiable. Dell’s ability to pivot—from direct sales to enterprise IT—proves that stagnation is the real risk for even the most dominant brands.
- Personal branding matters. Dell’s books, interviews, and public persona kept him relevant long after the PC wars faded.
- Leverage wisely. The 2007 buyout was risky, but it allowed Dell to control his own destiny—something he couldn’t do as a public company.
Where Things Stand Today
As of recent estimates, the net worth of Michael Dell is tied closely to his stake in Dell Technologies, now a publicly traded entity again after its 2018 IPO. While exact figures fluctuate with stock performance, industry analysts place his personal fortune in the $30–40 billion range, making him one of the wealthiest tech entrepreneurs of his generation. But Dell’s wealth isn’t just about numbers; it’s about strategic control. Unlike many founders who sell out or lose influence, Dell remains deeply involved in the company’s direction. His focus has shifted from PCs to enterprise solutions, including AI-driven data storage and cybersecurity—areas where Dell Technologies is a major player. Beyond Dell Technologies, Michael Dell has diversified his investments. His MSD Capital private equity firm has stakes in companies like VMware, CrowdStrike, and DocuSign, further insulating his wealth from any single market downturn. He’s also a prominent philanthropist, with commitments to education and healthcare through the Michael & Susan Dell Foundation. Yet, for all his success, Dell remains grounded in the principles that built his fortune: operational efficiency, customer obsession, and a willingness to take calculated risks. The net worth of Michael Dell isn’t just a reflection of his business acumen—it’s a testament to his ability to adapt when others couldn’t.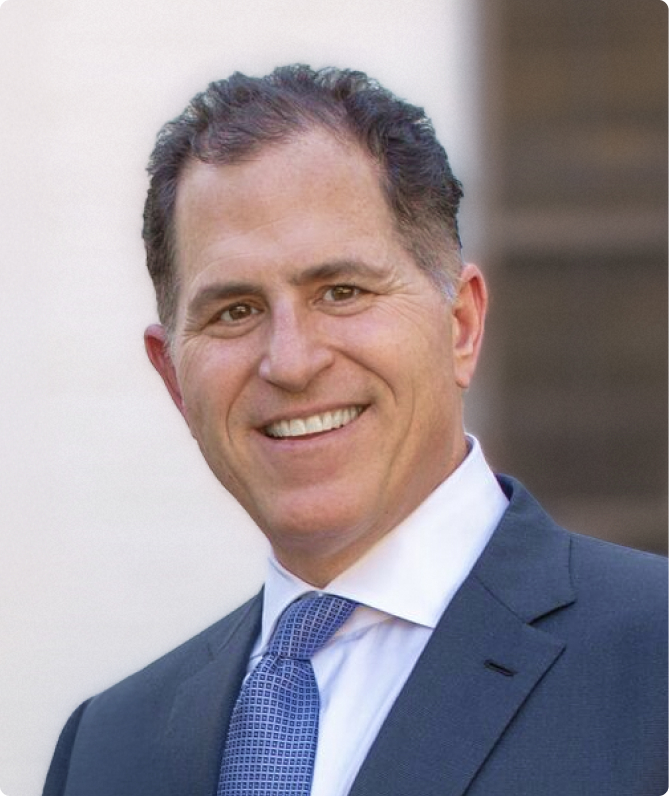
Conclusion
Michael Dell’s story is more than a rags-to-riches tale; it’s a masterclass in business resilience. From a dorm-room operation to a global tech conglomerate, his journey has been defined by three constants: an unwavering focus on cash flow, a willingness to disrupt his own business when necessary, and an ability to read market shifts before they become trends. The net worth of Michael Dell today is the result of these principles, but it’s also a reminder that fortunes are never static. Dell’s greatest asset has always been his adaptability—whether it was pivoting from PCs to enterprise IT or taking his company private to strip it of inefficiencies. What’s often overlooked in discussions about Dell’s wealth is the human element. Behind the balance sheets and stock ticker symbols is a founder who bet everything on his vision—and won. But success hasn’t made him complacent. Whether through his foundation, his private equity investments, or his ongoing role at Dell Technologies, Dell continues to shape industries. For entrepreneurs and investors alike, his story is a case study in how to build, preserve, and grow wealth—not just in tech, but in any field where innovation meets discipline.Comprehensive FAQs
Q: How did Michael Dell first accumulate his wealth?
Dell’s wealth traces back to the direct sales model he pioneered in the 1980s. By selling PCs directly to businesses—cutting out retailers and distributors—he achieved higher margins and lower inventory costs. The company’s IPO in 1988 made him a millionaire, and by the late 1990s, his stake in Dell Inc. put him among the richest entrepreneurs of his generation.
Q: What was the biggest mistake in Dell’s early career?
The over-reliance on debt during the dot-com boom is often cited as a misstep. Dell’s aggressive expansion in the late 1990s led to high leverage, which became unsustainable when the bubble burst. This forced a strategic reset, including the 2007 buyout that took the company private.
Q: How did the 2007 buyout affect Michael Dell’s net worth?
The buyout was a high-risk move that required Dell to sell nearly half his shares and borrow heavily. While it temporarily reduced his personal stake, the strategy saved the company and set the stage for the EMC merger. Post-merger, his wealth rebounded as Dell Technologies’ valuation soared, putting his net worth of Michael Dell back in the stratosphere.
Q: What industries is Michael Dell invested in besides tech?
Beyond Dell Technologies, Dell has investments in private equity (MSD Capital), including stakes in cybersecurity (CrowdStrike), cloud computing (VMware), and healthcare tech. His philanthropic work through the Michael & Susan Dell Foundation also spans education and global health initiatives.
Q: Is Dell still involved in day-to-day operations at Dell Technologies?
While Dell has stepped back from the CEO role, he remains deeply involved as Chairman of the Board. His focus is on long-term strategy, particularly in AI, data storage, and enterprise solutions—areas where Dell Technologies is expanding.
Q: How does Michael Dell’s wealth compare to other tech founders?
As of recent estimates, Dell’s net worth of Michael Dell places him among the top 50 wealthiest people globally, alongside figures like Jeff Bezos and Larry Ellison. However, unlike many tech moguls who built fortunes on single products (e.g., Amazon, Oracle), Dell’s wealth is diversified across enterprise IT, private equity, and philanthropy.
Q: What’s the biggest lesson from Michael Dell’s career?
The most recurring theme in Dell’s success is adaptability. Whether it was pivoting from direct sales to enterprise IT or taking his company private to restructure it, Dell’s ability to reinvent his business model when faced with disruption has been the key to preserving—and growing—his wealth.
