
The Short Answers
- Memory loss from wreck net worth is linked to chronic financial stress, which studies show can impair executive function and memory retrieval.
- High-net-worth individuals often face accelerated cognitive decline when wealth volatility triggers anxiety, sleep deprivation, and poor decision-making.
- Legal protections like conservatorships may exacerbate memory issues by stripping autonomy, while financial advisors rarely screen for cognitive risks.
- Recovery depends on structured routines, professional support, and—critically—accepting that financial stability alone won’t reverse cognitive strain.
- Families of affected individuals report that the most damaging loss isn’t the money, but the erosion of trust in their loved one’s judgment.
- Preventative measures include diversifying cognitive health (e.g., mental exercises) alongside financial diversification.
Deep Dive: The Full Picture
The relationship between wealth and cognition has been studied for decades, but the focus has typically been on the privileges of affluence—better healthcare, education, or nutrition. What’s less examined is how the destruction of wealth acts as a cognitive disruptor. When a person’s net worth plummets, the brain’s reward centers, which once associated success with dopamine hits, now associate failure with cortisol spikes. This isn’t just stress; it’s a neurological recalibration. The prefrontal cortex, responsible for memory and impulse control, becomes overloaded with financial anxiety, while the hippocampus—critical for long-term memory—shrinks under chronic stress. The result? A person who once managed complex portfolios may now forget appointments or struggle to follow conversations about investments they once dominated. The psychological toll compounds when external factors intervene. Lawsuits, divorces, or business fraud can accelerate the decline. A 2021 study in the Journal of Alzheimer’s Disease found that individuals with sudden wealth loss exhibited memory retrieval deficits similar to early-stage dementia patients, though the causes differed. The key distinction: financial trauma-induced memory loss is often reversible with intervention, whereas neurodegenerative conditions are not. Yet, the stigma around discussing cognitive struggles in high-net-worth circles means many suffer in silence. Advisors, family members, and even doctors may dismiss forgetfulness as a temporary side effect of financial setbacks, delaying critical support.The Context You Need
Memory loss from wreck net worth isn’t a uniform experience. It manifests differently across demographics. For example, a 40-year-old tech entrepreneur who built a unicorn startup may experience episodic memory lapses—forgetting meetings, misplacing documents, or blanking on the names of early investors—while a 70-year-old retiree whose pension vanished due to market crashes might struggle with semantic memory, losing track of basic financial concepts like inflation or compound interest. The common thread? Both groups face a double jeopardy: their cognitive decline is often attributed to aging or "burnout," rather than the financial upheaval itself. The legal system further complicates matters. Courts rarely consider cognitive impairment when ruling on financial disputes, even when it’s clear that a person’s judgment is compromised. A prime example is the case of a former Hollywood producer whose memory loss from wreck net worth—stemming from a failed film project that bankrupted him—led to a conservatorship. His family argued that his cognitive decline was a direct result of financial stress, but the court treated it as a standalone medical issue. This disconnect highlights a broader failure: financial and cognitive health are treated as separate domains, when in reality, they’re intertwined.The Mechanics
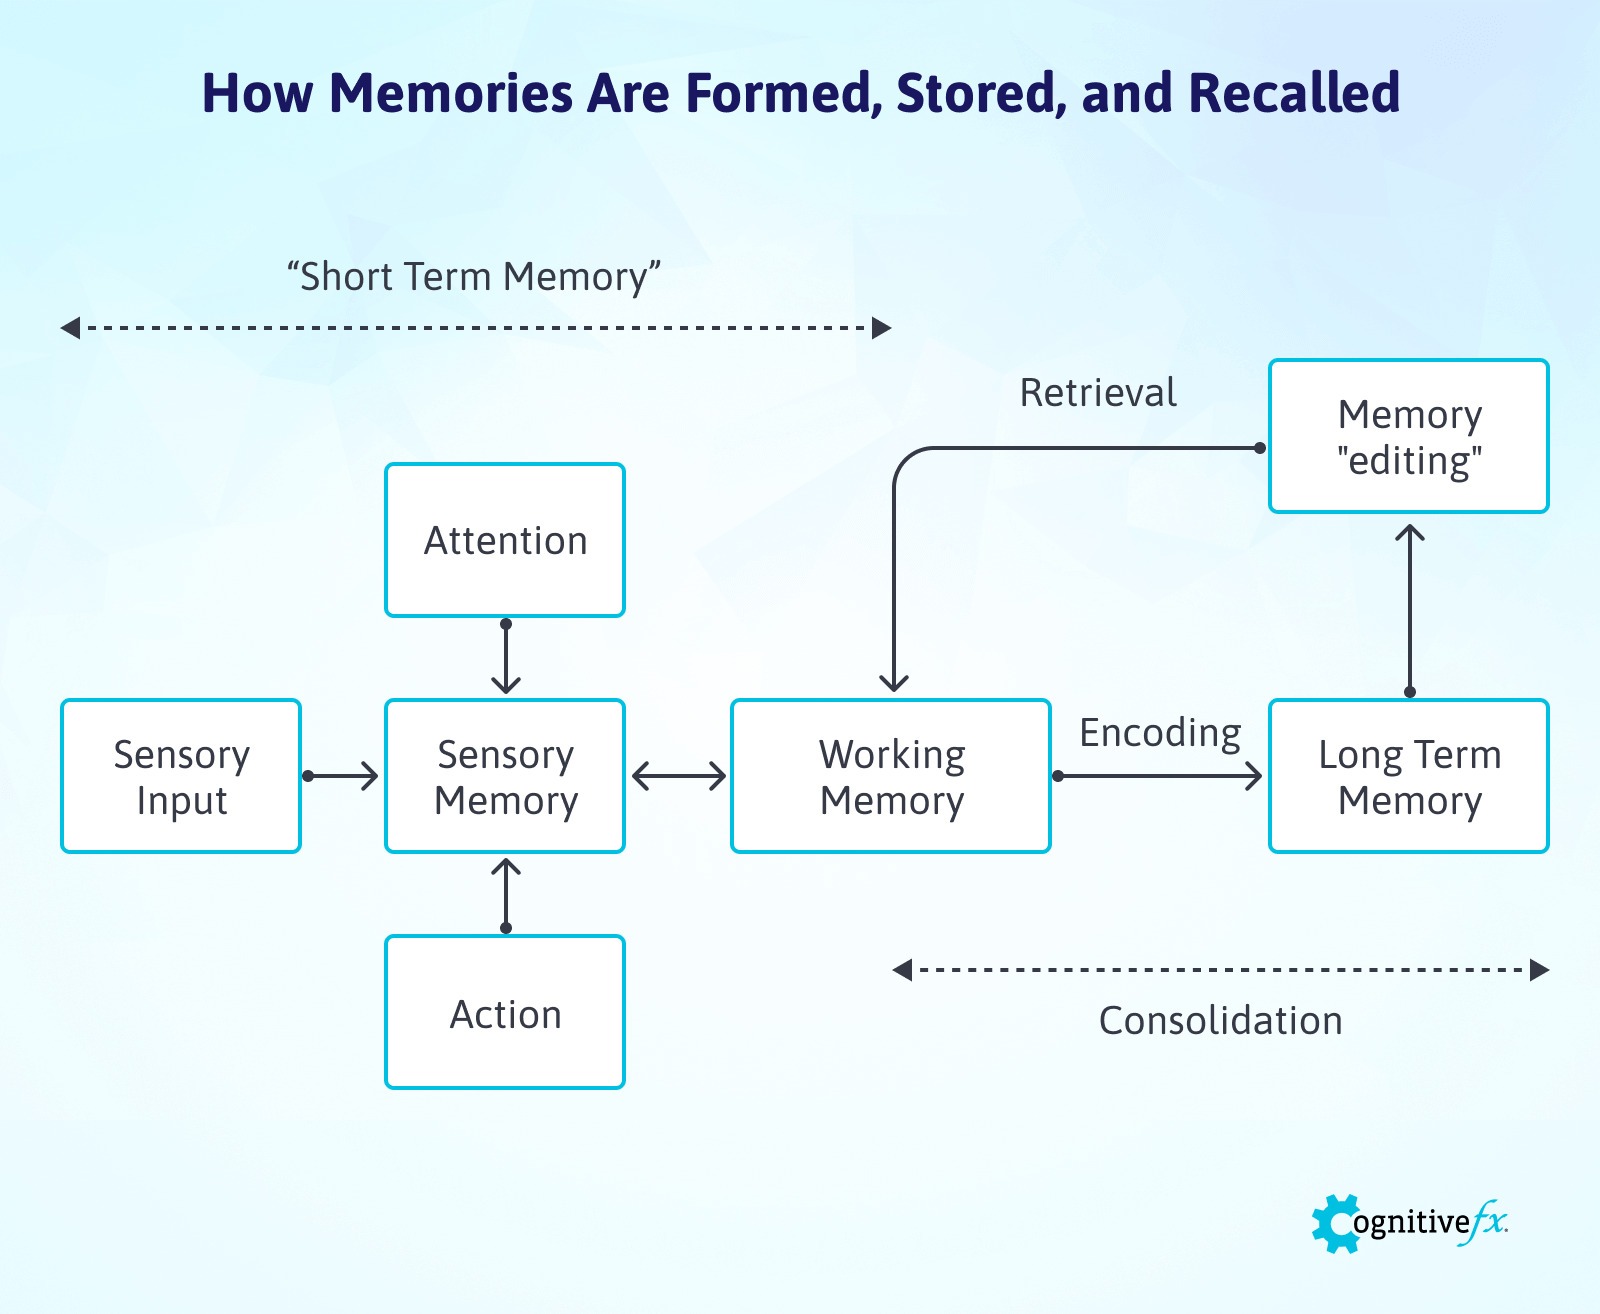
The brain’s response to financial ruin follows a predictable pattern. Initially, the amygdala—the brain’s alarm system—overactivates, flooding the system with stress hormones. Prolonged exposure to these hormones damages the hippocampus, impairing memory consolidation. Meanwhile, the prefrontal cortex, which handles working memory and decision-making, becomes cognitively exhausted from the constant need to problem-solve in a volatile financial environment. Over time, this creates a vicious cycle: poor financial decisions lead to more stress, which worsens cognitive function, which then leads to even poorer decisions. Research in neuroeconomics suggests that individuals with fluctuating net worth often develop cognitive rigidity—an inability to adapt to new information. This isn’t laziness; it’s a survival mechanism. The brain, under duress, defaults to familiar patterns, even if they’re harmful. For instance, a person who once diversified investments might revert to risky bets in an attempt to recoup losses, despite past failures. The memory of past successes becomes distorted, replaced by a reconstructed narrative that justifies reckless behavior. This phenomenon explains why some high-net-worth individuals cycle through repeated financial disasters: their memory of past mistakes is either suppressed or rewritten.Details That Change the Picture
The most underreported aspect of memory loss from wreck net worth is its intergenerational impact. Children of financially ruined parents often inherit not just debts but the emotional and cognitive fallout. Studies on "financial legacy trauma" show that offspring may develop anticipatory anxiety—a fear of repeating their parents’ mistakes—while also absorbing their cognitive habits. For example, a parent who once managed a multimillion-dollar portfolio but now forgets how to balance a budget may pass down a distorted financial identity to their children, who then either overcompensate with obsessive control or disengage entirely. Another critical factor is the role of social capital. High-net-worth individuals often rely on networks of advisors, peers, and mentors to maintain their cognitive edge. When wealth declines, these networks can evaporate, leaving the individual isolated. The loss of social engagement—whether through networking events, board meetings, or even casual financial discussions—accelerates cognitive decline. This is why some affected individuals report feeling "invisible" in professional circles, even if their skills remain intact. The brain, it turns out, thrives on reciprocal engagement, and financial ruin can sever those connections."You don’t realize how much of your memory is tied to your money until it’s gone. I used to know every line of every contract I signed. Now? I forget where I put my keys—and my will." —Anonymous former hedge fund manager, interviewed post-conservatorship
| Symptom | Likely Cause |
|---|---|
| Forgetting names of long-time business partners | Hippocampal shrinkage from chronic stress |
| Repeatedly signing documents without recalling details | Prefrontal cortex overload from financial anxiety |
| Misplacing critical financial documents | Working memory deficits due to sleep deprivation |
| Relying on scripts for conversations about past successes | Semantic memory degradation from identity crisis |
| Difficulty following multi-step financial plans | Executive function impairment from cognitive rigidity |

Conclusion
Memory loss from wreck net worth is more than a footnote in the story of financial ruin. It’s a silent epidemic among those who once commanded both wealth and mental clarity. The failure to address it stems from a cultural bias: we romanticize the "self-made" narrative but ignore the human cost when the system fails. The solution isn’t just better financial planning—it’s recognizing that cognitive health and wealth management are two sides of the same coin. Early intervention, whether through cognitive behavioral therapy, structured financial routines, or legal protections that account for mental decline, could mitigate the damage. Yet, the stigma persists. Admitting that memory loss from wreck net worth is real risks undermining the myth of invincibility that surrounds success. For those affected, the path forward isn’t about rebuilding net worth alone—it’s about reclaiming the narrative of their own minds. The first step? Acknowledging that the brain, like any asset, requires maintenance—especially when the balance sheet is in freefall.Comprehensive FAQs
Q: Can memory loss from wreck net worth be reversed?
A: Partial reversal is possible with targeted interventions, such as cognitive therapy, stress management, and structured financial routines. However, prolonged financial trauma can cause lasting hippocampal damage, so early action is critical. Neuroplasticity means the brain can adapt, but the window for recovery narrows with time.
Q: Are there legal protections for individuals experiencing this?
A: Current legal frameworks are inadequate. Conservatorships exist but are often triggered too late, and courts rarely consider financial stress as a contributing factor to cognitive decline. Advocacy groups are pushing for "financial cognitive assessments" in estate planning, but adoption remains limited.
Q: How does this differ from early-onset dementia?
A: The primary difference is reversibility. Memory loss from wreck net worth is typically stress-induced and situational, whereas dementia involves progressive neurodegeneration. However, chronic financial stress can accelerate dementia risk, blurring the lines over time.
Q: What role do financial advisors play in mitigating this?
A: Most advisors focus on portfolio management, not cognitive health. The best practitioners now screen for financial anxiety and recommend cognitive resilience strategies, such as simplifying financial tasks or using memory aids. The field is still evolving, but awareness is growing.
Q: Can family members recognize the signs early?
A: Yes, but cultural taboos often delay action. Watch for patterned forgetfulness (e.g., missing payments, ignoring legal deadlines) combined with emotional withdrawal. Families should seek medical evaluations if financial behaviors become erratic, as this can signal cognitive strain before memory lapses become severe.
Q: Does memory loss from wreck net worth affect women differently?
A: Research suggests women may experience more pronounced semantic memory loss (e.g., forgetting financial terminology) due to societal conditioning that links their identity less directly to wealth. Men, conversely, may exhibit more executive dysfunction (e.g., impulsive financial decisions) as a coping mechanism. Gender roles shape how financial trauma manifests cognitively.
Q: Are there preventative measures for high-net-worth individuals?
A: Diversifying cognitive health is key. This includes regular mental exercises (e.g., chess, language learning), stress-reduction practices (e.g., mindfulness), and financial contingency planning that accounts for cognitive decline. Some ultra-high-net-worth individuals now include "cognitive trustee" clauses in estate documents to manage assets if mental capacity wanes.
Q: What’s the most damaging long-term effect?
A: The erosion of self-trust. When a person’s memory of their own competence fails, it creates a feedback loop of shame and avoidance. This is why recovery often requires rebuilding confidence in one’s judgment—long before the numbers are restored.
