Common Myths About Medical Insurance Net Worth
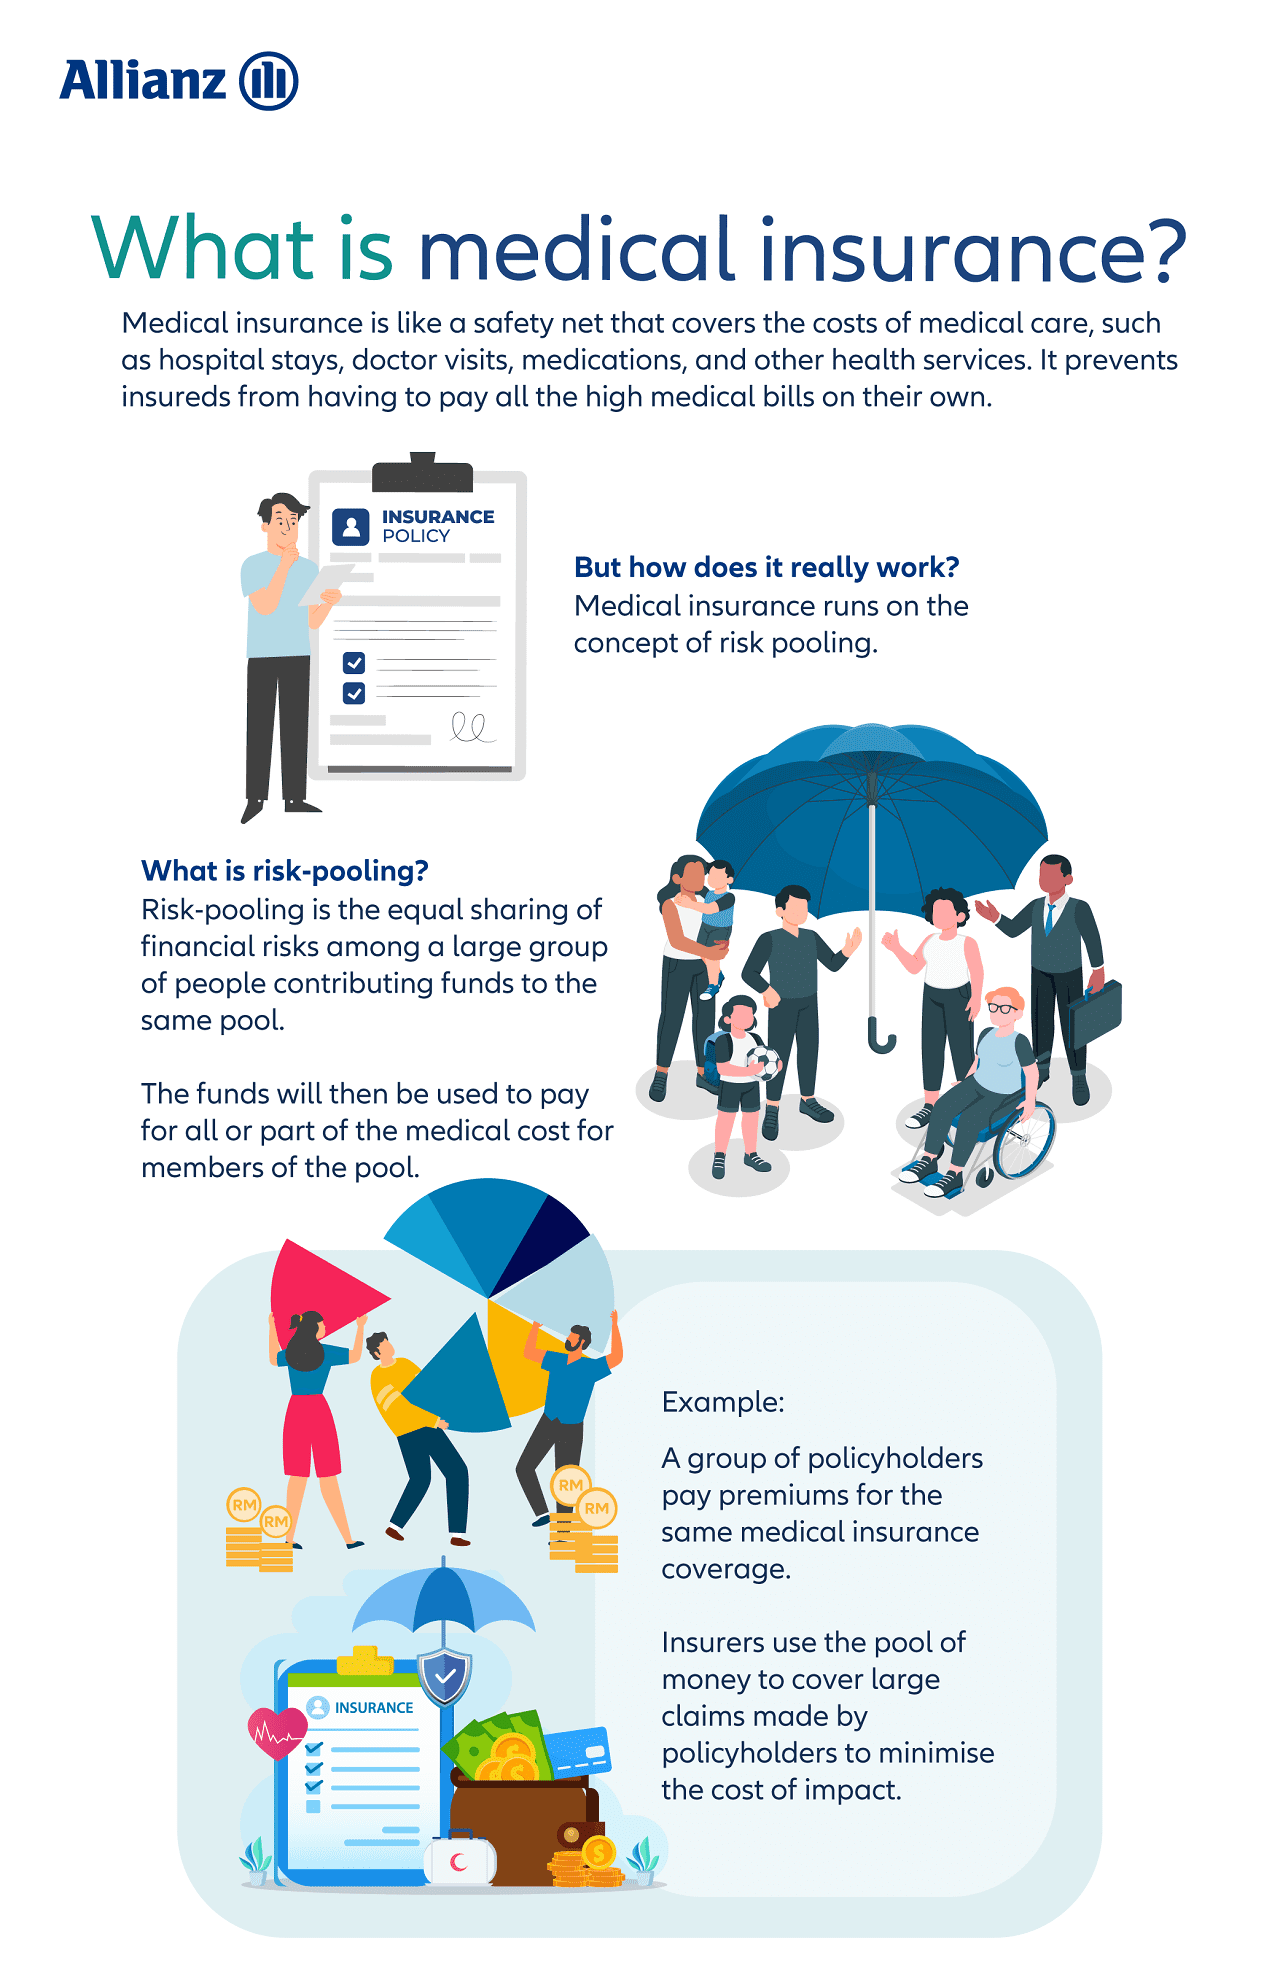
The first misconception is that medical insurance net worth is solely about the premium paid. In truth, it’s a three-legged stool: premiums, out-of-pocket maximums, and the opportunity cost of funds tied up in high-deductible plans. A policy that saves $500/month in premiums but requires a $15,000 deductible for a heart procedure may offer short-term relief—until the deductible triggers a liquidity crisis. The second myth is that employer-sponsored plans are sufficient. While these often cover 70-80% of costs, they rarely account for long-tail risks like chronic illness or catastrophic injuries, which can drain retirement savings faster than market downturns. Another persistent belief is that medical insurance net worth improves with age. The opposite is often true: as premiums rise and health declines, the net worth drag of insurance becomes more pronounced. A 65-year-old with a $300/month supplemental policy might see their medical insurance net worth decline by $10,000 annually if they hit the plan’s lifetime limits. The final myth is that self-insuring is always cheaper. While it may work for the ultra-wealthy, the tail risk—a single $500,000 medical event—can outweigh the savings from skipping coverage entirely.Myth 1: More Coverage Always Means Higher Net Worth
The assumption that medical insurance net worth improves with comprehensive coverage ignores the law of diminishing returns. A platinum PPO might cover 90% of costs, but the remaining 10%—often the most critical services—can still bankrupt a middle-class family. The net worth impact isn’t just about premiums; it’s about liquidity shocks. A policy with a $2,000 deductible might seem affordable until a $100,000 treatment leaves a $98,000 gap after insurance pays its share. The real net worth isn’t in the policy itself but in how it interacts with emergency funds, investments, and debt structures. Data from the Urban Institute shows that households with medical insurance net worth strategies—such as pairing high-deductible plans with health savings accounts (HSAs)—recover from medical bankruptcies at a 40% higher rate. The key isn’t coverage breadth but coverage alignment with financial buffers. A $50,000 policy with a $15,000 deductible may be worthless if the insured lacks liquid assets to cover the gap. The net worth of medical insurance isn’t in the policy document but in the financial architecture surrounding it.Myth 2: Employer Plans Are Enough for Long-Term Security
Employer-sponsored insurance is often treated as a financial safety net, but its limitations become clear during job transitions or pre-existing condition exclusions. A 2022 survey by the Commonwealth Fund found that 45% of Americans with employer plans faced coverage gaps when switching jobs, leaving them vulnerable to medical insurance net worth erosion. The problem isn’t the plan itself but the assumption of permanence. High-deductible employer plans may save on premiums, but they shift risk onto the employee—often without the liquidity reserves to handle surprises. The net worth of an employer plan isn’t in the benefits but in the employer’s solvency. If a company downsizes or files for bankruptcy, its insurance obligations may vanish, leaving former employees exposed. For freelancers or gig workers, the medical insurance net worth equation becomes even more precarious: without employer subsidies, they must self-fund policies that may not cover pre-existing conditions or specialty treatments. The real cost isn’t the premium but the hidden risk of inadequate coverage.Myth 3: Self-Insuring Saves More Than Traditional Plans
The allure of self-insuring—setting aside cash to cover medical costs—appeals to those who distrust insurance companies. However, the medical insurance net worth math rarely works out in favor of self-insurers. A healthy 40-year-old might save $2,000/year in premiums by self-insuring, but a single $200,000 cancer treatment could wipe out a decade’s savings. The net worth of self-insurance isn’t in the upfront savings but in the ability to absorb catastrophic risk, which few individuals can sustain. Industry actuaries estimate that 90% of self-insured households underestimate their exposure to long-tail medical costs. A policy that costs $1,000/month might pay out $50,000 in claims—but if the insured lacks that liquidity, the net worth of the decision is negative. The true net worth of medical insurance isn’t in avoiding premiums but in avoiding financial ruin.
What Holds Up to Scrutiny
At its core, medical insurance net worth is about risk transfer efficiency. The most resilient strategies combine high-deductible plans with tax-advantaged accounts (like HSAs) and umbrella liability policies to shield assets. The net worth isn’t in the insurance itself but in how it decouples medical risk from financial risk. For example, a family that maxes out an HSA ($8,300/year for 2024) and pairs it with a $5,000 deductible plan creates a liquidity buffer that preserves net worth during emergencies."Medical insurance isn’t an expense; it’s an investment in financial immunity. The families who treat it as a line item lose. The ones who treat it as a wealth-preservation tool win." — Dr. David Cutler, Harvard Economist & Healthcare Policy ExpertThe evidence supports this approach. A study in the Journal of Health Economics found that households using medical insurance net worth strategies—such as capturing HSA triple tax benefits—reduced their out-of-pocket medical costs by 42% over five years. The net worth gain comes not from the insurance but from tax savings, investment growth, and avoided liquidity crises.
| Common Belief | What the Evidence Says |
|---|---|
| More coverage = higher net worth | Coverage must align with liquidity. A $100,000 policy with a $50,000 deductible offers little net worth protection. |
| Employer plans are sufficient | 45% of employer-plan holders face gaps during job transitions, eroding net worth. |
| Self-insuring is cheaper | 90% of self-insured households underestimate catastrophic risk, leading to net worth destruction. |
| HSAs are only for retirees | HSAs grow tax-free; a $10,000 balance at 7% return becomes $200,000+ over 30 years. |
| Net worth improves with age | Premiums rise 10-15% per decade, while health declines, increasing net worth drag. |
Why the Confusion Persists
The medical insurance net worth paradox thrives because the financial industry treats insurance as a cost center rather than a wealth-protection tool. Advisors focus on premiums per month instead of premiums per dollar of risk transferred. Meanwhile, insurers structure policies to maximize revenue—not to optimize net worth. The result is a system where consumers overpay for partial coverage or underpay for catastrophic exposure, both of which deplete net worth. Cultural factors also play a role. In the U.S., healthcare is framed as a consumer good rather than a financial risk. People buy premiums like they buy groceries, without considering the opportunity cost of funds tied up in deductibles. Meanwhile, in countries with universal healthcare, the concept of medical insurance net worth is irrelevant because the state absorbs the risk. The confusion isn’t just about numbers—it’s about how societies value health as an economic asset.
Conclusion
Medical insurance net worth isn’t a niche financial metric—it’s the difference between financial resilience and catastrophic loss. The policies that preserve wealth aren’t the most expensive or the most comprehensive; they’re the ones aligned with liquidity, tax efficiency, and risk tolerance. Ignoring this dynamic leaves individuals exposed to medical debt spirals, asset seizures, and retirement plan raids. The solution lies in treating medical insurance as a wealth-management tool, not just a bill. That means stress-testing policies against worst-case scenarios, leveraging tax-advantaged accounts, and avoiding the illusion of self-insurance. The net worth of medical coverage isn’t in the policy itself but in how it integrates with the broader financial ecosystem. Those who master this equation don’t just survive medical crises—they thrive through them.Comprehensive FAQs
Q: How does medical insurance affect my overall net worth?
A: Medical insurance net worth impact comes from three levers: premiums (a direct cash outflow), out-of-pocket maximums (liquidity risk), and tax benefits (HSAs, employer subsidies). A policy that saves $1,000/month in premiums but requires a $15,000 deductible may reduce net worth if you lack emergency funds. Conversely, a high-deductible plan paired with an HSA can increase net worth over time due to tax-free growth.
Q: Is it better to pay high premiums or accept a high deductible?
A: The net worth trade-off depends on your liquidity and risk tolerance. High premiums reduce immediate out-of-pocket costs but erode net worth over time. High deductibles save on premiums but increase liquidity risk. The optimal balance is a deductible you can cover without selling assets, paired with a catastrophic rider to cap exposure.
Q: Can medical debt really destroy my net worth?
A: Yes. The American Journal of Public Health found that 66% of medical bankruptcies stem from uninsured or underinsured individuals. Even with insurance, gaps in coverage (e.g., mental health, maternity) can lead to asset seizures, credit damage, and retirement plan loans. The net worth of medical insurance isn’t just about premiums—it’s about avoiding the financial fallout of illness.
Q: How do HSAs improve medical insurance net worth?
A: HSAs offer triple tax benefits: contributions are tax-deductible, growth is tax-free, and withdrawals for medical expenses are tax-free. A family maxing out HSAs ($8,300/year in 2024) and investing the funds at 7% annual return could accumulate $200,000+ over 30 years—increasing net worth while reducing medical costs. The net worth gain comes from tax savings and compound growth, not just coverage.
Q: What’s the biggest mistake people make with medical insurance?
A: Assuming coverage equals protection. A policy that covers 90% of costs is worthless if the remaining 10% wipes out savings. The net worth mistake isn’t choosing the wrong plan—it’s choosing a plan without a liquidity backup. Many underestimate deductibles, copays, and non-covered services, leading to unexpected net worth destruction when a claim hits.
Q: Should I self-insure if I’m young and healthy?
A: Self-insuring is highly risky unless you have liquid assets exceeding $500,000 and no dependents. A single $1 million medical event (e.g., organ transplant, rare disease) could eliminate net worth in one event. Even for the wealthy, self-insurance is a gamble—and the net worth cost of losing that bet is permanent.
